
For a healthy, non-smoking married female in 2026, a $100,000 term life insurance policy typically costs between $8 and $25 per month. Prices vary based on age and term length, with a 30-year-old often paying around $10 monthly, while a 50-year-old may see premiums closer to $35 for the same coverage level.
Purchasing life insurance is a cornerstone of a sound financial plan, especially for married women who often balance career responsibilities, household management, and long-term family goals. A $100,000 policy is frequently viewed as a "starter" amount or a supplemental layer of protection designed to cover specific debts, funeral expenses, or a short-term income gap. In 2026, the insurance market has become more streamlined, with data-driven underwriting allowing for highly competitive rates for women, who statistically enjoy longer life expectancies than men.
Key Factors Determining Premiums for Married Women
The cost of life insurance is not a flat rate; it is a calculated risk assessment performed by actuarial experts. For a married female seeking $100,000 in term coverage, several primary levers determine the final monthly or annual premium. Understanding these factors allows you to anticipate your costs and potentially improve your eligibility for lower rates.
Age and Mortality Risk
Age is the single most significant predictor of life insurance costs. As you age, the statistical probability of a claim being filed increases. In 2026, insurance companies continue to use granular age-based tables. For every year you delay purchasing a policy, you can expect the premium to increase by approximately 5% to 8%. Younger women in their 20s and 30s are viewed as "low risk," which is why their premiums are often lower than a monthly subscription to a streaming service.
Health Status and Medical History
During the application process, you will be assigned an underwriting class. These classes range from "Preferred Plus" (excellent health) to "Standard" or "Substandard" (higher risk). Factors such as Body Mass Index (BMI), blood pressure, and cholesterol levels are scrutinized. For married women, specific health history—including history of gestational diabetes or postpartum complications—may be reviewed, though many carriers in 2026 have modernized their views on these temporary conditions, provided they have resolved.
Tobacco and Nicotine Usage
Smoking remains the most expensive habit in the eyes of an insurer. A married female who smokes can expect to pay two to three times more for a $100,000 policy than a non-smoker. This includes not just traditional cigarettes but also vaping and nicotine replacement therapies, depending on the specific carrier's guidelines. Even occasional use can disqualify an applicant from "Preferred" rates.
The Impact of Marital Status
While marital status itself is not a direct "rating factor" in the same way health is, it often correlates with lower premiums through indirect means. Married individuals often lead more stable lifestyles, which can translate to fewer high-risk behaviors and better health maintenance. Some insurers also offer "spousal discounts" or "multi-policy discounts" if both partners purchase coverage through the same carrier.
Average Monthly Cost Breakdown by Age and Term (2026 Rates)
The following table provides estimated monthly premiums for a $100,000 term life insurance policy for a married female in excellent health (Preferred Non-Smoker). These figures represent industry averages for 2026 and are intended for comparison purposes.
| Age at Issue | 10-Year Term | 20-Year Term | 30-Year Term |
|---|---|---|---|
| 25 Years Old | $7.50 | $9.25 | $12.50 |
| 35 Years Old | $8.75 | $11.50 | $16.00 |
| 45 Years Old | $14.50 | $21.00 | $32.00 |
| 55 Years Old | $28.00 | $44.00 | $68.00* |
| 65 Years Old | $62.00 | $115.00 | N/A |
*Note: 30-year terms may have limited availability for individuals over age 55 depending on the carrier.
As the table illustrates, the "locked-in" nature of term insurance makes early purchase highly advantageous. A 35-year-old woman who secures a 30-year term will pay roughly $16 per month until she is 65, whereas waiting until age 55 to buy a 10-year term would cost significantly more for a much shorter duration of protection.
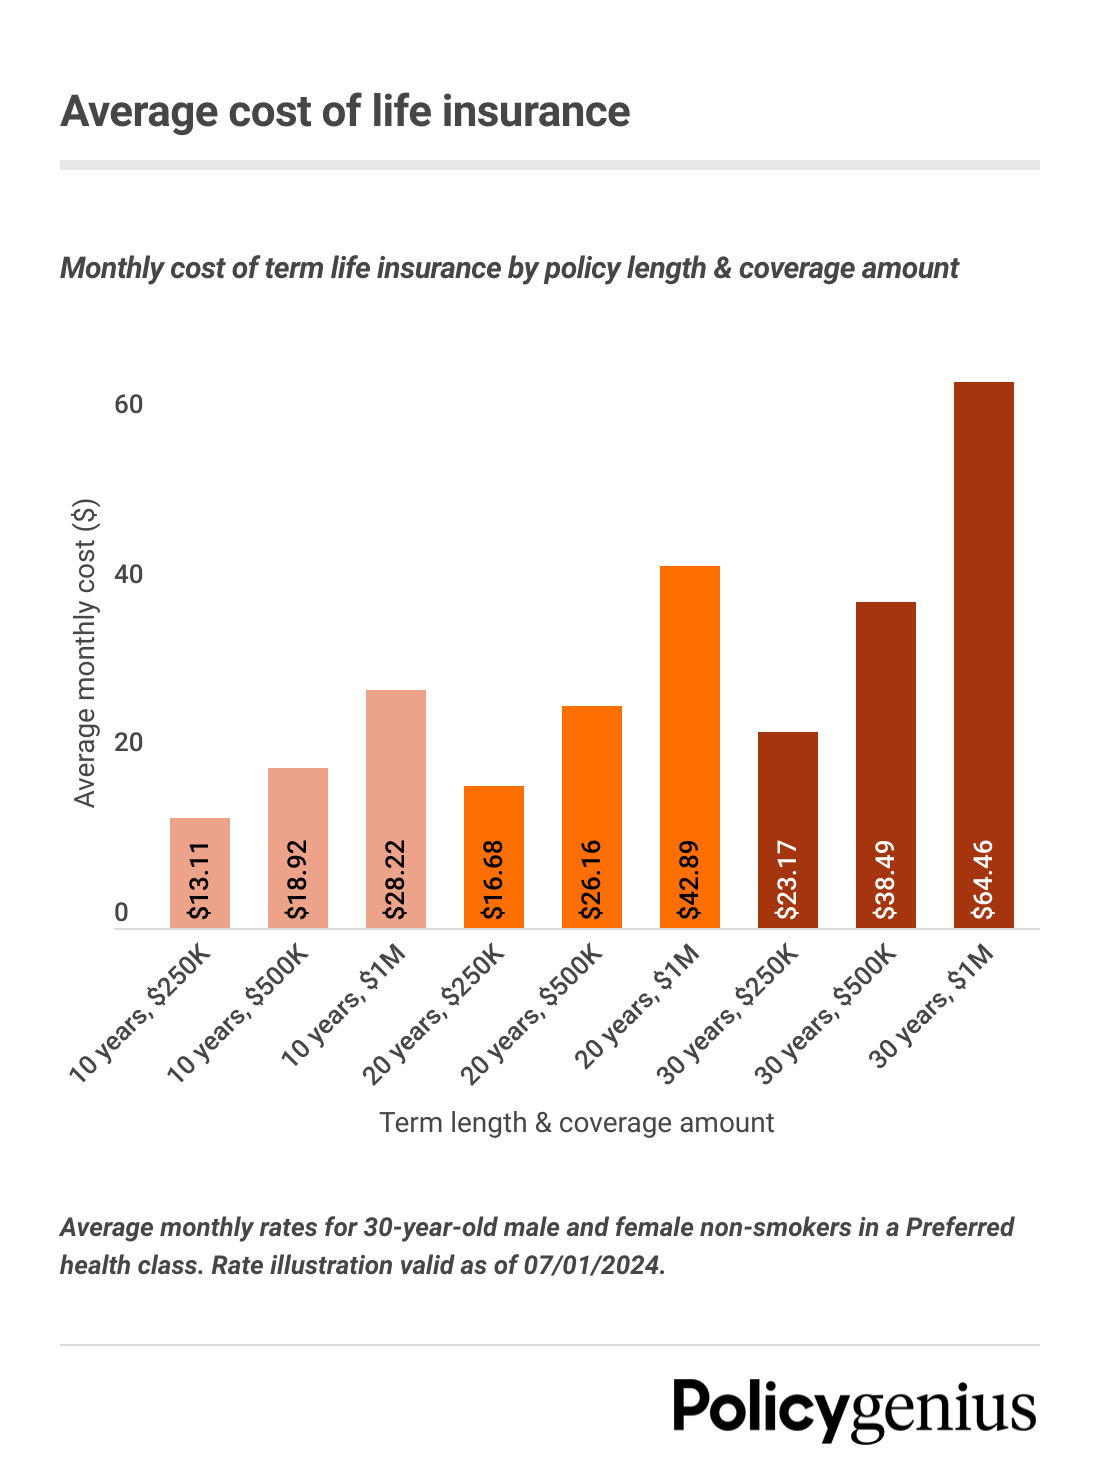
Why Gender and Marital Status Impact Life Insurance Costs
Gender plays a pivotal role in insurance pricing due to biological and statistical realities. In the United States, according to the Social Security Administration’s mortality data, women consistently outlive men by an average of five to seven years. Because women are statistically likely to pay premiums for a longer period before a death benefit is paid out, insurers offer them lower rates than men of the same age and health profile.
For a married woman, the "insurable interest" is often clear. If her income or domestic labor (childcare, household management) were suddenly lost, the surviving spouse and children would face significant financial hardship. Insurers look favorably upon clear-cut financial needs, as it reduces the likelihood of speculative or fraudulent applications.
Furthermore, being married often opens the door to "laddering" strategies. For example, a married couple might decide the wife needs $100,000 of her own coverage to supplement a larger employer-provided policy. This "supplemental" approach is a cost-effective way to ensure that even if she changes jobs (losing her group coverage), the family still has a $100,000 safety net in place.
Is a $100,000 Policy Sufficient for Your Needs?
While $100,000 sounds like a substantial sum, it is important to evaluate it against the economic realities of 2026. For many married women, $100,000 serves a specific, limited purpose rather than a total replacement of lifetime earnings.
Final Expenses and Debt
The average cost of a funeral and related end-of-life expenses in 2026 can exceed $12,000 to $15,000. Additionally, many married couples carry credit card debt, auto loans, or personal loans. A $100,000 policy is excellent for wiping these slate clean, ensuring the surviving spouse isn't burdened by high-interest liabilities during a time of grief.
Mortgage Protection
If a couple has a small remaining balance on their home, a $100,000 policy can be used to pay off the mortgage entirely or pay the monthly installments for several years. However, if the mortgage is $400,000 or more, a $100,000 policy would only provide a temporary buffer.
Childcare and Education
For a stay-at-home parent, the cost of replacing their labor—childcare, transportation, and home maintenance—is often underestimated. According to the U.S. Bureau of Labor Statistics, the cost of professional childcare has risen steadily. A $100,000 death benefit might cover only two to four years of full-time childcare for multiple children, depending on the region.
The "DIME" Formula
To see if $100,000 is enough, experts recommend the DIME formula:
- Debt: Total of all non-mortgage debts.
- Income: Your annual salary multiplied by the years your family needs support.
- Mortgage: The balance remaining on your home.
- Education: The estimated cost of tuition for your children.
If your DIME total is significantly higher than $100,000, you may want to consider a larger policy. Surprisingly, the jump from $100,000 to $250,000 in coverage often only adds a few dollars to the monthly premium because of the way insurance companies "band" their pricing.
How Underwriting Classes Influence Your Final Quote
When you apply for a $100,000 policy, you aren't just "approved" or "denied." You are categorized. In 2026, many companies use "Accelerated Underwriting," which uses algorithms to scan your electronic health records, motor vehicle reports, and prescription history to assign a class without requiring a blood draw or physical exam.
- Preferred Plus: You have an ideal weight-to-height ratio, no chronic health issues, a clean driving record, and no family history of early-onset heart disease or cancer. You will receive the lowest possible rates.
- Preferred: Excellent health, but perhaps one minor issue, such as well-controlled cholesterol or a slightly higher-than-perfect BMI.
- Standard Plus: Better than average health, but perhaps a family history of illness or a more significant lifestyle factor.
- Standard: You are of average health and weight. You may have a manageable chronic condition like high blood pressure.
- Substandard (Rated): If you have significant health risks (e.g., Type 2 diabetes, history of heart disease), you may be "rated." This means your premium will be the standard rate plus a percentage (e.g., Standard + 25%).
For a married woman, pregnancy can occasionally complicate underwriting. If you are currently pregnant, some insurers will postpone your application until after delivery, while others will offer coverage based on your pre-pregnancy weight and health markers, provided there are no complications like pre-eclampsia.
Strategic Ways to Lower Your Life Insurance Premiums
Even though $100,000 policies are already affordable, there are several ways to ensure you are getting the best possible value in 2026.
- Pay Annually: Most insurance companies charge a "fractional fee" for the convenience of monthly payments. By paying your premium once a year, you can save between 2% and 8% on the total annual cost.
- Bundle Policies: Check with your home and auto insurance provider. While they may not always have the absolute lowest base rate for life insurance, the "bundling discount" applied to your other policies might make them the most cost-effective overall choice.
- Improve Your Health Metrics: If you are on the border of a better underwriting class, small changes can matter. For instance, quitting smoking for at least 12 months can move you from "Smoker" rates to "Non-Smoker" rates, saving you thousands of dollars over the life of the policy.
- Buy While Young: As shown in the cost table, the premium for a 25-year-old is nearly half the cost of a 45-year-old. Locking in a 20- or 30-year term early ensures your family is protected at a "low-cost" rate regardless of health changes you may experience later in life.
- Compare "No-Exam" Options: In 2026, no-exam policies are highly competitive. However, if you are in exceptionally good health, a traditional fully-underwritten policy (with a medical exam) might still yield a slightly lower premium because the insurer has more certainty about your health status.
Term vs. Permanent Life Insurance for Married Women
While the focus here is on term life insurance, it is worth noting why term is often the preferred choice for a $100,000 policy for married women.
Term Life Insurance is designed to last for a specific period (e.g., 10, 20, or 30 years). It is "pure protection." If you die during the term, the $100,000 is paid to your beneficiaries tax-free. If you outlive the term, the coverage ends. This simplicity makes it the most affordable option.
Permanent (Whole) Life Insurance lasts your entire life and includes a "cash value" component that grows over time. However, for a $100,000 policy, a whole life premium could be 10 to 15 times more expensive than a term premium. For most married women, the goal is to protect the family during "vulnerable years" (while children are young or a mortgage is active), making term insurance the more efficient financial tool.
Frequently Asked Questions
Does my husband need to be involved in the application?
While your husband does not need to sign your application, he is often named as the primary beneficiary. In "community property" states, or depending on specific carrier requirements, a spouse might need to acknowledge the policy, but the medical and financial underwriting is based solely on you, the applicant.
What happens to the $100,000 policy if we get divorced?
A life insurance policy is an individual contract. If you own the policy, you retain it after a divorce. You have the right to change the beneficiary from your former spouse to your children, a trust, or another individual. The premiums will remain the same regardless of your change in marital status.
Can I get a $100,000 policy if I am a stay-at-home mother?
Yes. Insurers in 2026 recognize the immense economic value of a stay-at-home spouse. Most companies will allow a non-working spouse to carry a death benefit equal to that of the working spouse, up to certain limits. A $100,000 policy is almost always approved for stay-at-home mothers without requiring proof of earned income.
Will my premiums go up during the term?
No. One of the primary benefits of "Level Term" life insurance is that your premiums are guaranteed to remain exactly the same for the entire duration of the term (e.g., 20 years). Even if your health declines after the policy is issued, the insurance company cannot increase your rate or cancel your coverage as long as you pay the premiums.
Is $100,000 too little coverage?
For many, yes. If you have young children and a mortgage, $100,000 may only cover a few years of expenses. However, having $100,000 in coverage is infinitely better than having none. It is often used to "fill the gap" or provide a dedicated fund for a specific purpose, such as a child’s college education or a spouse’s transition period.
Final Recommendation
For a married female in 2026, a $100,000 term life insurance policy is an incredibly affordable way to provide a financial safety net. If you are in your 30s or 40s and in relatively good health, you can likely secure this coverage for the cost of a few cups of coffee per month.
The best next step is to obtain a formal quote that uses your specific health history and age. Because rates increase every year, and because an unexpected change in your health could make coverage more expensive or harder to get later, it is generally recommended to lock in a policy as soon as the need is identified. Start by comparing three different carriers or working with an independent broker who can shop your application across multiple companies to find the "Preferred Plus" rating you deserve.
Image Gallery
Select an image to open it in a new tab.
Simon Caldwell
Enterprise Technology and Systems Editor
