
Determining whether Kotak Life Insurance is a suitable provider requires a balanced assessment of its solvency ratios, claim settlement performance, product diversity, and digital service infrastructure. As of 2026, the company maintains a strong position in the Indian market, characterized by consistent regulatory compliance, a broad spectrum of protection and investment plans, and a robust online ecosystem designed to simplify policy management for diverse demographic segments.
Understanding the Role of Kotak Mahindra Life Insurance
Kotak Mahindra Life Insurance Company Limited is a subsidiary of the Kotak Mahindra Bank, one of India’s premier financial institutions. Because life insurance is a long-term commitment—often spanning decades—evaluating a provider is not merely about looking at the current year’s performance, but rather the insurer’s historical stability, financial health, and commitment to policyholder obligations.
The "goodness" of an insurance company is primarily measured through its capacity to honor claims when the time comes. This is dictated by the insurer's financial underwriting practices, investment management, and operational efficiency. In the Indian context, the Insurance Regulatory and Development Authority of India (IRDAI) sets strict guidelines that all life insurers, including Kotak, must follow to ensure they remain solvent and capable of fulfilling their liabilities.
Evaluating Financial Strength and Credibility
When assessing if Kotak Life Insurance is a reliable choice, the first metric to examine is the Solvency Ratio. This figure represents the insurer’s ability to meet its long-term debt obligations. IRDAI mandates a minimum solvency ratio of 1.50 for all insurance companies. Kotak Life has historically maintained a ratio significantly higher than this mandate, signaling a conservative and secure approach to asset management.
Furthermore, the company operates under the backing of the Kotak Mahindra Group, providing it with a layer of institutional stability that standalone insurance entities might not possess. This financial backing is critical for customers who prioritize the long-term safety of their capital, especially for those opting for endowment plans or unit-linked insurance plans (ULIPs) where the investment horizon is extended.

Claim Settlement Ratio: The Ultimate Test
The Claim Settlement Ratio (CSR) is the percentage of claims an insurance company settles against the total claims received in a financial year. While a high CSR is a positive indicator, it should be analyzed alongside the "Amount Settlement Ratio" and the "Repudiation Rate."
Kotak Life Insurance consistently posts competitive claim settlement figures. However, as a policyholder, it is essential to understand that a claim can be rejected if there is a non-disclosure of material facts during the initial application process. Therefore, the "goodness" of the company is also tied to your own diligence in providing accurate information regarding your health, occupation, and lifestyle at the time of policy inception.
Product Portfolio and Suitability
The variety of products offered by Kotak Life is vast, catering to different financial life stages. Understanding these categories is vital to determining if the company aligns with your specific needs:
1. Term Insurance Plans
These are pure protection plans that provide a high life cover at a relatively low premium. Kotak offers various term plans with options for return of premium, critical illness riders, and accidental death benefits. These are generally recommended for individuals who need to secure their family’s future against the loss of income.
2. Unit-Linked Insurance Plans (ULIPs)
These products combine protection with investment. Your premiums are invested in market-linked funds. These are suitable for investors with a moderate to high risk appetite who are looking for long-term wealth creation alongside life cover.
3. Endowment and Money-Back Plans
These are traditional, lower-risk products that offer a guaranteed payout at the end of the policy term or at regular intervals. They are favored by conservative investors who prioritize capital preservation and predictable returns.
4. Retirement and Annuity Plans
Designed for long-term corpus building, these plans ensure a steady stream of income during retirement years.
Comparison Table: How to Evaluate Your Options
When comparing Kotak Life Insurance against other players in the market, consider the following parameters. While specific numbers change annually, the criteria for evaluation remain constant.
| Feature | Importance | What to Look For |
|---|---|---|
| Claim Settlement Ratio | High | Consistency over the last 5 years. |
| Solvency Ratio | High | Well above the 1.50 regulatory floor. |
| Customer Service | Medium | Accessibility of branch offices and digital portals. |
| Rider Availability | Medium | Customization options for disability/illness. |
| Fund Performance | Variable | Past performance of ULIP funds (for ULIP users). |
Digital Infrastructure and Service Efficiency
In 2026, the quality of a life insurance provider is heavily defined by its digital interface. Kotak Life has invested significantly in its mobile application and web portal. Policyholders can perform tasks such as premium payments, nominee updates, address changes, and fund switching without visiting a branch.
For many users, the "goodness" of an insurance company is defined by how frictionless the premium payment process is. Integration with Unified Payments Interface (UPI) and internet banking through the broader Kotak ecosystem makes the payment experience largely seamless. If you prefer a digital-first experience, Kotak’s current infrastructure is designed to minimize administrative friction.
Potential Limitations and Considerations
Despite its positive market standing, no insurance company is a "one-size-fits-all" solution. You may find limitations in specific areas:
- Premium Pricing: Depending on your age and health profile, Kotak’s premiums might occasionally be higher than "online-only" boutique insurers. It is always wise to obtain quotes for the same coverage amount across multiple providers.
- Underwriting Strictness: Like all reputable insurers, Kotak maintains rigorous underwriting standards. If you have pre-existing medical conditions, the underwriting process may result in a higher premium (loading) or the exclusion of specific health conditions from coverage.
- Product Complexity: ULIPs and certain endowment plans can be complex. If you are not familiar with market volatility or policy charges (like mortality charges and fund management charges), ensure you review the "Benefit Illustration" document provided at the time of purchase.
Frequently Asked Questions
Does Kotak Life Insurance cover COVID-19 related claims?
Yes, the company adheres to IRDAI guidelines, which mandate that all health and life insurance policies must cover COVID-19 related claims, provided the policy was active and the diagnosis meets the standard medical documentation requirements.
Can I port my policy to another insurer if I am unhappy with Kotak?
While you can choose not to renew your policy, "portability" as it exists in health insurance does not apply to life insurance in the same manner. If you switch life insurance providers, you typically have to buy a fresh policy, which will be subject to new underwriting and age-based premium rates.
What happens if I miss a premium payment?
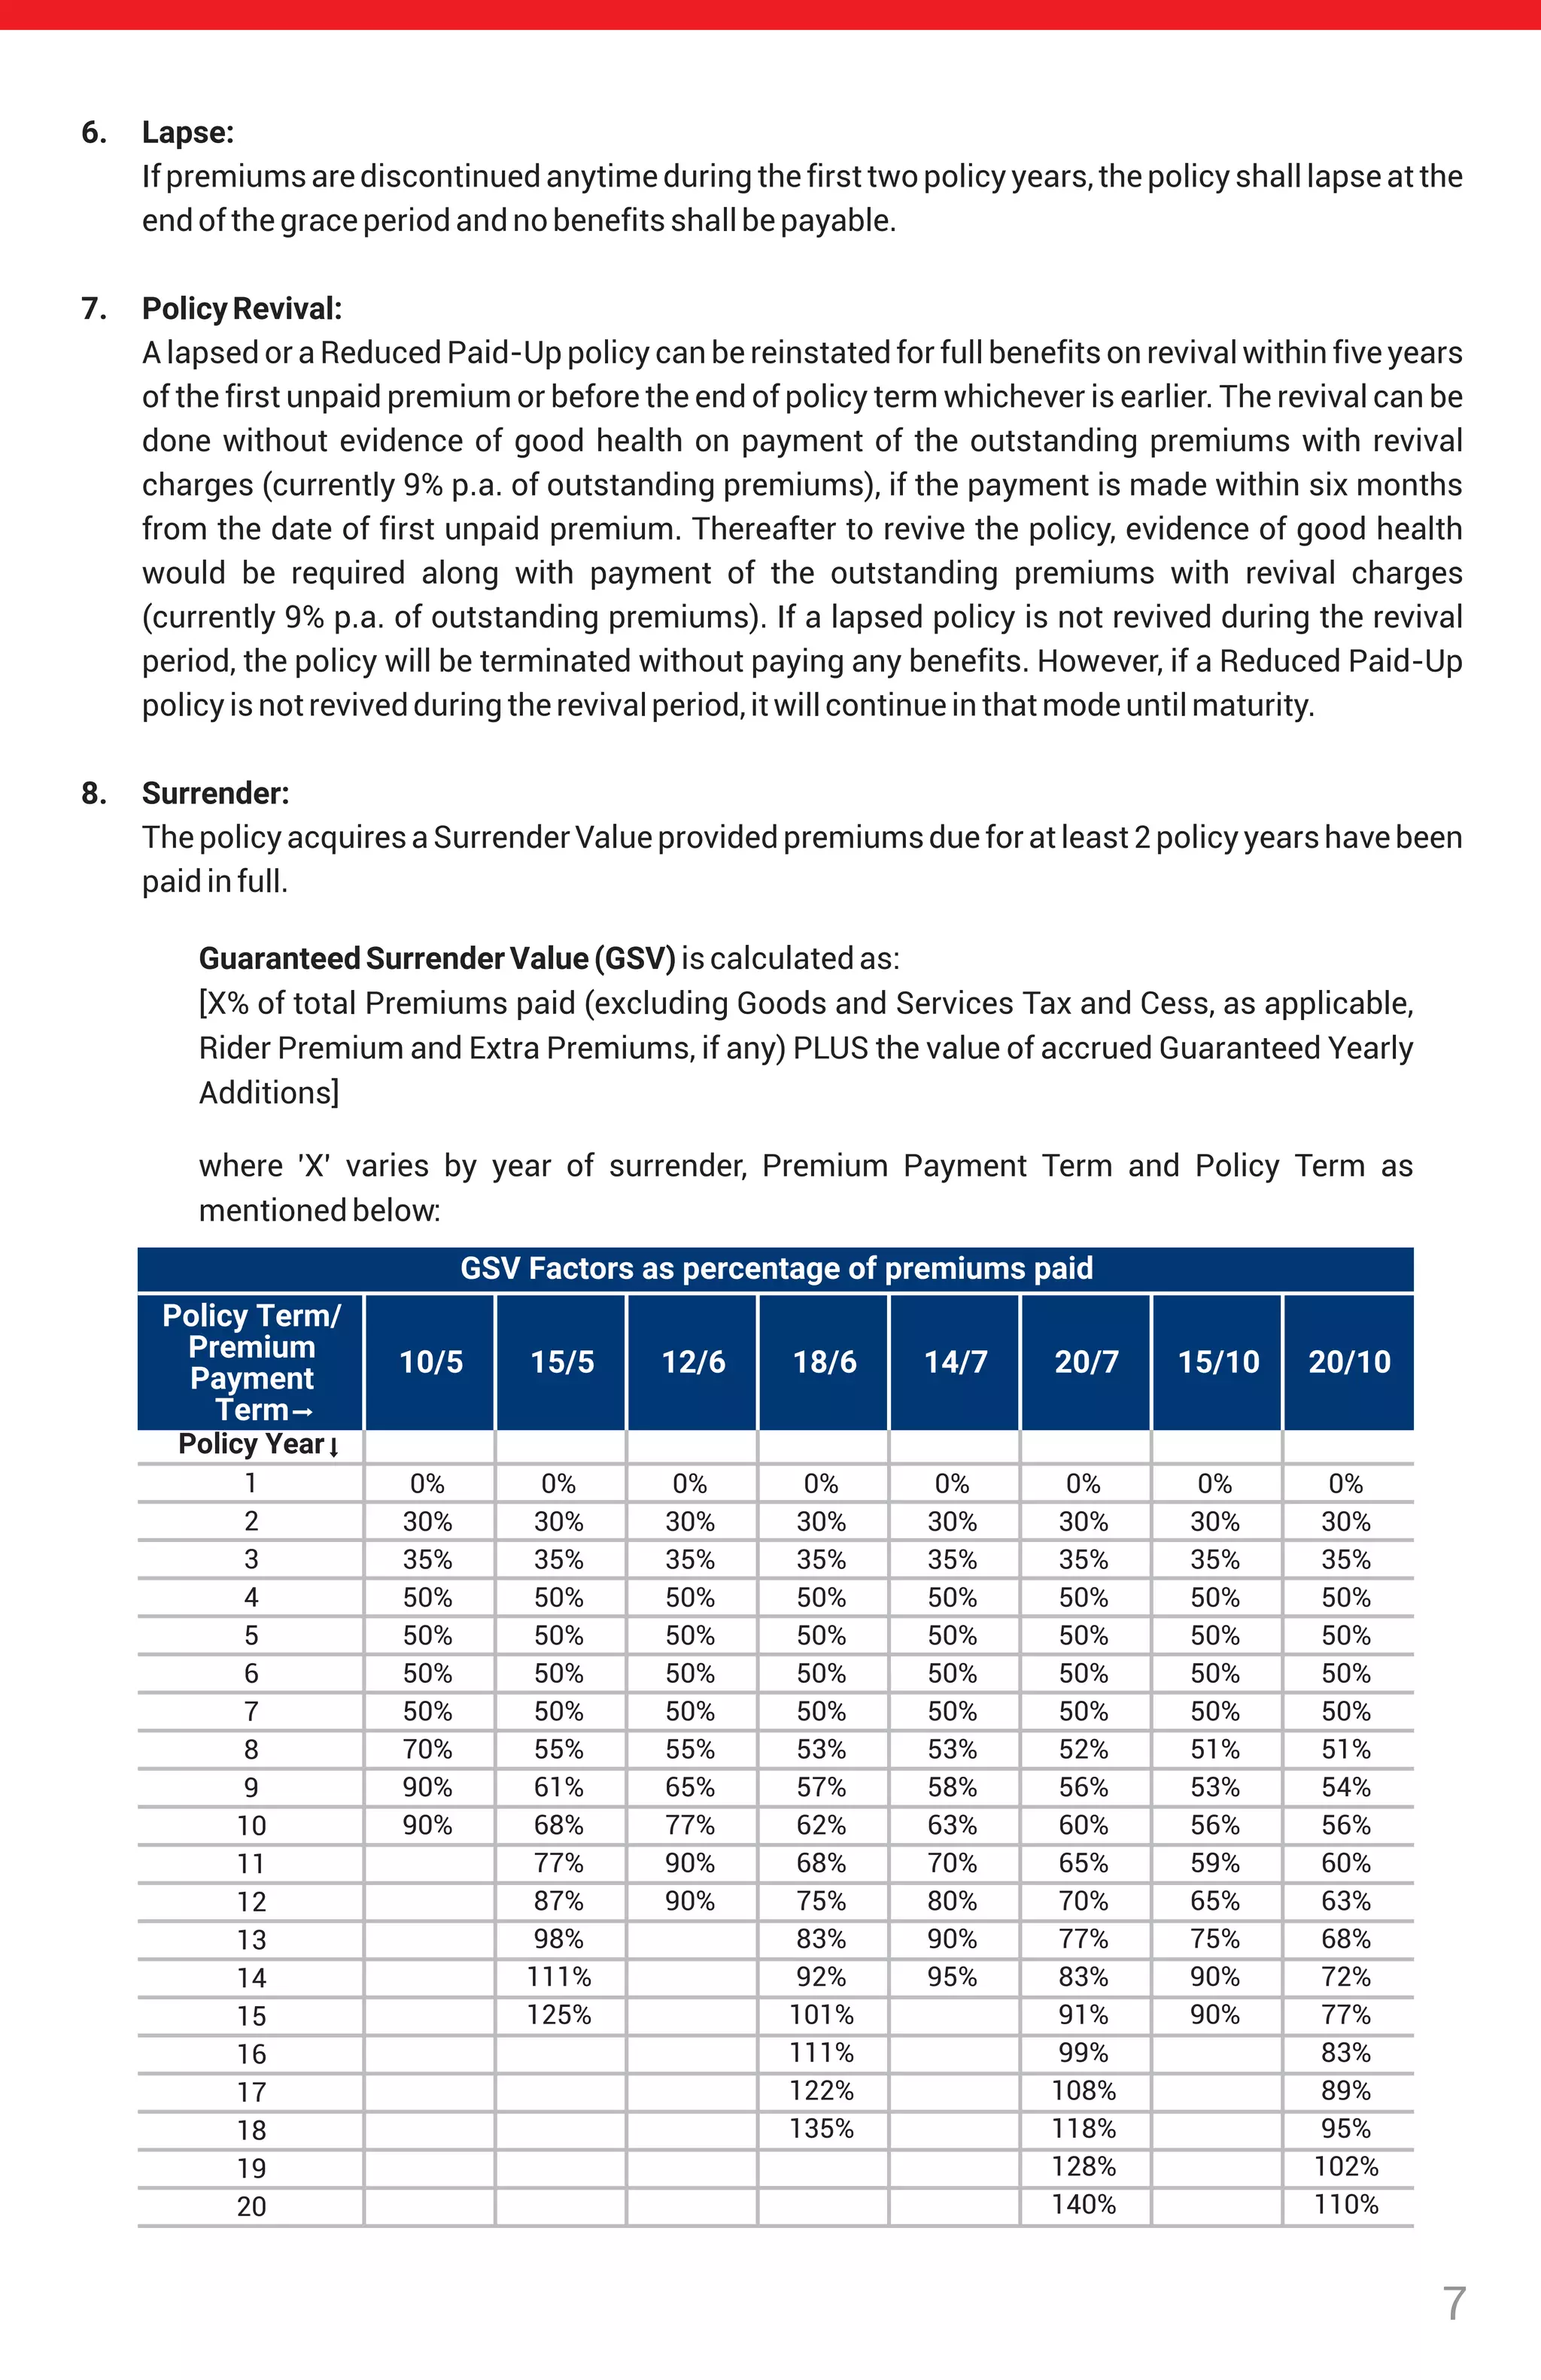
Kotak Life Insurance typically offers a "grace period" (usually 15 to 30 days) to pay overdue premiums. If payment is not made within this period, the policy may lapse. Lapsed policies can often be revived by paying the outstanding premiums with interest, provided you remain eligible under the insurer's revival terms.
Is it better to buy offline or online?
Buying online is generally more cost-effective as it removes middleman commissions and allows for a transparent view of the plan’s features. However, if you require personalized financial planning or have a complex tax/estate situation, speaking to an authorized advisor may be beneficial.
How are the funds in Kotak ULIPs managed?
The funds are managed by professional fund managers who allocate assets based on the fund's objective (equity, debt, or balanced). You can view the historical performance of these funds on the official Kotak Life website, which details the portfolio composition and risk profile.
Final Recommendation: Steps to Take
Determining if Kotak Life Insurance is good for you is a personal financial decision. Before committing to a plan, follow these steps:
- Define your goal: Are you looking for pure protection (Term), or an investment-linked return (ULIP/Endowment)?
- Request an illustration: Always request a customized "Benefit Illustration" which outlines the premium, the sum assured, and the potential returns or charges over the life of the policy.
- Read the exclusions: Pay close attention to the "Exclusions" section of the policy document—this defines the scenarios under which the insurer will not pay the claim (e.g., suicide within the first year, certain high-risk activities).
- Compare: Get quotes for the same sum assured from two other providers to ensure the pricing aligns with your budget.
If you prioritize a brand with a strong regulatory track record, institutional backing, and modern digital tools, Kotak Life Insurance is a highly competitive and reliable choice in the current market. Ensure your medical history is disclosed honestly during the application to guarantee that your future claims are processed without complication.
Image Gallery
Select an image to open it in a new tab.



Celine Dubois
Contemporary Living and Global Arts Columnist
