Auto Insurance in Portage, IN: A Guide to Coverage and Compliance
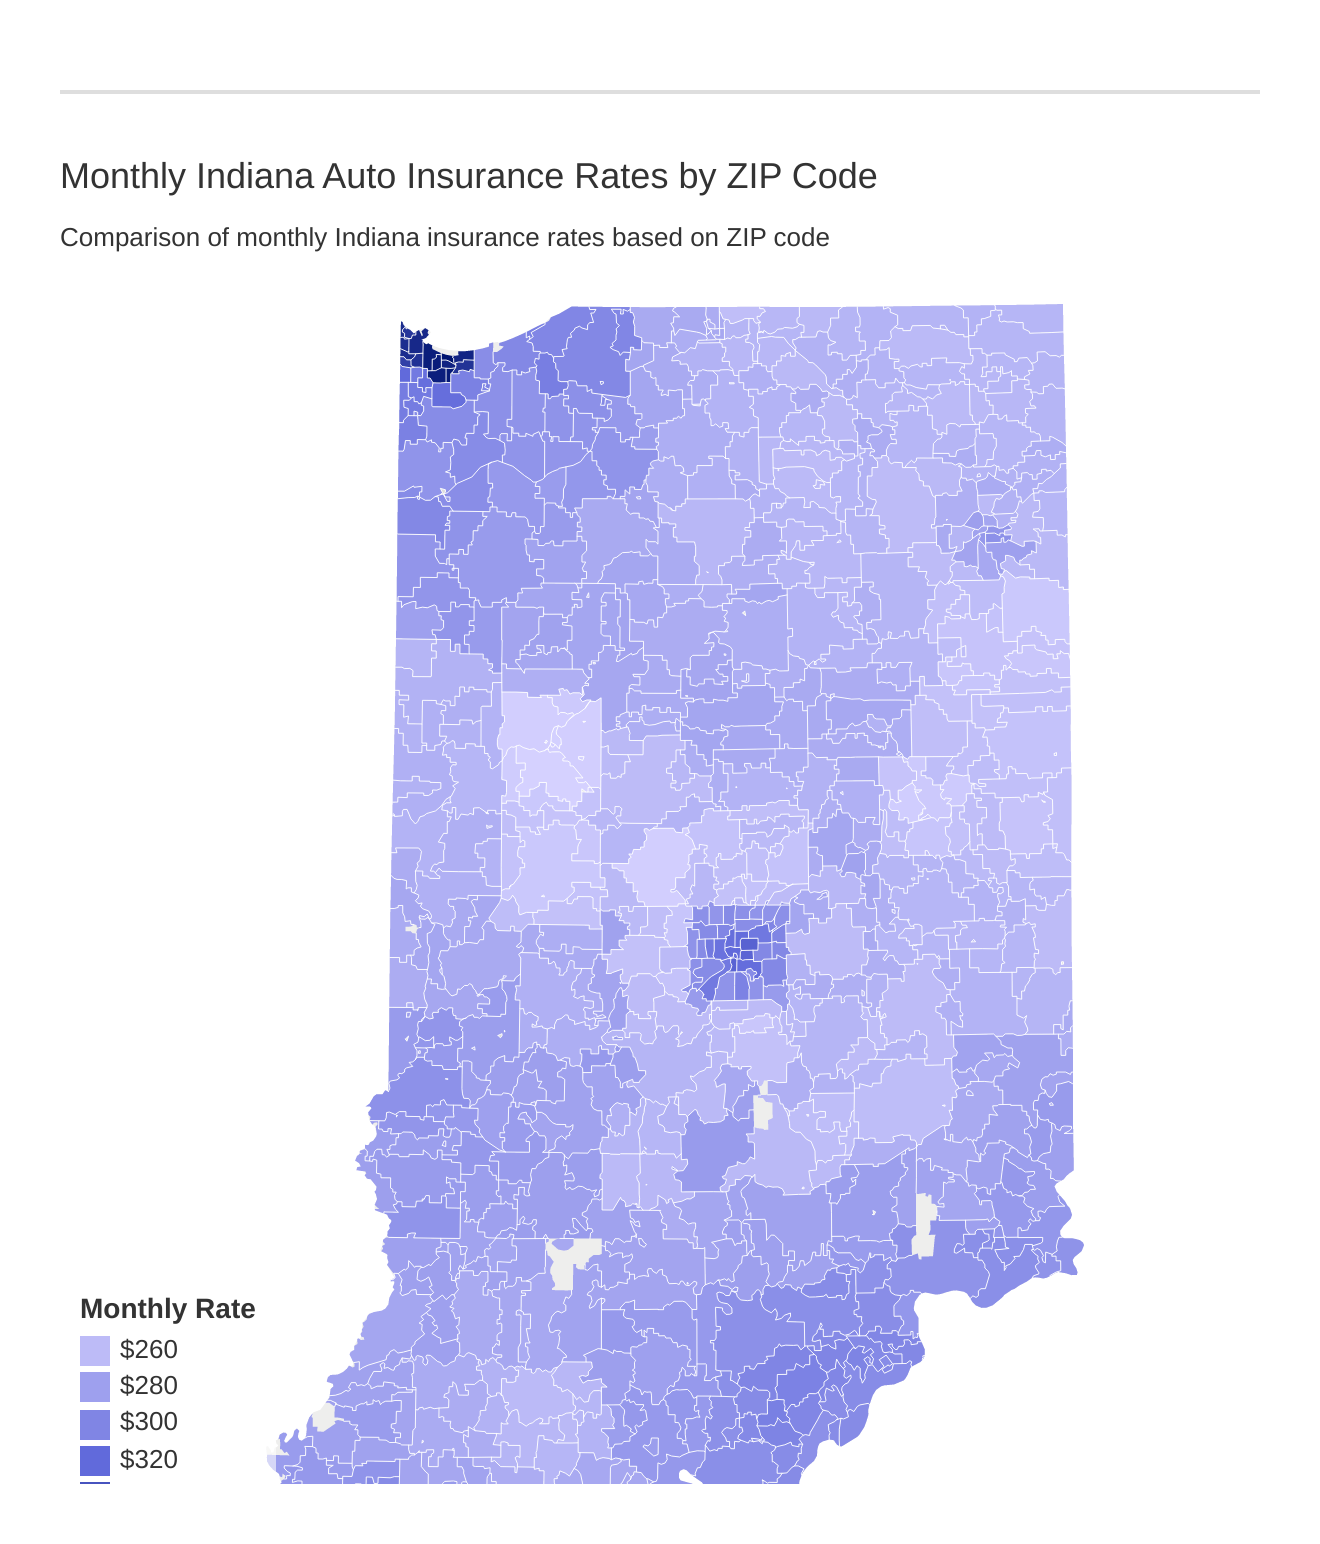
Securing auto insurance in Portage, Indiana, requires maintaining state-mandated liability minimums while navigating the unique regional factors of the Northwest Indiana market. Residents must carry proof of insurance at all times to satisfy Indiana law, with premiums influenced by local driving patterns, vehicle types, and personal risk factors. Comparing quotes from multiple carriers remains the most effective strategy for managing costs while ensuring adequate financial protection.
Understanding Indiana’s Mandatory Liability Requirements
To operate a motor vehicle legally in Portage, Indiana, you must comply with the state’s financial responsibility laws. The Indiana Bureau of Motor Vehicles (BMV) dictates that every driver must maintain a policy that meets or exceeds specific liability coverage thresholds. These requirements exist to ensure that if you are at fault in an accident, there is a baseline of funds available to cover the injuries or property damage caused to others.
The current minimum liability coverage requirements in Indiana are:
- $25,000 for bodily injury or death of one person in an accident.
- $50,000 for total bodily injury or death of two or more people in an accident.
- $25,000 for property damage per accident.
It is critical to understand that these are "minimums," not recommendations. If you are involved in a significant collision, the costs of medical bills and vehicle repairs often exceed these amounts. Any expenses above your policy limits become your personal financial responsibility. Many financial advisors and insurance professionals in Portage recommend "full coverage," which includes optional protections like collision and comprehensive insurance, to avoid out-of-pocket vulnerability.
Regional Factors Influencing Portage Premiums
Portage is located in Porter County, a part of the greater Northwest Indiana region. Your insurance premium is calculated based on risk, and geography plays a significant role in this assessment. Several factors specific to this area affect the rates offered by major insurance carriers:
Traffic Density and Commuting Patterns
Portage residents often commute toward the Chicago metropolitan area or other hubs within the industrial corridor of Northwest Indiana. High traffic volume on major arteries, such as I-94 and U.S. Route 6, increases the statistical probability of fender-benders and multi-vehicle accidents. Insurance underwriters analyze regional crash data to set base rates for the specific zip codes covering Portage.
Weather-Related Risks
Indiana experiences significant seasonal volatility, including heavy winter snows, icy road conditions, and occasional severe thunderstorms. These conditions contribute to higher claim frequencies for property damage and collision incidents. Insurance companies adjust their pricing models to account for the increased risk of weather-related losses in Northern Indiana compared to more temperate regions of the state.
Vehicle Theft and Vandalism Rates
While Portage maintains different crime statistics than larger urban centers like nearby Gary or Hammond, insurance carriers monitor theft and vandalism trends at the municipal and county levels. If a specific area reports a higher frequency of vehicle break-ins or total vehicle thefts, premiums for comprehensive coverage—which covers theft—may reflect that elevated risk.
Essential Components of an Auto Insurance Policy
When shopping for coverage in Portage, you will encounter various types of insurance. Understanding the purpose of each ensures you are not under-insured or paying for coverage you do not need.
Liability Insurance (Mandatory)
This is the baseline coverage that protects your assets if you are found legally responsible for an accident. It covers the other party's medical expenses and property repair. It does not cover your own vehicle or your own medical bills.
Collision Coverage (Optional but Recommended)
If your car is damaged in a collision with another vehicle or a stationary object, this coverage pays for the repairs. If you are still making payments on your vehicle, your lender will almost certainly require you to maintain collision insurance to protect their collateral.
Comprehensive Coverage (Optional but Recommended)
Often referred to as "other than collision" coverage, this pays for damages to your vehicle resulting from events outside of your control, such as theft, fire, vandalism, falling tree limbs, or collisions with animals.
Uninsured and Underinsured Motorist Coverage
This is an invaluable addition in Indiana. If you are struck by a driver who lacks insurance or carries only the legal minimum—which may not be enough to cover your damages—this coverage bridges the gap. It ensures that you do not have to pay for someone else’s lack of financial responsibility.
Medical Payments Coverage (MedPay)
MedPay covers medical expenses for you and your passengers regardless of who is at fault in an accident. It can be particularly useful for covering deductibles or co-pays associated with your primary health insurance policy.
Strategies for Managing Insurance Costs in Portage
Insurance premiums are not fixed; they are a result of complex algorithms that weigh your personal history against local risk factors. By understanding how to influence these factors, you can effectively manage your annual expenditure.
Periodic Quote Comparison
The insurance market is highly competitive. Carriers adjust their rates frequently based on their own internal loss projections. Experts recommend obtaining new quotes every 12 to 24 months, even if you are satisfied with your current provider. This helps ensure that you are still receiving a market-competitive rate.
Bundling Policies
Most major insurers offer significant discounts if you bundle your auto insurance with homeowners, renters, or life insurance. By consolidating your policies under one provider, you often gain access to "multi-policy" discounts that can lower your overall annual premium by 10% to 20%.
Maintaining a Clean Driving Record
This is the single most effective way to keep premiums low. Traffic violations, speeding tickets, and "at-fault" accidents remain on your record for several years. Insurance companies treat these marks as indicators of future risk. Defensive driving courses, if approved by your insurer, can sometimes offset the impact of minor infractions.
Adjusting Your Deductibles
Your deductible is the amount you pay out-of-pocket before your insurance kicks in. Raising your deductible (e.g., from $500 to $1,000) will typically lower your monthly or semi-annual premium. However, you must ensure you have the funds available to cover that deductible in the event of an accident.
Comparison Table: Common Coverage Scenarios
| Coverage Type | What It Covers | Mandatory in IN? | Recommended For |
|---|---|---|---|
| Bodily Injury Liability | Other person's medical costs | Yes | All drivers |
| Property Damage Liability | Other person's vehicle/property | Yes | All drivers |
| Collision | Repairs to your own vehicle | No | Newer/Financed vehicles |
| Comprehensive | Theft, fire, natural disasters | No | Newer/High-value vehicles |
| Uninsured Motorist | Your costs if hit by uninsured | No | All drivers |
Handling Claims and Verifying Coverage
If you are involved in an accident in Portage, the first step is to ensure everyone is safe. Once the immediate danger has passed, you must exchange insurance information with the other driver. In Indiana, the standard procedure involves providing your policy number and the name of your insurance company.
It is important to remember that Indiana is a "fault" state. This means the driver who is responsible for the accident is also responsible for the damages. If you believe you are not at fault, it is essential to document the scene, take photographs, and collect contact information from any witnesses.
Verification of Insurance
The Indiana BMV utilizes an online verification system to ensure all registered vehicles remain insured. If you cancel your insurance or if your policy lapses, the insurance provider is required to report this to the state. Failure to maintain continuous coverage can result in the suspension of your driver’s license and vehicle registration. If you receive a notice from the BMV regarding a lack of insurance, do not ignore it. Contact your insurance agent immediately to verify that your policy status is active and correctly reported.
Frequently Asked Questions
Does my credit score affect my car insurance rates in Portage?
Yes. Indiana law allows insurance companies to use credit-based insurance scores as one factor in determining premiums. While not the only factor, individuals with higher credit scores generally see lower premiums, as statistical models correlate high credit scores with lower insurance claim frequency.
What should I do if I cannot find an affordable insurance policy?
If you have a poor driving record or other issues that make it difficult to find coverage in the voluntary market, you may be eligible for the Indiana Automobile Insurance Plan (INAIP). This is an assigned-risk pool that ensures high-risk drivers can still obtain the mandatory minimum liability coverage. Speak with a licensed insurance agent in Portage for guidance on accessing this program.
Are there specific discounts for safe drivers in Indiana?
Most insurers offer "telematics" programs, where a small device or mobile app tracks your driving habits—such as hard braking, speed, and time of day you drive. Safe driving behaviors can earn you significant discounts, sometimes up to 30%, upon policy renewal.
Does the age of my vehicle impact my comprehensive and collision costs?
Yes. As a vehicle ages, its actual cash value (ACV) decreases. Because collision and comprehensive insurance only pay out up to the ACV of the vehicle, the cost of these coverages often declines as the car gets older. Eventually, you may decide to drop these coverages entirely on an older vehicle, though you must always maintain the state-mandated liability insurance.
Is gap insurance necessary for my Portage commute?
Gap insurance is beneficial if you have a loan or lease on a vehicle and the amount you owe is higher than the car's current market value. If your car is totaled, standard insurance pays only the market value, leaving you to pay the difference to the lender. Gap insurance covers this "gap."
Next Steps for Portage Drivers
To begin the process of securing or optimizing your auto insurance, start by gathering your current policy declarations page and your vehicle's VIN. Use these to request quotes from at least three different reputable providers to establish a price baseline. Review your coverage limits to ensure they align with your personal net worth and risk tolerance. If you have questions about specific regional requirements, contact a local, licensed independent insurance broker in Portage who can provide personalized advice based on your driving history and vehicle type.
Image Gallery
Select an image to open it in a new tab.

Omar Farooq
EdTech Innovation and Virtual Pedagogy Journalist
