
When you experience windshield damage, your coverage through Westfield Insurance depends on the specific terms of your policy, your deductible selection, and the laws of your state. In many cases, glass repair or replacement is handled under your Comprehensive coverage, which may require you to pay a deductible unless you have added specific glass-related endorsements or reside in a state with mandatory glass repair laws.
How Comprehensive Coverage Applies to Windshield Damage
For most policyholders at Westfield Insurance, windshield breakage is classified as a "Comprehensive" claim. Comprehensive coverage, often referred to as "other-than-collision" coverage, is designed to protect your vehicle from damage caused by events beyond your control, such as theft, fire, vandalism, falling objects, or hitting an animal. Windshield damage, particularly from road debris, rocks, or weather-related incidents, falls squarely into this category.
It is important to distinguish Comprehensive coverage from Collision coverage. If your windshield breaks as a result of an accident where your vehicle hits another object or vehicle, the claim would typically fall under your Collision coverage. However, the vast majority of windshield claims result from stone chips or cracks sustained while driving on a highway, which triggers the Comprehensive portion of your policy.
When you file a claim for windshield damage, Westfield Insurance will evaluate the extent of the damage. Minor chips and small cracks that do not obstruct the driver’s line of sight can often be repaired through specialized resins. Larger cracks or damage that compromises the structural integrity of the glass usually necessitate a full windshield replacement. Because this is a standard insurance process, the insurer will typically work with preferred glass repair networks to ensure quality standards and pre-negotiated pricing.
The Role of Your Deductible
The most common point of confusion regarding insurance coverage for auto glass is the role of the deductible. Your deductible is the out-of-pocket amount you agreed to pay toward a loss before the insurance company begins to pay for the remaining repair or replacement costs.
For many standard auto insurance policies, the Comprehensive deductible applies to windshield claims just as it would to a stolen stereo or a damaged bumper. If your deductible is $500 and the cost to replace a high-tech windshield (which may include sensors for lane-departure warnings or rain-sensing wipers) is $700, the insurance company would pay $200. If the repair cost is only $150, you would be responsible for the full amount, as it falls below your deductible threshold.
However, some policyholders choose to carry a "full glass" endorsement or a "zero-deductible glass" option if their specific policy configuration allows for it. These additions essentially waive the deductible specifically for glass repairs. If you are unsure whether your policy includes a glass-specific waiver, you must review your "Declarations Page," which summarizes your coverages and limits.
State-Specific Laws and Mandatory Coverage
Your physical location plays a significant role in how Westfield Insurance handles your windshield claim. Certain states, such as Arizona, Florida, Kentucky, Massachusetts, Minnesota, and South Carolina, have laws that may impact how insurance companies apply deductibles to glass repair or replacement.
In states like Florida, for example, insurance companies are generally prohibited from applying a deductible to windshield repair or replacement claims. This is a legislative requirement intended to ensure that drivers keep their windshields clear for safety reasons. If you live in a state with these mandates, Westfield Insurance will follow the local statutes regarding glass coverage, even if your policy documents state that a deductible applies. When you report your claim, the insurance representative or the glass shop will verify your residency and the state’s requirements to determine if your deductible should be waived.
Assessing the Cost of Repair vs. Replacement
The modern automotive landscape has changed the financial implications of a broken windshield. Vehicles manufactured in recent years are often equipped with Advanced Driver Assistance Systems (ADAS). These systems rely on cameras and sensors mounted directly behind or within the windshield glass.
When a windshield with these features is replaced, the new glass must be calibrated precisely to ensure that systems like lane-keep assist, adaptive cruise control, and automatic emergency braking function correctly. This process is known as "ADAS recalibration." It is a technical necessity, not an optional add-on, and it can significantly increase the total cost of a windshield replacement claim.
| Factor | Repair (Chip/Minor Crack) | Replacement (Major Damage) |
|---|---|---|
| Typical Cost | Low (Often covered or low out-of-pocket) | High (Often exceeds standard deductibles) |
| Time Required | 30 to 60 minutes | Several hours (plus calibration time) |
| Safety Impact | Restores integrity for small chips | Required for structural safety |
| Deductible | Often waived in many states | Usually applied per policy terms |
Steps to Take When Your Windshield Breaks
If your windshield is damaged, immediate action can prevent a minor chip from spreading into a large, irreparable crack due to temperature fluctuations or road vibrations.
- Assess the damage: Determine if the damage is within the driver's line of sight and how large the crack is. If the damage is larger than a dollar bill or spans across the driver's view, the windshield likely requires a full replacement.
- Contact your agent or the claims department: Before proceeding with a third-party repair shop, contact your Westfield Insurance agent or the company’s claims reporting portal. They can provide guidance on preferred vendors and clarify your specific deductible requirements.
- Use a preferred vendor: Insurance companies often have agreements with national glass repair networks. Using these providers can simplify the billing process, as they are accustomed to working directly with the insurer and handling the claim submission on your behalf.
- Document everything: Take clear photographs of the damage from both the inside and outside of the vehicle. Keep a record of the date and location where the incident occurred, as this may be required for your claim file.
- Schedule the repair promptly: Delaying repair can lead to moisture entering the crack or the damage expanding, which might lead to a full windshield replacement being necessary rather than a simple, cost-effective resin repair.
Common Misconceptions About Glass Claims
A common myth is that filing a windshield claim will automatically result in a rate increase at your next renewal. While this varies by state and individual claims history, many insurance carriers, including Westfield, often treat minor glass claims differently than at-fault accident claims. A single claim for a rock chip or a shattered windshield due to debris is generally viewed differently than a collision claim, which reflects your overall risk as a driver.
Another misunderstanding is that all windshields are created equal. As previously noted, the inclusion of ADAS technology means that you cannot simply purchase the cheapest aftermarket glass. If your vehicle has factory safety features, you may need Original Equipment Manufacturer (OEM) or OEM-equivalent glass to ensure the sensors work accurately. Always confirm with your glass technician that they are aware of your vehicle’s specific safety feature requirements.
Frequently Asked Questions
Does Westfield Insurance cover "pitting" or minor scratches on the windshield? Generally, insurance covers damage that impairs your visibility or compromises the structural integrity of the glass. Minor cosmetic pitting or light surface scratches caused by normal wear and tear are usually considered maintenance issues rather than covered insurance losses.
Can I choose my own glass repair shop? Most policies allow you to choose a repair facility; however, using an insurance-recommended shop ensures that the costs are pre-approved and the quality of work is backed by the insurer. If you choose an out-of-network provider, you may need to pay out-of-pocket and seek reimbursement, subject to the "prevailing competitive price" in your area.
How does my vehicle's age affect the repair process? For older vehicles, standard aftermarket glass is often readily available and affordable. For newer, high-tech vehicles, the requirement for ADAS recalibration and specialized glass components makes the professional expertise of the installer much more important than it would be for a vintage car.
Will my premiums increase if I report a glass claim? Every claim is reviewed, but single, non-preventable Comprehensive claims are rarely treated with the same severity as at-fault collisions. You should consult your specific policy documents or speak with your agent to understand how your specific claims history might influence your future premium adjustments.
What happens if I ignore a small chip? A small chip is highly susceptible to temperature changes. If you run your heater or air conditioner on a day with extreme exterior temperatures, the thermal shock can cause a small chip to propagate into a large crack, eventually requiring a full, and much more expensive, replacement.
Next Steps for Policyholders
If you have discovered damage to your vehicle's windshield, the most effective next action is to verify your current policy documents. Look specifically for the "Comprehensive" section on your Declarations Page to determine your deductible amount. Following this, contact your Westfield Insurance agent to confirm if your policy includes any specific glass endorsements that might waive your deductible. By addressing the damage promptly, you ensure the safety of your vehicle and minimize the likelihood of a more expensive repair down the road.
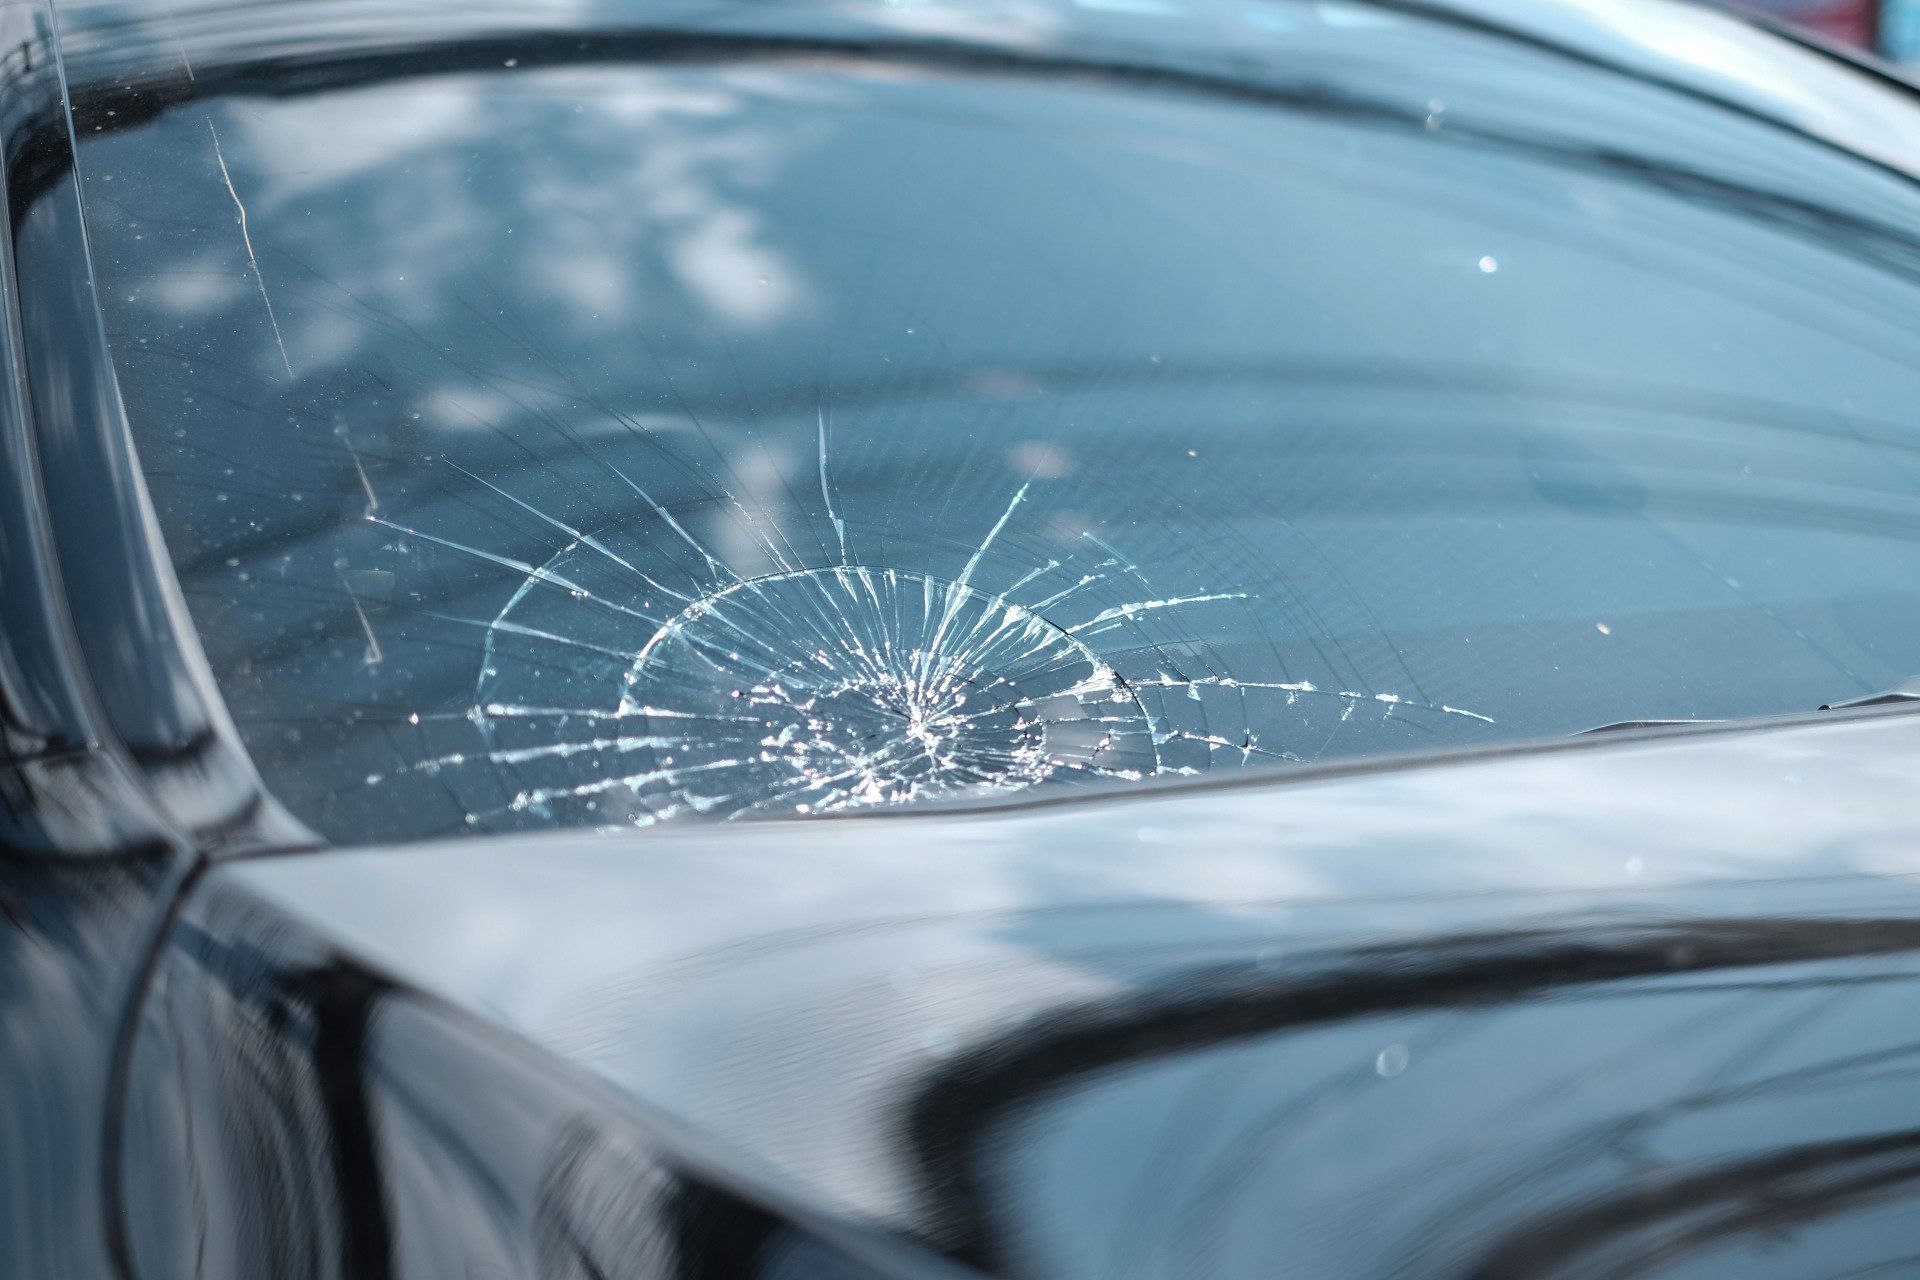
Image Gallery
Select an image to open it in a new tab.




Vivian Cho
Executive IT and Emerging Technologies Reporter
