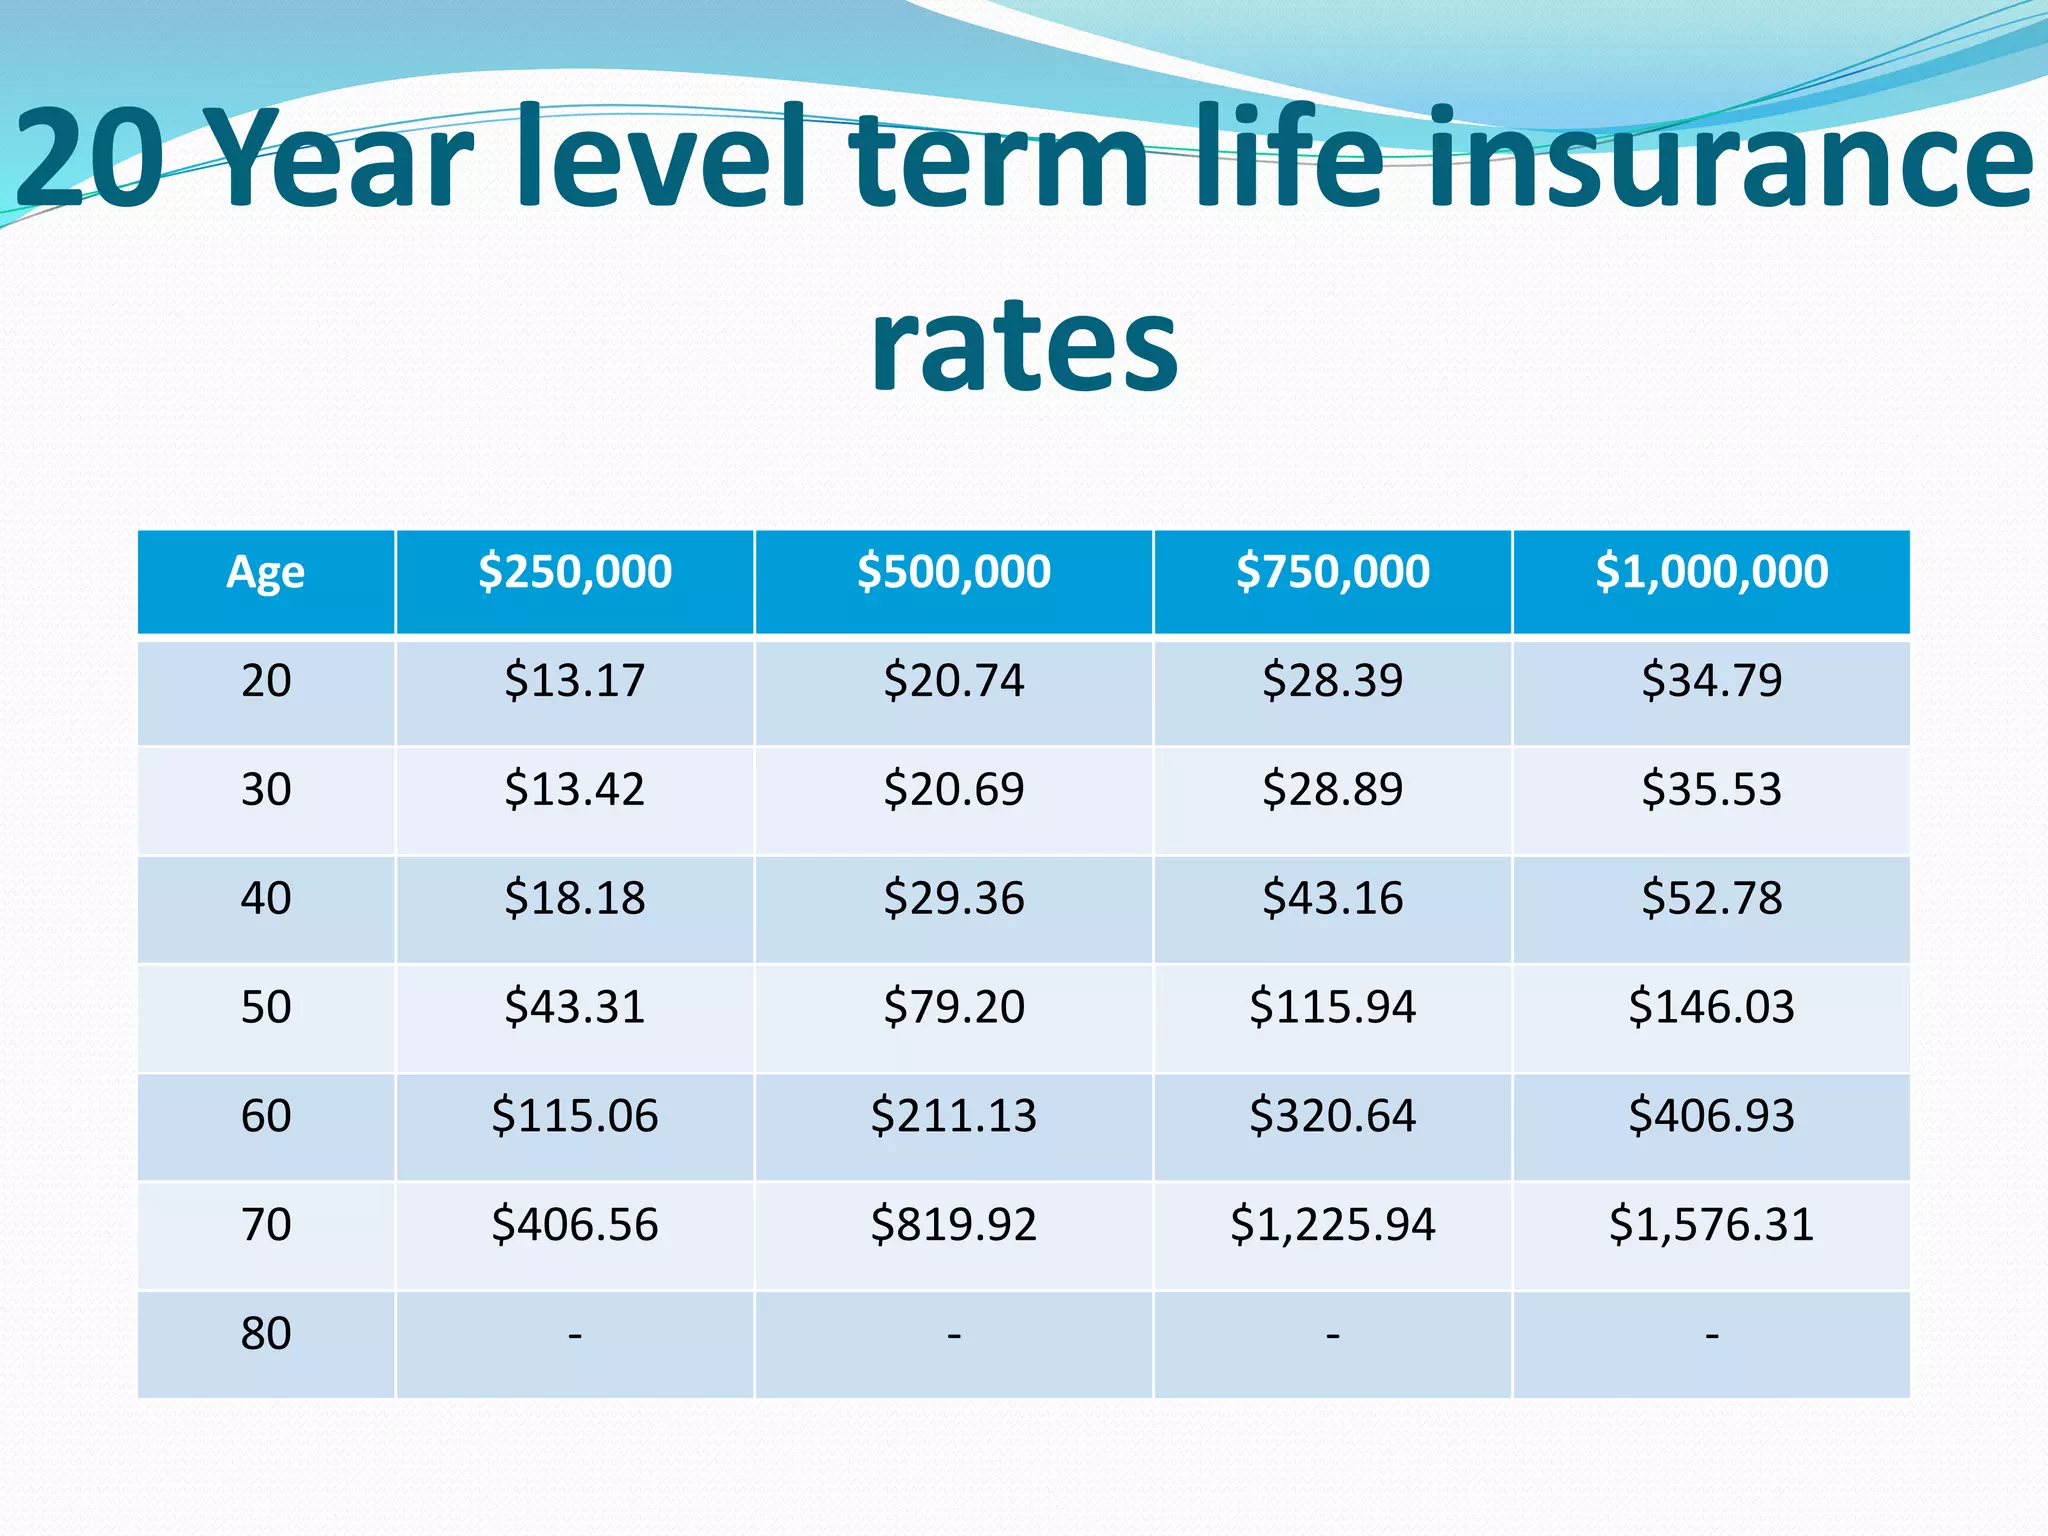
A term insurance rates calculator is a digital tool that allows consumers to estimate the cost of temporary life insurance coverage by inputting personal variables such as age, coverage amount, term length, and health profile. By processing these parameters, the calculator generates projected monthly or annual premium quotes, enabling users to evaluate different policy configurations before applying for coverage.
Understanding Term Life Insurance and Premium Calculation
Before interacting with any rate calculator, it is vital to understand what term life insurance is and how insurers calculate its cost. Term life insurance provides financial protection for a specified period, such as 10, 20, or 30 years. If the insured individual passes away during this active term, the designated beneficiaries receive a tax-free death benefit. Unlike permanent life insurance, term policies do not build cash value; they are purely designed to offer high coverage limits at affordable rates during peak financial responsibility years, such as when raising children or paying off a mortgage.
Insurance companies use complex actuarial tables to determine these costs, balancing the statistical probability of a claim against the premiums collected. When you use a rate calculator, you are essentially running your specific demographic and health data through a simplified version of these underwriting algorithms. While online calculators provide accurate estimates based on standard rate classes, final pricing is subject to official medical underwriting, which may include a paramedical exam, medical history reviews, and verification of lifestyle habits.
Essential Information Needed Before Using a Calculator
To obtain the most accurate estimates from a term insurance rates calculator, you should gather specific personal and financial details beforehand. Inaccurate inputs lead to unrealistic premium expectations, as minor variations in age or health classifications can significantly shift projected costs.
Personal and Demographic Metrics
- Age and Date of Birth: Rates increase incrementally with every year of age. Many insurers use "nearest age" calculation methods, meaning your rate is based on the age you are closest to.
- Gender: Actuarial data indicates that women generally have longer life expectancies than men, resulting in lower baseline term insurance rates for females at identical ages and health levels.
- Tobacco and Nicotine Use: Smoking, vaping, or using cigars, chewing tobacco, or nicotine replacement therapies drastically increases life insurance premiums—often doubling or tripling the cost compared to non-user rates.
Financial and Coverage Requirements
- Desired Coverage Amount (Death Benefit): The total payout your beneficiaries would receive. Calculations often rely on replacing 10 to 15 times your annual income, plus accounting for specific debts like mortgages or college tuition funds.
- Term Length: The duration of the policy. Common options include 10, 15, 20, 25, or 30 years. Choosing a longer term locks in your price for a broader timeframe but increases the baseline premium.
Basic Health and Lifestyle Profiles
- Height and Weight Proportions: Insurers use Body Mass Index (BMI) charts to evaluate health risks. Falling outside standard height-weight parameters can elevate your estimated rate class.
- General Medical History: Pre-existing conditions, ongoing prescriptions, and recent surgeries affect your preliminary risk category. Calculators usually prompt you to select a broad health tier (e.g., Preferred Plus, Preferred, Standard Plus, or Standard) rather than itemizing every condition.
- Family Medical History: A history of hereditary illnesses, such as certain cancers or heart disease occurring before age 50 or 60, can influence underwriting and baseline pricing.

Step-by-Step Guide to Using a Term Insurance Rates Calculator
Navigating a term insurance calculator effectively requires a methodical approach. While individual carrier or independent brokerage platforms vary slightly in design, the core input sequence remains consistent across the industry.
[Gather Personal Data] ➔ [Select Coverage Term & Amount] ➔ [Estimate Health Class] ➔ [Generate & Compare Quotes]
Step 1: Input Basic Demographic and Contact Information
Most online calculators require your zip code, birth date, and gender on the initial screen. Zip codes are necessary because insurance regulations and rates vary by state. While some calculators permit anonymous browsing without email submission, others require contact details to display the full quote results or to send a detailed summary.
Step 2: Define Your Coverage Parameters
Next, specify the financial scope of the policy. Enter your target death benefit amount—such as $500,000 or $1,000,000—and choose the policy duration. If you have young children, a 20- or 30-year term is typically selected to cover them until financial independence. If you are closer to retirement and seeking to cover a remaining mortgage balance, a 10- or 15-year term may be more appropriate.
Step 3: Answer Health and Lifestyle Screening Questions
The calculator will present a short questionnaire regarding your health and habits. Be prepared to answer questions concerning tobacco use, driving records (such as driving under the influence or excessive speeding tickets), and hazardous hobbies like private aviation, scuba diving, or rock climbing. Select the health category that most realistically reflects your medical history. When in doubt, select a standard tier rather than a preferred tier to avoid underestimating your potential costs.
Step 4: Review and Adjust Quote Results
Once all fields are completed, the calculator will display estimated monthly and annual premiums across various term lengths and coverage amounts. Use this interface to run comparisons. For example, check how much a 20-year term costs versus a 30-year term, or evaluate the price jump of moving from a $500,000 policy to a $1,000,000 policy.
Evaluating Calculator Outputs and Health Classifications
Insurance calculators assign your inputs to a specific underwriting health tier. Understanding these tiers helps you interpret whether the displayed quote is a best-case scenario or a realistic baseline for your situation.
| Health Classification | Risk Level | Description & Typical Characteristics |
|---|---|---|
| Preferred Plus / Elite | Lowest Risk | Exceptional health, no tobacco use, ideal height-to-weight ratio, no family history of major hereditary diseases, clean driving record, and normal blood pressure and cholesterol without medication. |
| Preferred | Below Average Risk | Very good health. May have minor, well-controlled health issues or slightly higher cholesterol, but otherwise maintains a healthy lifestyle and clean background. |
| Standard Plus | Average Risk | Good health with minor chronic conditions that are managed effectively. May be slightly outside optimal weight ranges or use minor medications. |
| Standard | Moderate Risk | Average health. May have controlled high blood pressure, elevated cholesterol, or a family history of heart disease or cancer. Common category for many applicants. |
It is important to remember that online calculators assume absolute accuracy in your self-reporting. If you estimate your blood pressure as normal, but a subsequent paramedical exam reveals elevated readings, the insurance company will adjust your final offer to a lower health tier, increasing your premium.
Common Mistakes to Avoid When Using Rate Calculators
Using a term insurance calculator incorrectly can lead to purchasing insufficient coverage or facing unexpected price hikes during formal underwriting. Avoid these common pitfalls:
- Overestimating Your Health Class: Selecting "Preferred Plus" because you exercise regularly, ignoring mild hypertension or a family medical history of cardiac issues. Always err on the side of caution or run multiple health scenarios.
- Ignoring Inflation and Financial Growth: Calculating a death benefit based entirely on current income without factoring in future salary increases, inflation, or the growing costs of living and education.
- Focusing Solely on the Lowest Price: Choosing a carrier strictly because its calculator showed the cheapest monthly premium, without researching the company's financial strength ratings or customer service reputation.
- Failing to Disclose Nicotine Use: Assuming occasional cigar use or vaping nicotine-free liquids will go unnoticed. Life insurance medical exams test for cotinine, a chemical breakdown product of nicotine, and discovering unreported usage will result in immediate application denial or steep rate recalculations.
Frequently Asked Questions
Are quotes from online term insurance calculators legally binding?
No, online quotes are estimates based on the information you provide and are not formal offers of insurance. A binding contract is established only after you complete a formal application, undergo medical underwriting, and accept the final policy offer issued by the insurance carrier's underwriters.
Do I have to submit my Social Security number to use a calculator?
Most basic term insurance rate calculators do not require a Social Security number. They can generate accurate baseline quotes using only your age, gender, zip code, and general health inputs. If a platform demands sensitive personal data before showing basic estimates, consider utilizing independent brokerages that prioritize consumer privacy.
Why do life insurance rates increase every year I wait?
Life insurance pricing is directly correlated to mortality risk. As you age, your statistical remaining life expectancy decreases, making you a higher risk to insure. Locking in a term policy earlier in life secures a lower rate that remains level throughout the entire duration of the term.
Can my rates change after I purchase a term life insurance policy?
If you purchase a level-term life insurance policy, your premium rates are guaranteed to remain the same for the duration of the chosen term (e.g., 20 years). The only way rates change is if you selected a yearly renewable term policy or if the initial quote was based on inaccurate underwriting information discovered later.
How do I transition from an online calculator estimate to a real policy?
Once you find a quote that aligns with your budget and coverage goals using a calculator, you can initiate the formal application process directly through the provider or broker. This involves completing a detailed health questionnaire, scheduling a brief paramedical visit where a nurse checks your vitals and collects blood and urine samples, and waiting for final underwriting approval.
Next Actions and Recommendations
To secure the best possible term insurance coverage, start by utilizing independent calculators that let you compare quotes across multiple top-tier carriers simultaneously. Gather your financial documents, calculate your family's true income replacement and debt-payoff needs, and run conservative health estimates. Once you identify a competitive rate and a financially stable insurance provider, submit a formal application promptly to lock in your baseline age-based pricing before your next birthday.
Image Gallery
Select an image to open it in a new tab.

Omar Farooq
EdTech Innovation and Virtual Pedagogy Journalist
