Understanding the New York Life Level Premium Convertible Term and the Level Platinum Guarantee
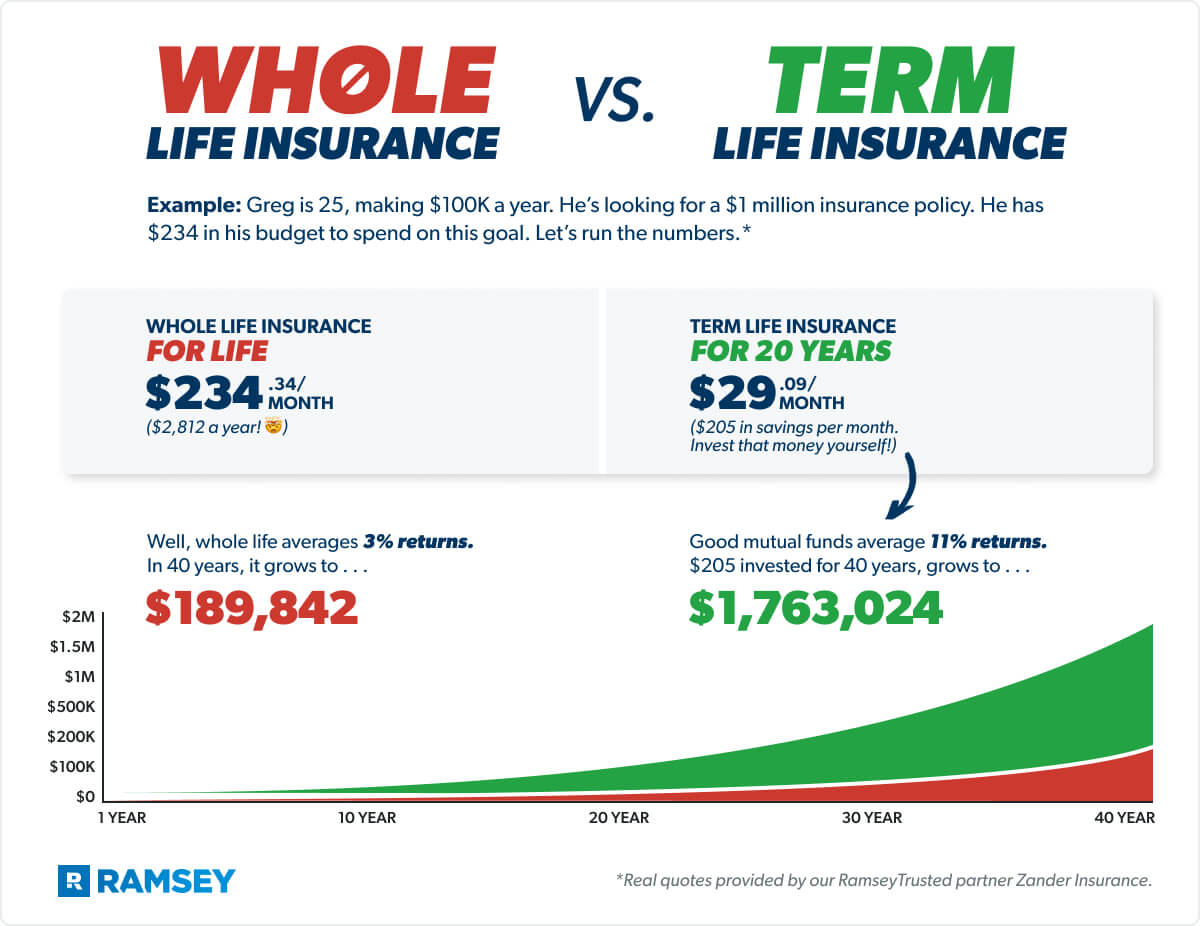
The New York Life Level Premium Convertible Term with the Level Platinum Guarantee is a life insurance policy designed to provide fixed monthly or annual costs for a specified period, typically 10, 15, or 20 years. This product guarantees that premiums will not increase during the initial term while offering a contractual right to convert the policy into permanent whole life insurance without undergoing a new medical examination.
The Foundation of New York Life’s Term Architecture
To understand the Level Platinum Guarantee, one must first look at the structure of New York Life’s term insurance portfolio. As of 2026, New York Life remains a mutual insurance company, which means it is owned by its policyholders rather than outside shareholders. This corporate structure heavily influences how they build "guarantees" into their products.
The Level Premium Convertible Term (LPCT) is the flagship term product within this ecosystem. Unlike "annually renewable" term insurance, where the price climbs every year as the insured ages, the LPCT locks in a rate based on the insured's age and health at the time of application. The "Level Platinum" designation specifically refers to the highest tier of these guarantees, ensuring that the mortality charges and administrative expenses are capped by the contract for the duration of the chosen term.
In the context of the 2026 financial landscape, this guarantee provides a hedge against inflation and rising healthcare costs. If an individual’s health declines during the term—for instance, if they develop a chronic condition—the "Level" nature of the premium ensures their costs do not skyrocket, provided the policy remains in force.
Decoding the Level Platinum Guarantee
The Level Platinum Guarantee is not merely a marketing term; it is a legal provision within the policy contract. This guarantee ensures that the "scheduled premium" shown in the policy illustrations is the maximum amount the policyholder will ever have to pay during the initial term.
Most modern life insurance policies contain two sets of numbers: the "current" premium and the "maximum guaranteed" premium. In many lower-tier or "non-guaranteed" term products, the insurance company reserves the right to raise premiums up to a certain maximum if their internal costs increase. However, the Level Platinum Guarantee effectively merges these two columns. For the duration of the 10, 15, or 20-year period, the current premium is the guaranteed premium.
This level of certainty is particularly valuable for:
- Young Families: Who need to lock in a fixed expense while managing mortgages and childcare costs.
- Business Owners: Utilizing life insurance for "Key Person" protection or buy-sell agreements where fixed overhead is essential for long-term budgeting.
- Estate Planners: Who require a temporary "bridge" of coverage while a larger estate plan or trust is being funded.
The Strategic Power of the Conversion Privilege
The word "Convertible" in the product name is arguably more significant than the term "Level." A conversion privilege allows the policyholder to exchange their term policy for a permanent policy (such as Whole Life or Universal Life) offered by New York Life at the time of conversion.
As of 2026, the conversion window for the Level Premium Convertible Term typically extends for the duration of the level premium period or until the insured reaches a specific age (often age 70 or 75), whichever comes first. The critical advantage here is the waiver of medical evidence.
If a policyholder buys a 20-year Level Platinum policy at age 30 and is diagnosed with a serious illness at age 45, they can convert that policy to a permanent New York Life Whole Life policy at age 49 without taking a blood test, physical exam, or answering health questions. The premium for the new permanent policy will be based on their age at the time of conversion, but their "health rating" will remain what it was when they were a healthy 30-year-old. This "insurability insurance" is the primary reason why many sophisticated buyers choose New York Life over lower-cost, non-convertible internet providers.
Underwriting Classes and Pricing Tiers
The cost of the Level Premium Convertible Term is determined by New York Life’s underwriting process. Even with the Level Platinum Guarantee, the starting price point depends on which "risk class" the applicant falls into. In 2026, these classes generally include:
- Select Preferred: Reserved for individuals in excellent health with no significant family history of early mortality and a clean driving record.
- Preferred: For those in very good health who might have minor, well-controlled issues like slightly elevated cholesterol.
- Standard Plus: For individuals with average health who are non-smokers.
- Standard: The baseline rate for those with average health and lifestyle risks.
- Smoker Rates: Significantly higher premiums for those who use tobacco or nicotine products.
The Level Platinum Guarantee applies equally to all these classes. Once the policy is issued at a specific rate, that rate is locked for the 10, 15, or 20-year duration, regardless of whether the insured transitions from "Select Preferred" health to a higher risk category later in life.
Comparison of Term Durations and Conversion Limits
Choosing the right duration is vital because the Level Platinum Guarantee expires once the initial term ends. After the level period, the policy typically enters an "annually renewable" phase where premiums increase drastically each year.
| Term Duration | Level Premium Guarantee | Typical Conversion Deadline | Primary Use Case |
|---|---|---|---|
| 10-Year Term | Fixed for 120 months | End of Year 10 (or age limit) | Short-term debt, such as a business start-up loan. |
| 15-Year Term | Fixed for 180 months | End of Year 15 (or age limit) | Mid-range mortgages or protecting children through college. |
| 20-Year Term | Fixed for 240 months | End of Year 20 (or age limit) | Standard family protection and long-term income replacement. |
| Term to Age 90 | Fixed for varying years | Usually age 70 or 75 | Long-term flexibility with an emphasis on permanent transition. |
Note: Specific conversion deadlines are subject to state-specific regulations and the exact policy form issued.
Policy Riders and Enhancements
The New York Life Level Premium Convertible Term can be customized with various "riders"—optional add-ons that provide additional benefits, often at an extra cost. These riders are also protected by the Level Platinum Guarantee’s pricing structure.
Waiver of Premium Rider
If the insured becomes totally disabled (as defined by the policy) and is unable to work, New York Life will pay the premiums for the policy. This ensures that the life insurance remains in force during a period when the insured's income may be severely limited. In 2026, this remains one of the most frequently added options for young professionals.
Living Benefits (Accelerated Death Benefit)
This feature allows the policyholder to access a portion of the death benefit while still alive if they are diagnosed with a terminal illness. While this does not provide "long-term care" in the traditional sense, it provides critical liquidity during end-of-life care.
Spouse and Children’s Riders
These allow for smaller amounts of term coverage to be added for family members under the umbrella of the primary insured’s policy. While convenient, these riders often have limited conversion options compared to the main Level Platinum policy.
Evaluating the Cost-to-Value Ratio in 2026
When evaluating New York Life's Level Platinum offerings, it is important to distinguish between "price" and "value." New York Life is rarely the cheapest option on the market. Independent brokers often point to smaller, "term-only" companies that may offer premiums 10-15% lower.
However, the value of the Level Platinum Guarantee lies in the claims-paying ability of New York Life. As a company with some of the highest possible ratings from agencies like A.M. Best and Standard & Poor’s, the guarantee is backed by a massive surplus and a conservative investment philosophy. In a volatile 2026 economy, the certainty that the company will be there to pay a claim or honor a conversion 20 years into the future is a significant factor for many consumers.
Furthermore, the conversion to New York Life permanent insurance is often considered superior to many competitors because NYL’s whole life products have a long history of paying dividends to policyholders (though dividends are never guaranteed).
Common Mistakes to Avoid
- Waiting Too Long to Convert: Many policyholders wait until the very last year of their 20-year term to consider conversion. By then, their age may make the permanent premium prohibitively expensive. It is often wiser to convert portions of the policy incrementally.
- Assuming "Level" Means "Permanent": A 20-year level term policy ends or becomes extremely expensive in year 21. The Level Platinum Guarantee does not extend indefinitely; it only protects the initial term.
- Underestimating Coverage Needs: Because the Level Platinum Guarantee locks in the rate, it is often better to buy slightly more coverage than needed today to account for future inflation and life changes, rather than trying to add more coverage later at an older age.
The Role of the New York Life Agent
Unlike many modern insurance tech platforms that use "algorithmic underwriting" and "self-service" portals, New York Life continues to rely heavily on its career agency force. To access the Level Premium Convertible Term with the Level Platinum Guarantee, an applicant usually works with an agent who conducts a "Financial Needs Analysis."
This human element is crucial for the conversion aspect of the policy. An agent tracks the conversion deadlines and helps the policyholder navigate the transition from term to permanent insurance as their financial goals evolve from "protection" to "wealth accumulation" or "estate preservation."
Frequently Asked Questions
What happens to my premium after the 10, 15, or 20-year guarantee period ends? Once the initial Level Platinum Guarantee period expires, the policy enters a period of annually increasing premiums. These rates are typically much higher than the initial level premium because they are based on your attained age and the fact that you are no longer being medically underwritten. Most policyholders choose to either convert the policy to permanent coverage or let it lapse at this point.
Can I convert only a portion of my Level Platinum policy? Yes, New York Life generally allows for "partial conversions." For example, if you have a $1,000,000 term policy, you could convert $250,000 to a Whole Life policy to have some permanent protection while keeping the remaining $750,000 as term insurance for the duration of the original guarantee.
Is the "Level Platinum" guarantee available for smokers? Yes, the guarantee is available to all risk classes, including smokers. While the initial premium for a smoker will be significantly higher than for a non-smoker, that higher rate is still "level" and guaranteed not to increase for the duration of the term.
Does New York Life require a medical exam for the Level Premium Convertible Term? In 2026, many policies under a certain dollar threshold may qualify for "accelerated underwriting," which might waive the physical exam (paramed) if your medical records and digital health data are sufficient. However, for larger face amounts or older applicants, a medical exam is usually required to establish the initial rate.
What is the difference between "Level Platinum" and standard term insurance? The "Level Platinum" branding typically signifies that New York Life’s most robust conversion options and highest-tier premium guarantees are included. Some lower-cost "Basic Term" policies may have shorter conversion windows or allow the company to adjust premiums under specific (though rare) contractual conditions.
Strategic Recommendation
If you are seeking a life insurance solution that prioritizes long-term flexibility over the absolute lowest monthly cost, the New York Life Level Premium Convertible Term with the Level Platinum Guarantee is a premier choice. It is best suited for individuals who anticipate a future need for permanent insurance but currently require a high death benefit for a lower cost.
To maximize the value of this policy, you should review your coverage every three years with a financial professional. Focus specifically on your "conversion options" to ensure that you do not miss the window to lock in permanent protection if your health status changes or your financial needs shift toward estate planning and legacy building.
Image Gallery
Select an image to open it in a new tab.
Zara El-Hashem
Sociocultural Dynamics and Academics Writer
