The online broker market in Canada is the primary engine for individual wealth creation, offering millions of Canadians low-barrier access to global equity, bond, and options markets. It matters because it decentralizes financial power, shifts investors away from high-fee mutual funds toward cost-effective ETFs, and provides the essential infrastructure for managing tax-advantaged accounts like the TFSA and FHSA in an increasingly self-directed economy.
The Evolution of the Canadian Investment Landscape
To understand why the online broker market in Canada matters in 2026, one must first look at the historical context of the Canadian financial system. Historically, the "Big Five" banks—RBC, TD, BMO, Scotiabank, and CIBC—dominated the investment landscape. For decades, the average Canadian investor had little choice but to purchase high-fee, actively managed mutual funds through bank-affiliated advisors. These funds often carried Management Expense Ratios (MERs) exceeding 2%, significantly eroding long-term returns.
The rise of online brokerages changed this dynamic entirely. By providing a platform where individuals could execute their own trades, these entities introduced a "do-it-yourself" (DIY) model that prioritized transparency and cost-efficiency. In 2026, this market has matured into a sophisticated ecosystem where traditional bank-owned brokerages compete fiercely with independent "fintech" platforms. This competition is not merely about lower commissions; it is about the democratization of financial tools that were once reserved for institutional investors or high-net-worth individuals.
Democratization of Access and Lowering Financial Barriers
The most significant reason the online broker market matters is the reduction of entry barriers. In the past, opening a brokerage account often required substantial minimum balances, sometimes ranging from $5,000 to $25,000. Today, many Canadian online brokers allow accounts to be opened with $0, enabling young professionals and students to begin investing with as little as a few dollars through fractional share ownership.
The Impact of Zero-Commission Trading
The shift toward zero-commission trading, pioneered by platforms like Wealthsimple and eventually adopted in various forms by competitors, has fundamentally altered investor behavior. When it costs $9.99 to buy a stock, an investor needs a large position to justify the fee. When the commission is zero, an investor can practice "dollar-cost averaging" by purchasing small amounts of an asset every payday. This behavioral shift encourages consistent saving habits and reduces the risk associated with trying to "time the market."
Fractional Shares and Market Participation
By 2026, fractional share trading has become a standard feature across major Canadian platforms. This allows an investor with only $50 to own a piece of a high-priced stock like Berkshire Hathaway or Shopify. This inclusivity matters because it prevents retail investors from being priced out of the highest-performing sectors of the economy, ensuring that wealth growth is not restricted to those who already possess significant capital.
The Role of Tax-Advantaged Accounts
In Canada, the online broker market is inextricably linked to government-sponsored tax-advantaged accounts. The functionality and ease of use of these accounts within a brokerage platform can determine an individual's long-term financial security.
- Tax-Free Savings Account (TFSA): Online brokers make it simple to trade within a TFSA, where all capital gains, dividends, and interest are earned tax-free.
- Registered Retirement Savings Plan (RRSP): These platforms provide the tools for long-term retirement planning, allowing for the tax-deductible contributions that are vital for middle-class Canadians.
- First Home Savings Account (FHSA): As of 2026, the FHSA has become a critical tool for young Canadians aiming to enter the housing market. Online brokers have been at the forefront of providing the most flexible FHSA options, allowing users to invest in a mix of GICs, stocks, and ETFs to grow their down payment faster than a traditional savings account would allow.
The ability to manage these diverse accounts under a single digital roof allows for better asset allocation and a clearer view of one’s total net worth. This integration is why the market is a central pillar of Canadian "financial wellness."
Regulatory Oversight and Investor Security
The Canadian online broker market matters because it operates within one of the most stable and well-regulated financial environments in the world. This stability provides the confidence necessary for retail investors to commit their life savings to digital platforms.
The Canadian Investment Regulatory Organization (CIRO)
The 2023 merger of the Investment Industry Regulatory Organization of Canada (IIROC) and the Mutual Fund Dealers Association of Canada (MFDA) into CIRO created a streamlined regulatory framework. By 2026, CIRO has solidified its role in ensuring that online brokers adhere to strict capital requirements, "know your client" (KYC) rules, and fair pricing standards. This oversight prevents the kind of "wild west" scenarios seen in less regulated global markets.
Canadian Investor Protection Fund (CIPF)
Investor security is further bolstered by the CIPF, which provides coverage if a member firm becomes insolvent. Most reputable online brokers in Canada are members of CIPF, offering coverage of up to $1 million per account category. This insurance is a fundamental reason why the market matters; it provides a safety net that protects the integrity of the national economy against the failure of individual financial institutions.
Technological Innovation and the User Experience
The Canadian market matters as a hub for fintech innovation. In 2026, the competition between "incumbent" bank brokers and "challenger" independent brokers has led to a surge in technological advancement.
- Instant Deposits: The frustration of waiting three to five business days for funds to clear has largely been eliminated. Many platforms now offer instant or same-day deposits, allowing investors to react to market opportunities in real-time.
- AI-Driven Insights: Modern platforms now integrate artificial intelligence to provide personalized risk assessments and portfolio rebalancing suggestions. While the investor remains in control (self-directed), the "intelligence" of the platform helps prevent common emotional mistakes, such as panic selling during a market dip.
- Integrated Research Tools: High-quality research, once the domain of professional analysts, is now embedded in online brokerage apps. This includes real-time Level 2 market data, analyst ratings, and comprehensive financial statements.
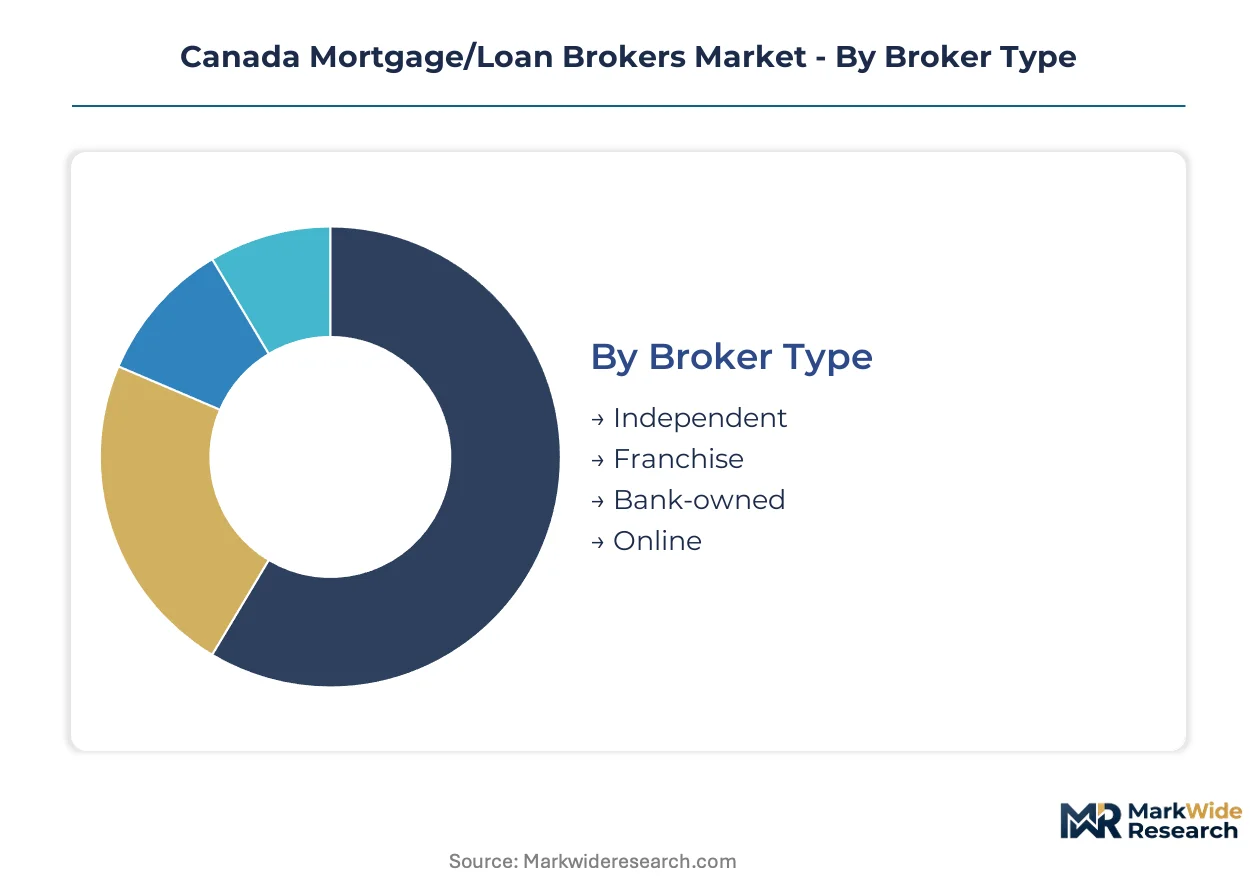
Comparing the Major Segments of the Canadian Market
The following table compares the different types of online brokerage offerings available in Canada as of 2026, highlighting why various segments appeal to different investor needs.
| Broker Category | Primary Examples | Best For | Typical Fee Structure | Key Advantage |
|---|---|---|---|---|
| Bank-Owned | TD Direct Investing, RBC Direct Investing | High-net-worth, All-in-one banking | $7 - $10 per trade; often waived for high balances | Seamless integration with bank accounts |
| Independent / Fintech | Questrade, Wealthsimple | Cost-conscious, DIY investors | Zero-commission or low-cost ECN fees | Innovative UI and low entry barriers |
| Specialized / Professional | Interactive Brokers Canada | Active traders, Options, Margin | Tiered or fixed low-volume pricing | Access to global markets and low margin rates |
The Macroeconomic Significance
Beyond the individual investor, the health of the online broker market in Canada has broader economic implications. A robust brokerage sector ensures that Canadian companies have access to a deep pool of domestic capital. When Canadians invest in domestic stocks through their online accounts, they are providing the liquidity and capital that Canadian businesses need to expand, innovate, and create jobs.
Furthermore, the rise of online brokers has forced the "Big Five" banks to innovate. To prevent a mass exodus of younger clients to fintech challengers, traditional banks have had to improve their digital interfaces and reconsider their fee structures. This ripple effect improves the quality of financial services for all Canadians, regardless of which platform they choose to use.
Common Pitfalls and Challenges
Despite the benefits, the online broker market presents challenges that make its ongoing evolution important. The ease of trading can lead to over-trading or "gamification," where investors treat the stock market like a casino.
The Risk of Gamification
Some platforms use psychological triggers—such as push notifications about "trending stocks" or celebratory animations—to encourage frequent trading. In a healthy market, regulators and brokers must balance "ease of use" with "investor protection." By 2026, there is an increased focus on educational resources within these apps to ensure that users understand the risks of complex instruments like options and leveraged ETFs.
The Complexity of US Dollar Transactions
A unique challenge in the Canadian market is the management of US Dollars (USD). Many Canadians trade US-listed stocks, and the way a broker handles currency conversion can be a hidden cost. Some brokers charge a 1.5% to 2% spread on every conversion, while others allow for USD accounts or "Norbert’s Gambit" (a technique to convert CAD to USD at minimal cost). The market matters because it provides the competitive pressure to make these currency transactions more transparent and affordable.
FAQs About the Canadian Online Broker Market
Is my money safe with a Canadian online broker?
Yes, provided the broker is a member of the Canadian Investment Regulatory Organization (CIRO) and the Canadian Investor Protection Fund (CIPF). CIPF protects your assets up to $1 million if the broker goes bankrupt. However, this does not protect you from market losses; the value of your investments can still go down based on market performance.
How do I choose between a bank-owned broker and an independent one?
Choosing a broker depends on your priorities. If you value having all your finances in one place and don't mind paying slightly higher fees for the convenience of instant transfers from your chequing account, a bank-owned broker like TD or RBC is suitable. If your primary goal is minimizing fees and you prefer a modern, mobile-first interface, independent brokers like Questrade or Wealthsimple are generally better options.
What are "ECN fees" and why do some "free" brokers charge them?
Electronic Communication Network (ECN) fees are tiny charges (often fractions of a cent per share) passed on by the exchange. While some brokers cover these costs, others pass them to the client, particularly for "removing liquidity" from the market. Even on "commission-free" platforms, you may see these small charges on your trade confirmations.
Can I trade international stocks through a Canadian broker?
Most Canadian online brokers provide easy access to North American markets (TSX, NYSE, NASDAQ). However, if you wish to trade on European or Asian exchanges, you will need a more specialized broker like Interactive Brokers Canada. Access to international markets is one of the key differentiators in the 2026 brokerage landscape.
Do online brokers provide tax documents?
Yes. One of the most important functions of a Canadian online broker is the automated generation of tax forms such as T5s, T3s, and RRSP contribution receipts. These are typically made available in the "documents" section of the platform early in the calendar year, making the tax-filing process significantly easier for self-directed investors.
Strategic Recommendation for Investors
The online broker market in Canada is more than just a collection of apps; it is a vital gateway to financial independence. To make the most of this market in 2026, investors should prioritize platforms that offer a balance of low fees, robust security, and access to the specific account types they need (especially the FHSA for those looking to buy a home).
Before committing significant capital, verify that the broker is a member of CIRO and CIPF. For those starting, focus on platforms that offer commission-free ETFs, as this allows for the construction of a diversified portfolio without the drag of high transaction costs. As your portfolio grows, continue to evaluate whether your chosen platform’s tools—such as advanced charting or USD accounts—are keeping pace with your evolving needs as an investor.
Image Gallery
Select an image to open it in a new tab.



Omar Farooq
EdTech Innovation and Virtual Pedagogy Journalist
