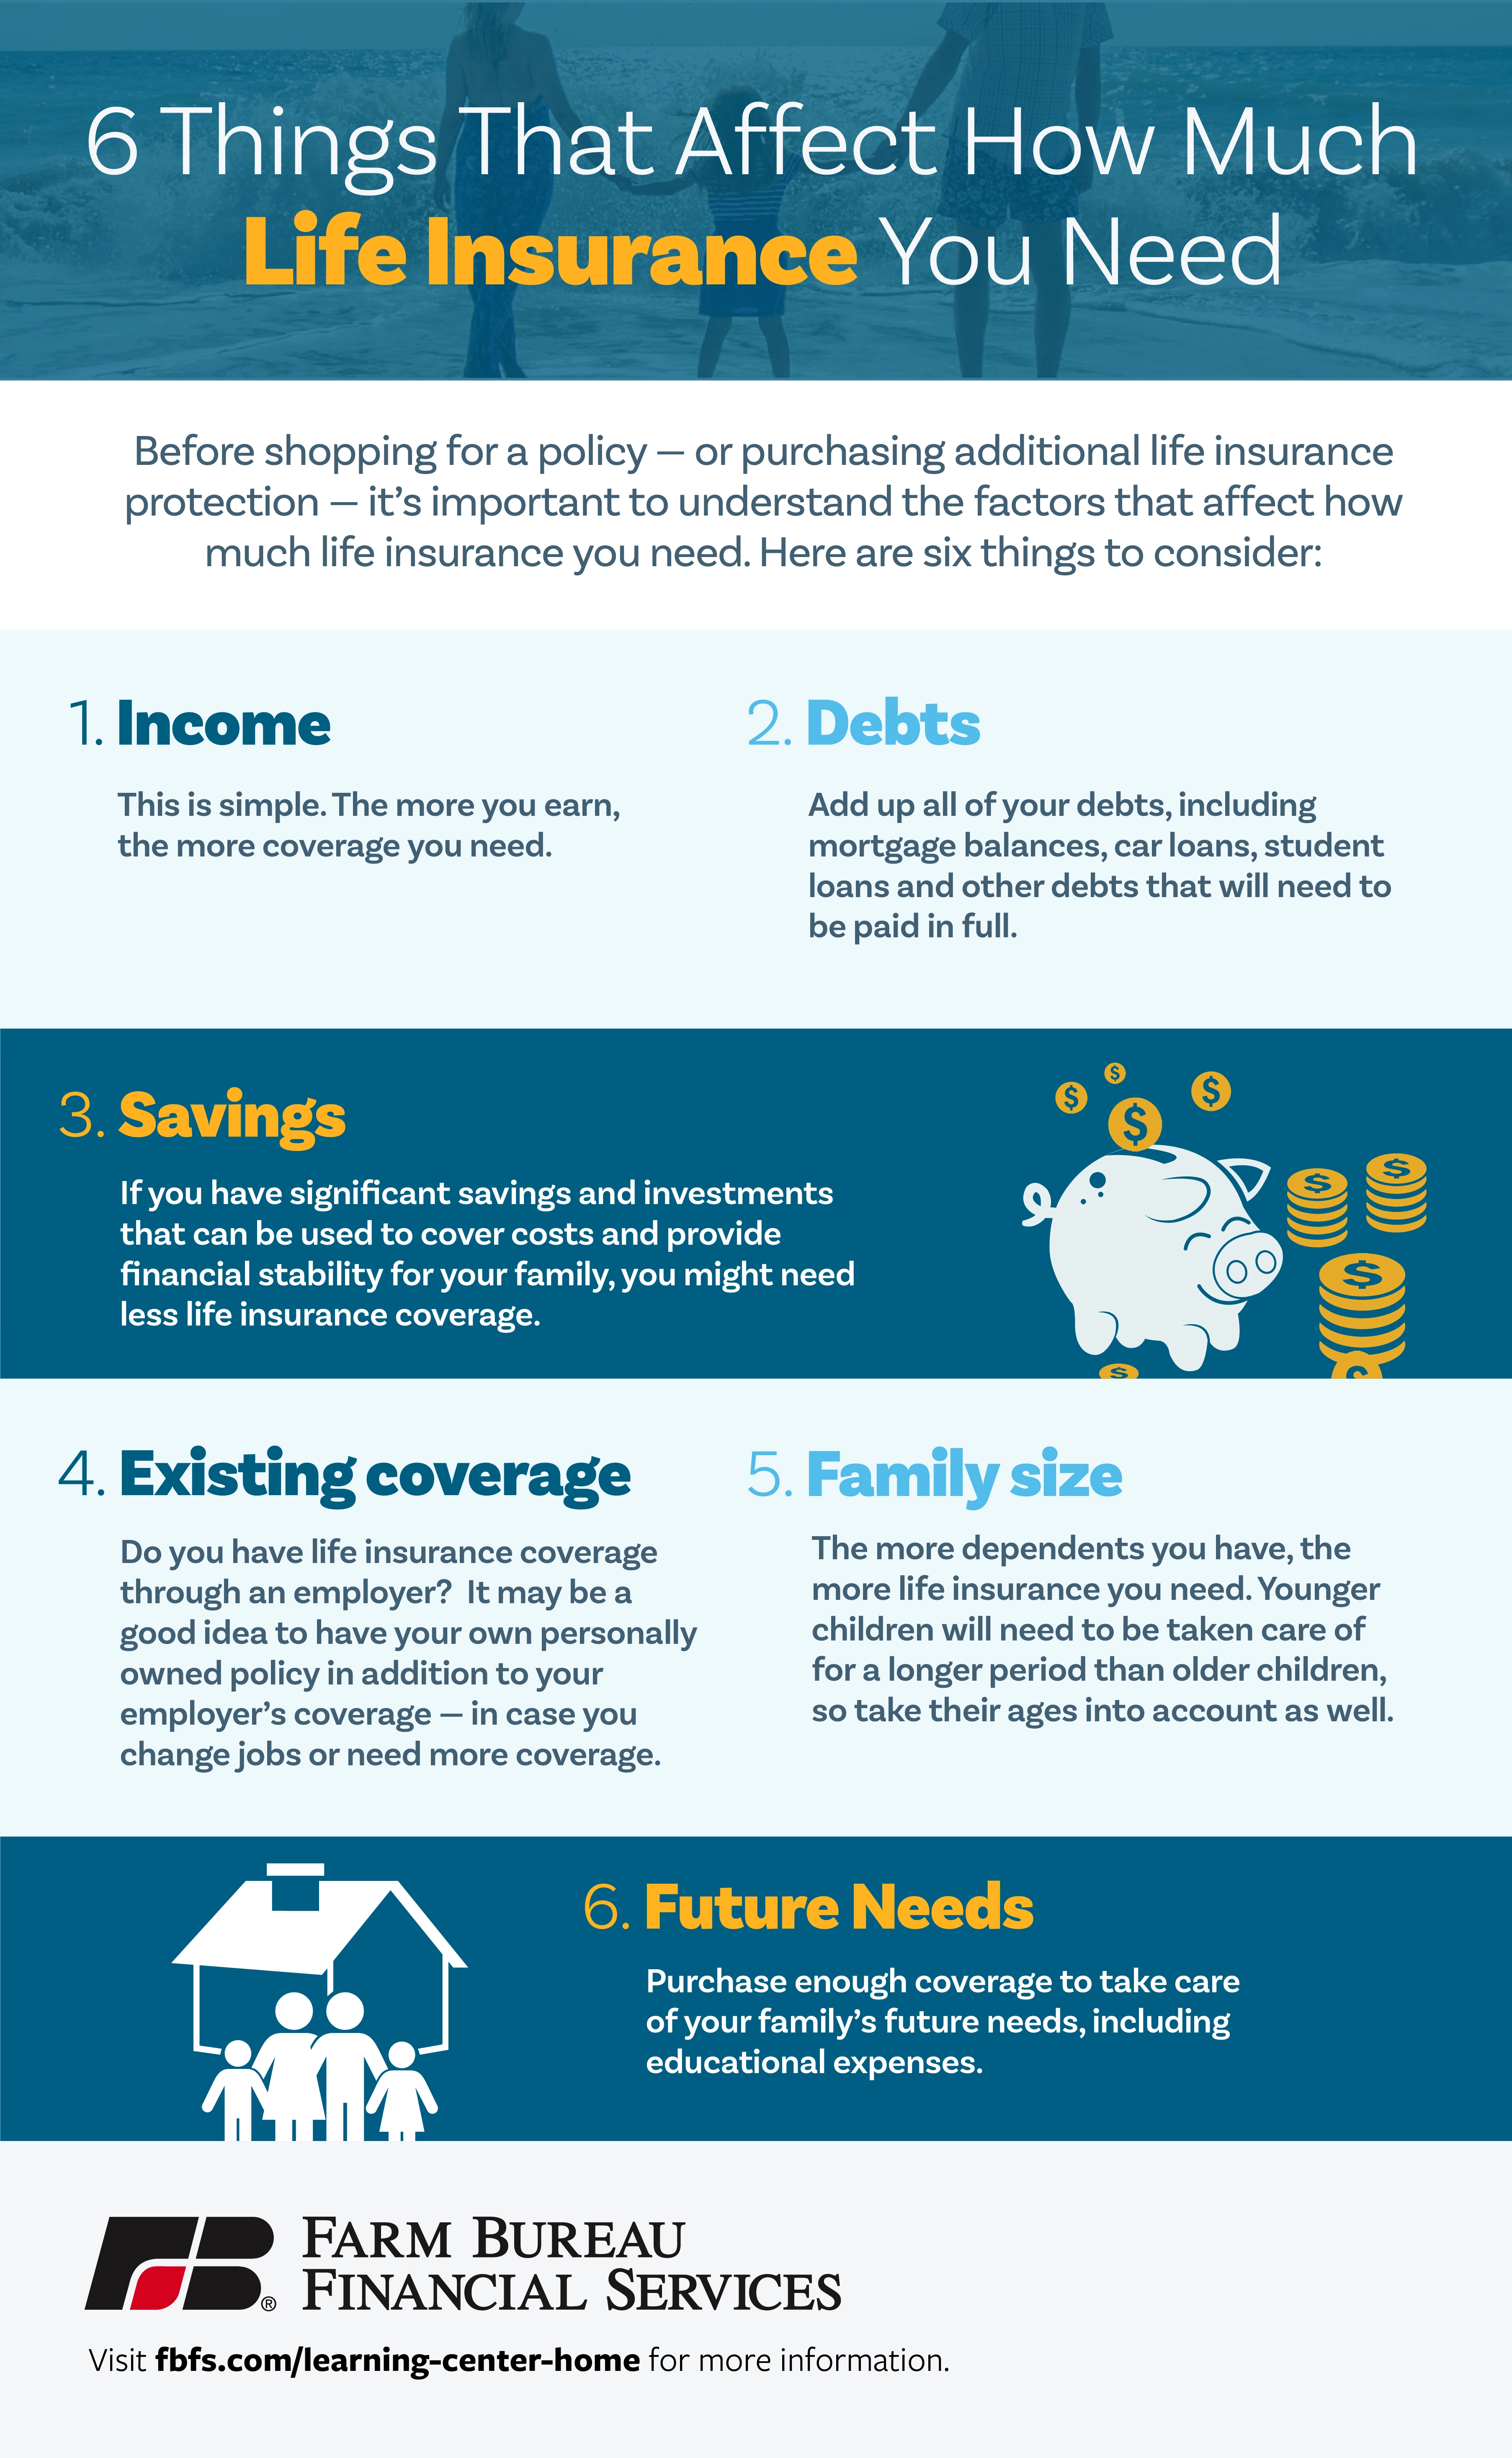
Determining the appropriate death benefit for a whole life insurance policy involves evaluating your long-term financial obligations, existing assets, and the specific role the policy plays in your broader estate plan. Because whole life insurance provides permanent coverage with a cash value component, your needs calculation should balance immediate income replacement, final expenses, and legacy goals.
Understanding the Role of Whole Life Insurance
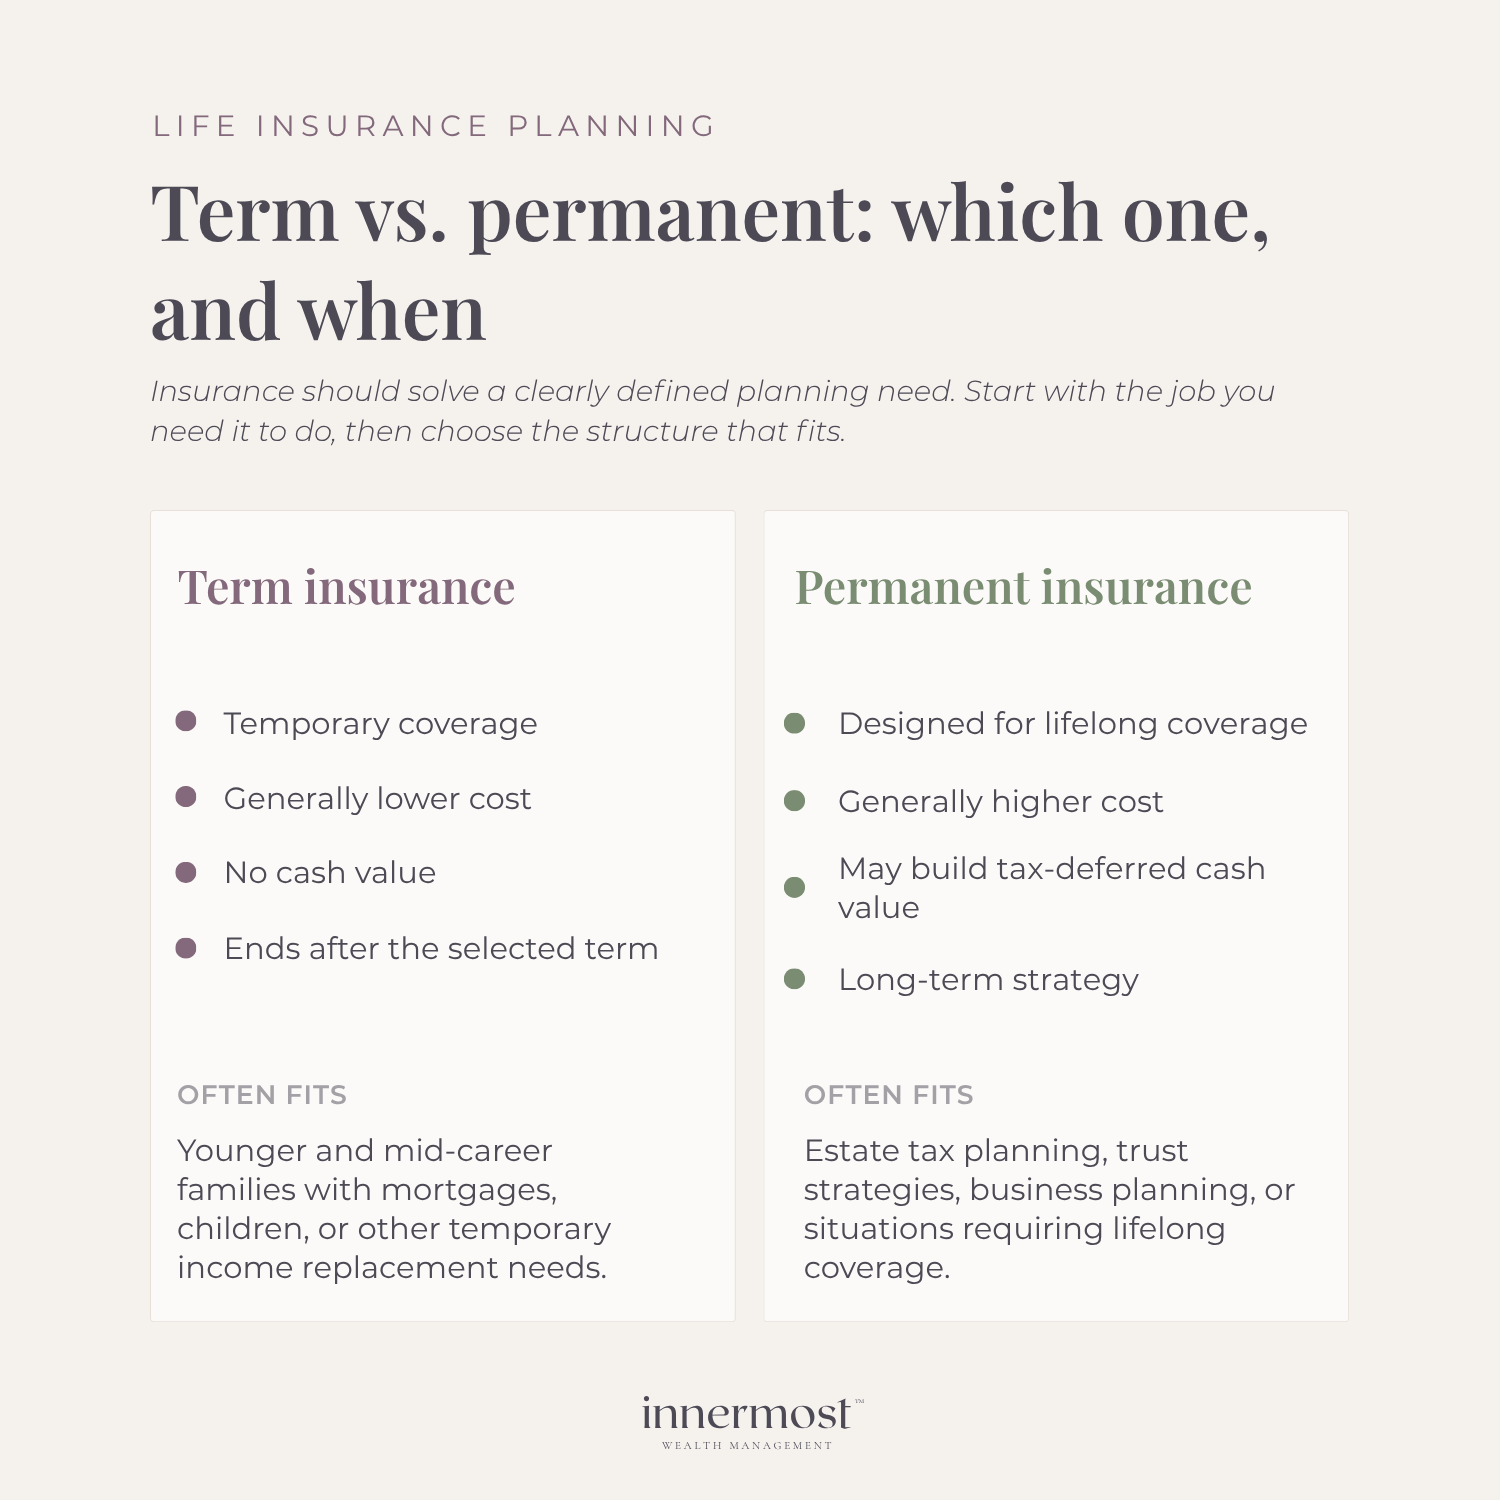
Unlike term life insurance, which is designed to provide high levels of coverage during specific, high-risk periods—such as raising children or paying off a mortgage—whole life insurance is a permanent product. It remains in force for your entire life, provided the premiums are paid, and includes a cash value account that grows on a tax-deferred basis.
When asking "how much," you are essentially answering a different set of questions than you would for term coverage. While term life insurance focuses on the "what if I die tomorrow" scenario for income replacement, whole life insurance often serves as a foundational piece of your financial portfolio. Its purpose may range from providing liquidity for estate taxes and burial costs to acting as a stable, conservative asset class within a diversified wealth management strategy.
The DIME Method Adapted for Permanent Coverage
The DIME method—an acronym for Debt, Income, Mortgage, and Education—is a standard framework for calculating life insurance needs. While usually applied to term insurance, you can adapt it to assess your baseline requirements for whole life insurance.
- Debt: Aggregate all outstanding personal debt beyond your mortgage, including auto loans, personal loans, and credit card balances. These are immediate obligations that your estate must settle.
- Income: Identify how many years your family would require income replacement. If you are using whole life insurance, you might focus on a smaller, permanent income bridge rather than the massive 20- or 30-year projections typical of term insurance.
- Mortgage: Consider the remaining balance of your home loan. If your primary goal is to ensure your family remains in the home regardless of your death, this figure is a non-negotiable part of your coverage need.
- Education: Calculate the projected costs of your children’s or grandchildren’s higher education. Whole life insurance is often used here as a way to "fund" these goals, with the added benefit of the policy’s cash value potentially being accessed to supplement tuition costs.
Beyond Income Replacement: Estate Liquidity and Taxes
For many individuals, the question of how much whole life insurance they need shifts from income replacement to estate preservation as they age. If your assets are substantial, your death could trigger significant tax liabilities or create a liquidity crunch for your heirs.
Federal estate taxes in 2026 apply to assets above the federal exemption threshold. If your estate exceeds these limits, your heirs may be forced to sell off illiquid assets—such as family businesses or real estate—to pay the tax bill. A whole life insurance policy, if structured correctly (often within an Irrevocable Life Insurance Trust or ILIT), can provide the immediate, tax-free cash necessary to settle these obligations, preserving the rest of your legacy intact.
Evaluating Your Capacity to Pay
Whole life insurance is significantly more expensive than term insurance because it is designed to last a lifetime and features a cash value component. A common mistake is overcommitting to a death benefit that results in a premium payment you cannot sustain over the next 20 to 30 years.
Before settling on a face amount, perform a cash-flow analysis. Review your annual income and your fixed expenses. Unlike term insurance, where lapsing a policy often results in simply losing the coverage, letting a whole life policy lapse prematurely can result in significant financial losses. Because the "load" of the insurance policy is front-loaded in the early years to cover agent commissions and administrative costs, the cash value in the first few years is often zero or very low. If you discontinue the policy during this period, you lose the premiums you have paid.
Comparing Coverage Strategies
To determine the right level of coverage, it is helpful to compare the utility of whole life against other options.
| Feature | Whole Life Insurance | Term Life Insurance |
|---|---|---|
| Duration | Permanent (Lifetime) | Temporary (10–30 years) |
| Cash Value | Included (Grows over time) | None |
| Premium | Fixed and higher | Fixed and lower |
| Primary Intent | Estate planning, liquidity, cash value | Income replacement, debt coverage |
| Risk of Lapse | High financial cost if early | Policy ends with no value |
Factoring in Cash Value Growth
The "amount" of insurance you need is not just the face value paid to your beneficiaries; it is also the utility of the cash value you can access while alive. If you are looking at whole life insurance as a tool for wealth accumulation or supplemental retirement income, the death benefit may actually be secondary to the policy's cash accumulation potential.
In this scenario, you should work with a financial planner to conduct a "policy illustration" analysis. This involves examining the projected growth of the cash value based on the dividends (if the policy is with a mutual insurance company) and the interest crediting rates. You may find that you need less death benefit than you initially thought, allowing you to allocate more capital toward paid-up additions or other policy riders that enhance cash value growth.
Common Mistakes to Avoid
- Underestimating Inflation: While your debt might decrease, the cost of final expenses and estate taxes rarely goes down. Ensure your coverage plans for future purchasing power.
- Ignoring Policy Riders: Riders, such as long-term care or accelerated death benefit riders, allow you to access part of your death benefit while alive if you become terminally or chronically ill. These effectively change "how much" you need by providing a financial cushion for medical care.
- Purchasing Based on Peer Comparisons: Your need for insurance is bespoke to your balance sheet. Comparing your coverage amount to a friend or relative is counterproductive because their debt load, tax situation, and legacy goals are different.
- Failing to Review: Life changes—marriages, divorces, the birth of children, and changes in net worth—are all triggers for a review. You should re-evaluate your insurance needs at least every three to five years.
Frequently Asked Questions
How does my current net worth influence the amount of whole life insurance I need? Generally, the higher your net worth, the more you may need whole life insurance for estate tax liquidity. If your assets are primarily illiquid (like real estate or private equity), a death benefit ensures your family has the cash to cover taxes without conducting a "fire sale" of your assets.
Can I have too much whole life insurance? Yes. Because whole life insurance premiums are significantly higher than term premiums, buying more coverage than your budget can support can lead to a policy lapse. You should prioritize "right-sizing" the policy so that the premiums are sustainable for the long term.
Does whole life insurance replace the need for an emergency fund? While you can borrow against the cash value of a whole life policy, it should not be considered a primary emergency fund. Accessing cash value involves policy loans which accrue interest and reduce your death benefit. It is a secondary layer of liquidity, not a replacement for a cash savings account.
Should I consider inflation when calculating my insurance needs? Absolutely. If you plan for a death benefit today based on current dollar values, those dollars will have significantly less purchasing power in 20 or 30 years. When calculating your target, factor in a modest inflation adjustment for final expenses and legacy transfers.
What happens if I cannot afford the premium later in life? Whole life policies often have "non-forfeiture options." These allow you to stop paying premiums and either convert the policy to a smaller, paid-up death benefit or use the existing cash value to keep the policy in force for a shorter period. These options ensure you do not lose all the value you have built if your circumstances change.
Professional Guidance and Next Actions
Determining the exact amount of whole life insurance required is a complex financial decision that sits at the intersection of tax law, family planning, and wealth management. It is strongly recommended to consult with a fee-only financial advisor or a Chartered Life Underwriter (CLU) who does not operate solely on commission.
Before your consultation, create a personal balance sheet listing all your assets, all your liabilities, and your specific goals for your heirs. By providing a clear picture of your financial life, you enable a professional to run accurate projections and help you select a face amount that is both sufficient for your needs and sustainable for your budget.
Image Gallery
Select an image to open it in a new tab.

Simon Caldwell
Enterprise Technology and Systems Editor
