Deciding whether to access the cash value in your life insurance policy is a significant financial maneuver that requires weighing long-term coverage needs against immediate liquidity requirements. When considering options like life settlements—specifically services provided by companies like Abacus Life—it is essential to determine if the surrender or sale of your policy aligns with your broader retirement and estate planning goals.
The Mechanism of Cash Value in Permanent Life Insurance
Permanent life insurance, such as whole life or universal life insurance, is distinct from term insurance because it includes a cash value component. As you pay your premiums, a portion of the payment is directed into a tax-deferred savings or investment vehicle held within the policy. Over time, this cash value grows based on interest rates, dividends, or the performance of underlying sub-accounts, depending on the policy structure.
For many policyholders, this cash value serves as a "living benefit." You can generally access these funds through policy loans or partial surrenders. However, it is critical to understand that taking money out of a policy can have consequences. A loan must be repaid with interest, and if the loan is not paid back, the death benefit—the amount your beneficiaries receive—is reduced. If the loan balance exceeds the cash value, the policy may lapse, potentially resulting in a significant tax liability.
What Is a Life Settlement?
A life settlement is the sale of an existing life insurance policy to a third-party investor for a lump-sum cash payment. The amount received is less than the policy’s total death benefit but is typically significantly higher than the policy’s current cash surrender value.
Once the policy is sold, the investor takes over the payment of future premiums and becomes the beneficiary of the death benefit when the insured individual passes away. Abacus Life is one entity in this industry that facilitates these transactions, functioning as a provider or purchaser that evaluates the policy's suitability for the secondary market.
When Does Engaging with Abacus Life Make Sense?
The decision to sell a policy through a firm like Abacus Life is not universal; it is highly situational. Generally, this route makes sense when the policy is no longer serving its original purpose or has become a financial burden.
1. Premium Affordability Issues
If your financial situation has changed, perhaps due to retirement or reduced income, you may find that the premiums required to keep your policy active are no longer sustainable. If you cannot afford the premiums, your only other option might be to let the policy lapse, which results in losing the coverage entirely with no financial return. In this case, a life settlement provides a recovery of value that would otherwise vanish.
2. Changing Financial Needs
Life insurance is often purchased for specific needs, such as income replacement during child-rearing years, covering a mortgage, or providing liquidity to pay estate taxes. If these needs have disappeared—for instance, if your children are independent, your home is paid off, or your estate is no longer large enough to trigger significant federal estate taxes—the policy may be redundant.
3. Long-Term Care and Medical Expenses
For seniors, the need for cash to cover high-cost medical care or assisted living can outweigh the desire to leave a death benefit. A life settlement provides immediate cash that can be used to improve one's quality of life during retirement, whereas a death benefit only provides value to heirs after the insured’s passing.
4. The "Value Gap"
The most compelling reason to explore a life settlement is when the offer from a company like Abacus Life exceeds the "cash surrender value" offered by your insurance carrier. Insurance companies calculate surrender values based on strict contractual formulas that often do not reflect the true market value of the policy. A secondary market buyer evaluates the policy based on its current market demand and the life expectancy of the insured, which can lead to a more favorable payout.
Comparative Analysis: Cash Value Access Options
To decide on the right path, it is helpful to compare the different ways to extract value from your policy.
| Method | Access Mechanism | Impact on Death Benefit | Financial Result |
|---|---|---|---|
| Policy Loan | Borrowing against cash value | Reduced by unpaid balance | Provides liquidity, remains in force |
| Partial Surrender | Withdrawing cash value | Permanently reduced | Permanent loss of cash value |
| Life Settlement | Selling the policy entirely | Policy terminates | Large lump sum, coverage ends |
| 1035 Exchange | Trading policy for another | Depends on new policy | Maintain coverage, potentially change terms |
Procedural Requirements for Life Settlements
If you conclude that a life settlement is the appropriate path, you must be prepared for the underwriting and verification process. This process is more extensive than simply cashing out a bank account because it involves an assessment of your medical history and the policy’s performance.
- Policy Review: You must provide copies of the policy, including any amendments or riders.
- Medical Underwriting: The firm will review your medical records to estimate life expectancy. This is the primary factor in determining the offer amount. Investors are essentially betting on the duration of the policy before the death benefit is triggered.
- Authorization: You will be required to sign HIPAA releases so that the buyer can verify your health status directly with your medical providers.
- Offer and Negotiation: Once the underwriting is complete, a formal offer is extended. It is often advisable to have an independent broker representing your interests to ensure that you are receiving a competitive valuation.
Potential Drawbacks and Considerations
While a life settlement can be a financial lifeline, it is not without disadvantages:
- Loss of Death Benefit: Once the policy is sold, your beneficiaries will no longer receive the death benefit. This can have profound implications for your estate planning.
- Tax Implications: The proceeds from a life settlement may be subject to capital gains tax. While there are specific tax treatments, the amount received that exceeds your "cost basis" (the premiums paid) is generally taxable.
- Privacy: Selling your policy requires sharing personal medical history with third-party investors.
- Market Limitations: Not every policy is eligible for a settlement. Policies with very small death benefits or policies issued by companies with poor financial ratings may be difficult to sell.
FAQ: Common Questions Regarding Life Insurance Value
What is the difference between a cash surrender value and a life settlement? The cash surrender value is the amount the insurance company is contractually obligated to pay you if you cancel your policy. A life settlement is an offer from an investor who wants to buy your policy; it is often significantly higher than the surrender value because it is based on the policy's potential to pay out a death benefit to the investor.
Can I sell a term life insurance policy? Generally, no. Most life settlement companies only purchase permanent policies (whole or universal life). However, some term policies may be "convertible" into permanent policies, which might then be eligible for a settlement. You would need to check with your insurance carrier regarding your conversion rights.
Does my health status impact the offer from Abacus Life? Yes, significantly. A life settlement is a financial instrument based on life expectancy. If you are in poor health, the investor expects to pay the premiums for a shorter period before collecting the death benefit, which typically leads to a higher offer. If you are in excellent health, the offer will likely be lower.
Is the money I receive from a life settlement tax-free? Not necessarily. Generally, the portion of the proceeds that equals your cost basis (the premiums you paid into the policy) is tax-free. However, any amount received above your cost basis may be subject to income or capital gains tax. Always consult a tax advisor before finalizing a transaction.
Do I need an attorney to sell my life insurance policy? While not always legally required, it is highly recommended to have an attorney or an experienced financial advisor review the settlement contract. These are legally binding documents, and you want to ensure the terms are favorable and clearly understood before you relinquish ownership.
Making the Final Decision
The choice to sell your life insurance policy is a permanent one. Before proceeding with a firm like Abacus Life, perform a thorough audit of your current and future financial obligations. Consider whether the cash liquidity you would gain today provides more utility than the security of a death benefit for your heirs.
If your primary goal is to resolve a cash-flow issue, investigate all alternatives, including reducing the death benefit to lower premiums or taking a policy loan, before settling on a sale. If you do choose the settlement route, ensure you are working with transparent, licensed professionals and that you have fully vetted the offer against the current market value of your specific policy.
Consulting with a fee-only financial planner who has experience in life insurance and estate planning can provide you with an objective analysis of whether a life settlement is truly the most beneficial move for your specific situation.
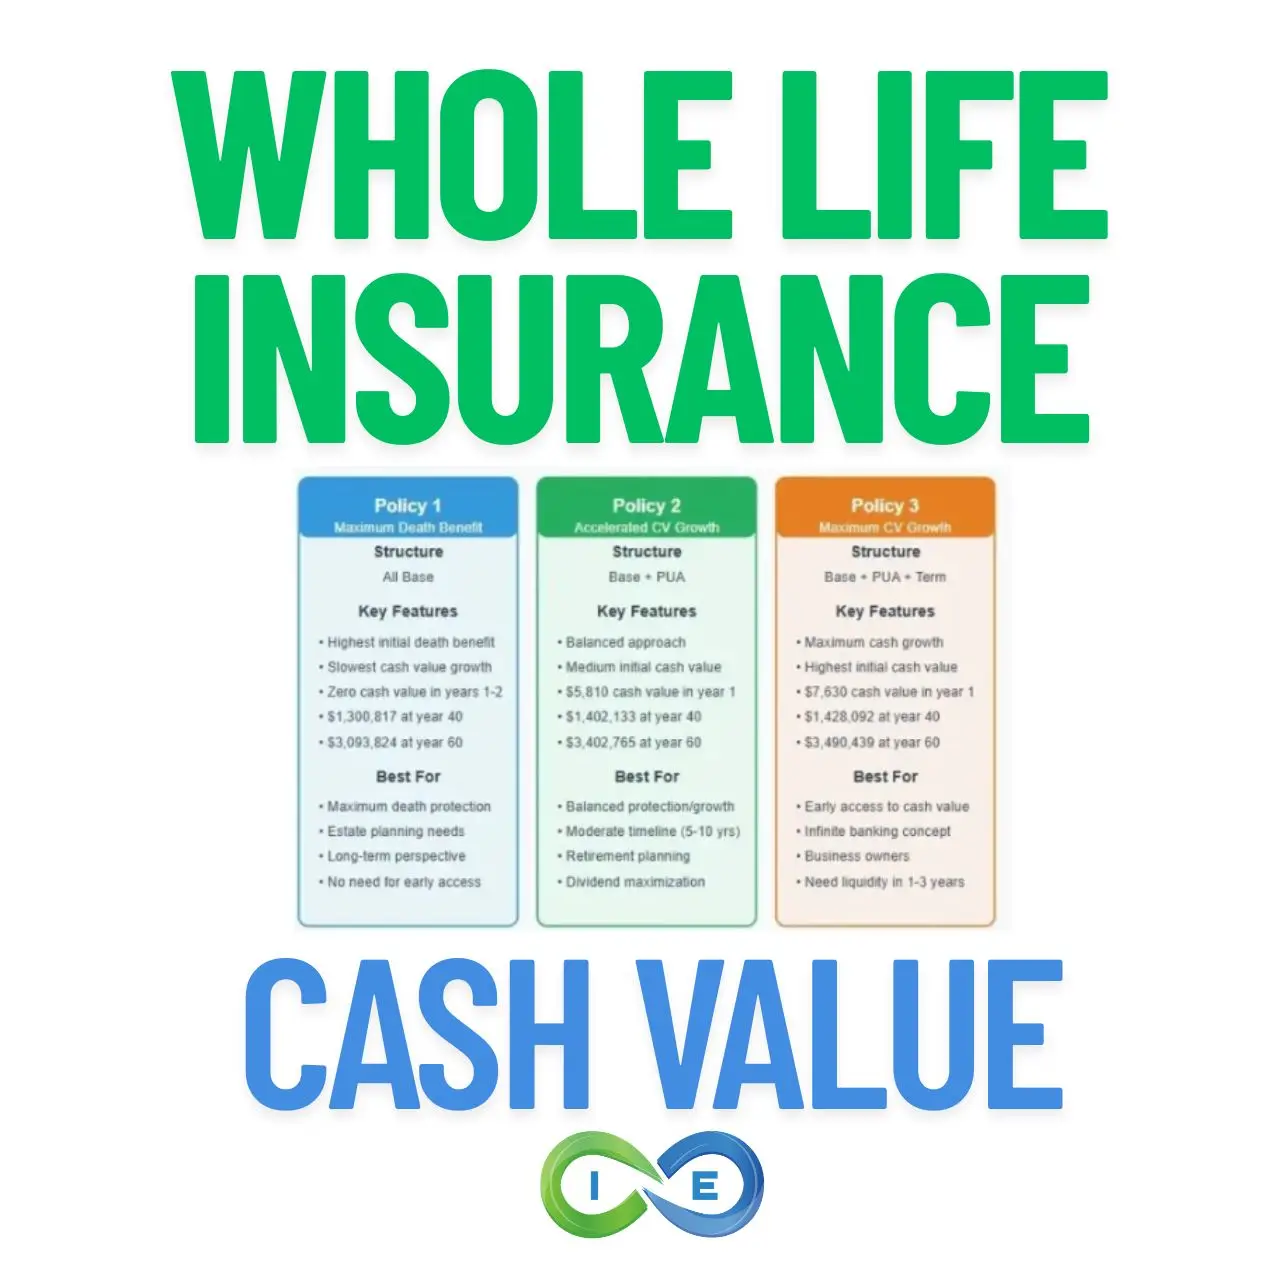
Image Gallery
Select an image to open it in a new tab.



Omar Farooq
EdTech Innovation and Virtual Pedagogy Journalist
