
Securing the best value auto insurance for students requires a strategic combination of leveraging multi-policy discounts, maintaining high academic performance, and choosing appropriate coverage levels that balance affordability with adequate financial protection. By carefully comparing provider-specific student programs and optimizing driver profile variables, students can significantly reduce premiums while ensuring they remain legally and financially covered on the road.
Understanding the Factors Influencing Student Insurance Premiums
Insurance companies operate on the principle of risk assessment, and students—particularly those in the 16 to 24-year-old demographic—are statistically classified as high-risk drivers. Because insurance premiums are a direct reflection of historical data, accidents, and claims, insurers view younger drivers as less experienced. When you seek an auto insurance quote as a student, the algorithm calculates your premium based on several non-negotiable variables.
The most significant factor is your age. Statistically, drivers under the age of 25 are more likely to be involved in traffic accidents. Consequently, insurance carriers adjust their base rates for this group upward to compensate for the increased probability of filing a claim. However, this base rate is only the starting point. Your specific vehicle, your location, and your driving record will then modify this cost.
When requesting a quote, insurers look at the make, model, and year of your vehicle. A high-performance car with expensive parts to replace will inevitably result in a higher premium. Furthermore, urban areas with higher traffic congestion and higher rates of vehicle theft will increase the quote compared to rural or suburban areas. Understanding that these factors are largely set in stone for the duration of a policy term helps you focus your efforts on the variables you can actually control, such as your academic record and your coverage selection.
The Academic Advantage: Good Student Discounts
One of the most effective ways to lower your auto insurance cost is by qualifying for a "Good Student Discount." Many major insurance providers acknowledge that students who maintain high academic standards—usually defined as a GPA of 3.0 or higher, or being in the top 20% of their class—tend to be more responsible, which correlates with safer driving habits.
To claim this discount, you will typically need to provide official documentation, such as a report card or a transcript from your high school or university. It is important to note that this discount is not automatically applied. You must proactively ask your agent or check the policy management portal to ensure your academic achievements are on file. In 2026, many carriers allow for the digital upload of these documents directly into their mobile apps or websites, making the verification process faster than in previous years.
Strategies for Comparing Quotes
To find the best value, you must avoid the "first-quote trap," where a driver selects the first policy they encounter. Comparison shopping is essential. When you request quotes, ensure you are comparing "apples to apples." If one quote includes collision and comprehensive coverage with a $500 deductible, but another quote only covers liability with a $2,000 deductible, the pricing will not be comparable.
| Coverage Feature | Importance for Students | Potential Impact on Quote |
|---|---|---|
| Liability Coverage | Mandatory by law | Required baseline for operation |
| Comprehensive | Protects against theft/vandalism | Increases premium; essential for newer cars |
| Collision | Covers your car in an accident | Increases premium; high value for financed cars |
| Deductible Level | Out-of-pocket cost per claim | Higher deductible = lower monthly premium |
| Telematics Program | Behavior-based monitoring | Potential for significant discounts |
Leveraging Telematics
In 2026, most major insurance providers offer telematics programs—small devices or smartphone apps that monitor your driving habits, such as hard braking, rapid acceleration, and speed. For a student, this is often the fastest route to a lower rate. If you are a safe driver, allowing the insurer to monitor your driving can lead to significant "safe driving" discounts that far outweigh the standard age-based surcharges.
Policy Structures: Staying on a Parent’s Plan vs. Independent Coverage
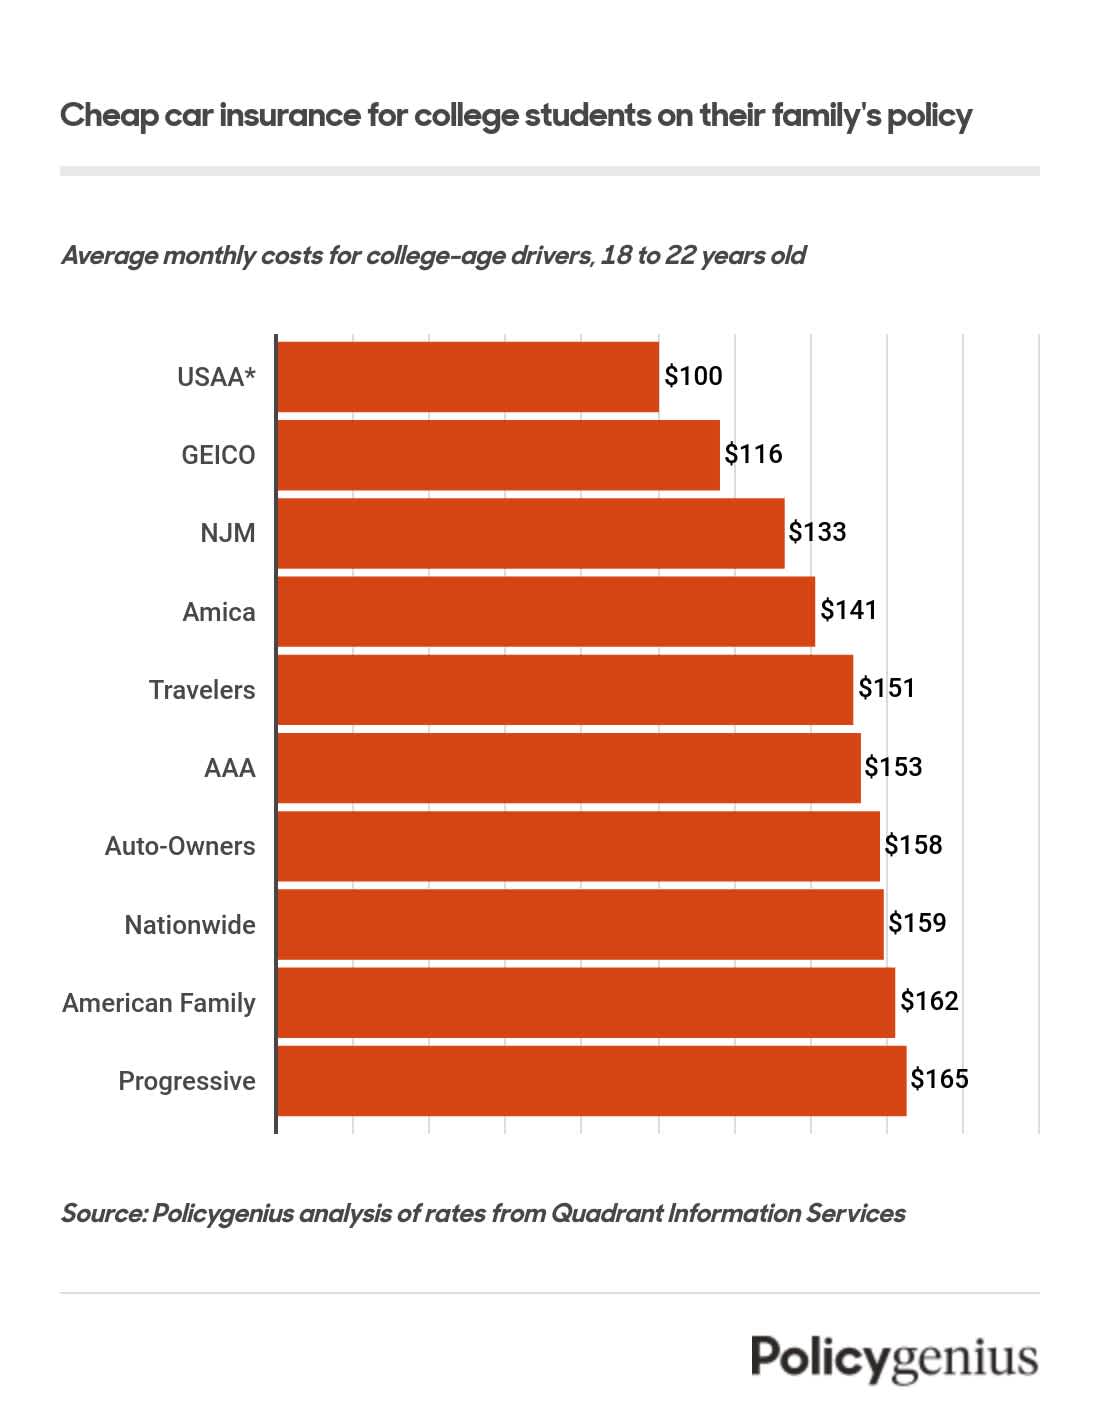
A critical decision for many students is whether to remain on their parents' insurance policy or to obtain an independent one. Staying on a family plan is almost universally cheaper due to "multi-car" and "multi-policy" discounts. Insurers often aggregate the risk across the household, and adding a student driver to a mature, clean-record parental policy is significantly less expensive than insuring a lone student with no prior insurance history.
However, there are circumstances where an independent policy is necessary, such as when a student moves to a different state or resides far from the primary household. If you are moving away for university, check with your insurance provider to see if you can remain on the home policy while attending school. In many cases, if you are a "student away at school" (typically defined as living 100+ miles from home without a car), your premium may be substantially reduced because the vehicle remains at the home address and is used only during school breaks.
Common Mistakes When Buying Student Insurance
One of the most frequent errors students make is failing to update their address or mileage estimates. If you move for school and do not update your policy, you may be left with inadequate coverage or a denied claim in the event of an accident. Conversely, if your policy assumes you are driving 15,000 miles a year, but you actually leave your car at home and only drive during the summer, you are likely overpaying for your insurance.
Another mistake is opting for the absolute minimum coverage requirements. While this provides the cheapest quote, it exposes the student to significant financial risk. If you are involved in an accident where the damages exceed your policy limits, you become personally liable for the difference. Always aim for a "best value" middle ground: coverage that protects your assets without including unnecessary add-ons like premium roadside assistance if you already have an auto club membership.
Preparing for the Quote Process
Before you begin requesting quotes, gather the necessary information to ensure accuracy. Providing inconsistent information—such as an incorrect Vehicle Identification Number (VIN) or inaccurate annual mileage estimates—can lead to quoted prices that change drastically once the insurer runs your actual motor vehicle record.
- Vehicle Details: Have your VIN, current mileage, and recent maintenance history ready.
- Driving Record: Obtain a copy of your motor vehicle report to ensure no past tickets or incidents are overlooked.
- Academic Records: Keep your most recent official transcript or report card ready for verification.
- Existing Insurance: If you have prior insurance, have your declaration page ready to prove continuous coverage, as many insurers offer lower rates to those who avoid a "lapse in coverage."
Frequently Asked Questions
Does my GPA really affect my insurance rate?
Yes. Many insurers offer a specific "Good Student Discount" for those maintaining at least a 3.0 GPA. Because insurance is data-driven, carriers use academic performance as a proxy for personal responsibility and lower risk-taking behavior behind the wheel.
What is the difference between liability and full coverage?
Liability insurance only covers the damage you cause to others or their property. Full coverage includes liability but adds collision (damage to your car from an accident) and comprehensive (damage from theft, fire, or weather). Students with older, lower-value vehicles often opt for liability-only to save money, while those with financed or newer cars are usually required by their lenders to maintain full coverage.
Will my rate drop automatically when I turn 25?
No, the drop is rarely automatic. While 25 is a common milestone for lower risk classification, you should contact your insurance company or agent on your 25th birthday to ensure the new rating has been applied to your account. Do not assume the system will update without prompting.
Should I choose a higher deductible to save money?
A higher deductible lowers your monthly premium because you agree to pay more out-of-pocket if you have an accident. This is a sound financial strategy if you have enough savings to cover that deductible in an emergency. However, avoid setting it so high that you cannot afford the repair if an incident occurs.
How does living away at college change my insurance?
Many companies offer a "student away at school" discount. If you are attending a university more than 100 miles from your home and do not take your car with you, you can notify your insurer. They will classify the car as being stored at the home address, which significantly lowers the risk profile and, consequently, your premium.
Next Steps for the Student Driver
To secure the best value, start by requesting quotes from at least three different major national carriers, as well as one local independent agency that can shop multiple smaller insurers for you. Before finalizing any policy, ensure that you have identified all applicable discounts: good student, defensive driving course completion, and anti-theft device installations.
If you find that standard market rates are consistently too high, inquire specifically about telematics programs. These programs shift the focus from your age and gender to your actual, observable behavior on the road. By demonstrating safe habits, you can bypass the "high-risk" stigma and secure a rate that reflects your specific performance as a driver.
Image Gallery
Select an image to open it in a new tab.
Declan O'Connor
Higher Education and Campus Culture Reporter
