
An auto insurance quote is an estimate of your premium based on the information you provide regarding your vehicle, driving history, and coverage needs. To obtain an accurate quote, you must provide your Vehicle Identification Number (VIN), driver’s license details, and claims history. You can request quotes directly from carriers, through independent agents, or via online comparison tools.
In 2026, the process of obtaining an auto insurance quote has become more data-driven and instantaneous than ever before. While the fundamental concept—exchanging personal data for a price estimate—remains the same, the integration of artificial intelligence and real-time telematics has changed how insurers calculate risk. Understanding where to get a quote from and what information is required is essential for securing the most competitive rate.
The Primary Sources for Auto Insurance Quotes
When looking for an auto insurance quote, you generally have three main avenues. Each source offers distinct advantages depending on whether you value personalized service, speed, or the ability to compare multiple brands simultaneously.
Direct-to-Consumer Carriers
Direct carriers allow you to get a quote from their own proprietary systems, usually via a website or mobile app. Companies like Geico and Progressive popularized this model. The primary benefit is speed; because you are interacting directly with the insurer’s algorithm, you can often receive a finalized quote in under ten minutes. In 2026, these platforms often use pre-fill technology that pulls vehicle data based on your name and address, minimizing manual entry.
Captive Agents
A captive agent works for a single insurance company, such as State Farm or Allstate. When you get a quote from a captive agent, you are benefiting from their deep knowledge of that specific company’s policy language and unique discount structures. While they cannot offer you a price from a competitor, they are often better equipped to handle complex situations, such as bundling high-value assets or navigating specialized coverage endorsements that automated systems might overlook.
Independent Agents and Brokers
Independent agents represent multiple insurance companies. This is often the best route for drivers who have unique risk profiles—such as a history of high-speed violations or ownership of a modified vehicle. An independent agent can shop your profile across dozens of carriers to find the one with the highest risk appetite for your specific situation. They act as a consultative partner, helping you weigh the pros and cons of different insurers.
Online Comparison Platforms and Aggregators
Aggregators are third-party websites that provide quotes from several different companies at once. These tools are excellent for getting a bird’s-eye view of the market. However, it is important to distinguish between "estimated" quotes and "finalized" quotes. Some aggregators provide a ballpark figure based on soft-pull data, while others require a full application to give you a binding price.
Essential Information Required for an Accurate Quote
To get a binding auto insurance quote from any provider, you must be prepared with specific documentation. Inaccurate information during the quoting phase can lead to "rate jumps" later, where the premium increases after the company performs its official underwriting.
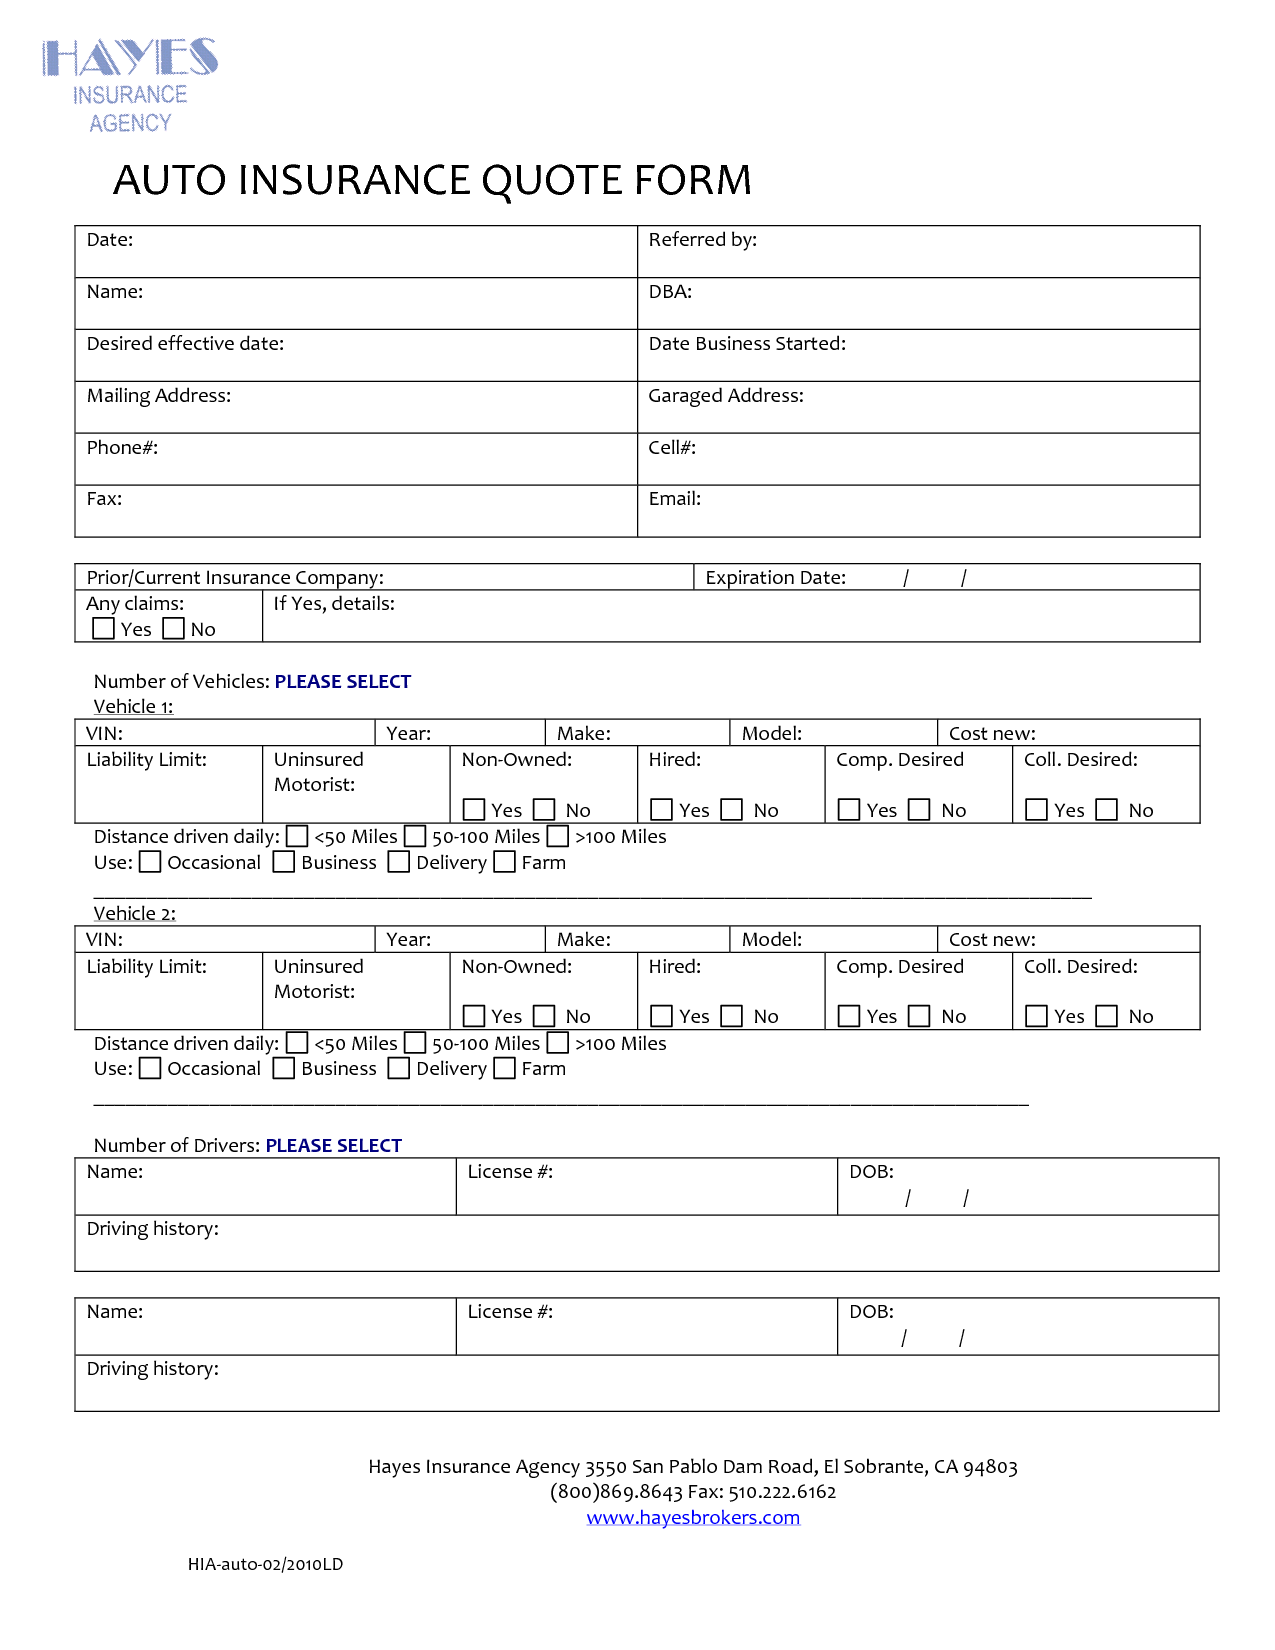
- Personal Identification: You will need the full name, date of birth, and driver’s license number for every person residing in your household who is of driving age. Insurers generally require all household members to be listed or specifically excluded.
- Vehicle Identification Number (VIN): While you can get a rough estimate using the year, make, and model, a VIN is necessary for a precise quote. The VIN informs the insurer about the vehicle’s specific safety features, engine type, and anti-theft devices, all of which impact the rate.
- Garaging Address: Where you park your car at night is a significant rating factor. Urban areas with higher rates of theft or accidents typically command higher premiums than rural locations.
- Driving History: Be prepared to disclose any accidents, moving violations, or claims made within the last three to five years. Most insurers will verify this via a Motor Vehicle Report (MVR) and the Comprehensive Loss Underwriting Exchange (CLUE) report.
- Current Policy Information: If you are switching carriers, having your current "Declarations Page" is helpful. It allows you to match your current coverage limits exactly when comparing prices to ensure an apples-to-apples comparison.
Technical Factors Influencing Your 2026 Quote
The landscape of insurance underwriting in 2026 is heavily influenced by technology and macroeconomic trends. When you receive a quote from a modern insurer, several behind-the-scenes factors are at play.
Telematics and Usage-Based Insurance (UBI)
Most quotes now include an option for telematics. By allowing the insurer to monitor your driving habits—via a mobile app or a device plugged into the car’s OBD-II port—you can often receive an immediate "participation discount." In 2026, many carriers have moved toward "continuous underwriting," where your premium can fluctuate slightly based on real-time data such as hard braking, cornering speed, and time of day spent on the road.
Credit-Based Insurance Scores
In states where it is legally permitted, insurers use a credit-based insurance score to help predict the likelihood of a claim. According to the Federal Trade Commission, there is a statistical correlation between how an individual manages their finances and their likelihood of filing an insurance claim. A higher credit score generally leads to a lower quote, as it suggests a lower risk profile to the underwriter.
Vehicle Complexity and Repair Costs
The "from" in your quote is also heavily dependent on the vehicle itself. In 2026, the prevalence of Advanced Driver Assistance Systems (ADAS) and electric vehicle (EV) batteries has driven up the cost of even minor repairs. A quote for a vehicle with LiDAR sensors and sophisticated camera arrays will reflect the increased liability the insurer takes on in the event of a total or partial loss.
Comparing Coverage Types and Limits
When you receive a quote from an insurer, the price is anchored to specific coverage selections. Understanding these components is critical to ensure you are not just buying the cheapest policy, but the right one.
| Coverage Type | What it Covers | Is it Required? |
|---|---|---|
| Bodily Injury Liability | Injuries you cause to others in an accident. | Yes (Most states) |
| Property Damage Liability | Damage you cause to someone else's property. | Yes (Most states) |
| Collision Coverage | Damage to your own vehicle from a crash. | If vehicle is financed |
| Comprehensive Coverage | Theft, fire, vandalism, or weather damage. | If vehicle is financed |
| Uninsured Motorist | Your injuries if the other driver lacks insurance. | Varies by state |
| Personal Injury Protection | Medical expenses for you and your passengers. | Yes (No-fault states) |
Liability limits are usually expressed as a series of three numbers, such as 100/300/100. This translates to $100,000 in bodily injury coverage per person, $300,000 in bodily injury coverage per accident, and $100,000 in property damage coverage per accident. When obtaining a quote from a new provider, experts often recommend limits of at least 100/300/100 to protect personal assets, even if state minimums are lower.
Strategic Ways to Lower Your Initial Quote
Before finalizing a quote from any carrier, check for available discounts. Many of these are not automatically applied unless you specifically request them or provide the necessary verification.
- Bundling: One of the most effective ways to lower an auto insurance quote is to bundle it with a homeowners, renters, or life insurance policy from the same provider. This often results in a 10% to 25% discount across all policies.
- Safety Feature Discounts: In 2026, insurers give significant weight to autonomous emergency braking, lane-keeping assistance, and sophisticated anti-theft recovery systems like LoJack. Ensure these are accurately reflected in your vehicle's VIN profile.
- Professional and Academic Affiliations: Many carriers offer "affinity discounts" for members of specific organizations, such as alumni associations, military service (USAW, etc.), or professional groups like the American Bar Association.
- Higher Deductibles: If you are looking to lower the monthly premium on your quote, increasing your deductible (the amount you pay out-of-pocket before insurance kicks in) is an effective strategy. However, you should only do this if you have sufficient emergency savings to cover that amount in the event of a claim.
Common Mistakes to Avoid When Getting a Quote
The process of securing an auto insurance quote from a provider is straightforward, but small errors can lead to long-term financial consequences or policy cancellations.
One common mistake is failing to disclose all drivers in the household. Insurers use sophisticated data tools to cross-reference addresses with driver’s license databases. If they discover an unlisted driver after an accident, they may deny the claim or retroactively charge premiums.
Another error is underestimating annual mileage. While it might be tempting to list a low mileage to get a cheaper quote, modern insurers can verify mileage through third-party services like Carfax or telematics data. Providing inaccurate mileage can be flagged as "rate evasion," which is a form of insurance fraud.
Finally, do not assume that the "Standard" or "Basic" package offered by a quoting tool is sufficient. These packages often omit important coverages like Rental Reimbursement or Roadside Assistance, which can be invaluable during a claim. Always review the itemized breakdown of the quote before hitting the "buy" button.
Frequently Asked Questions
Why did my auto insurance quote change after I submitted my application?
Quotes often change between the initial estimate and the final offer because of the "underwriting" phase. During this time, the insurer pulls your official motor vehicle record and claims history. If there are undisclosed tickets or accidents, the algorithm adjusts the risk profile and, consequently, the premium.
Can I get an auto insurance quote from a company without giving my Social Security Number?
While you can often get an "anonymous" estimate, most reputable carriers require a Social Security Number (SSN) to provide a binding quote in states where credit-based insurance scoring is used. This allows them to pull your insurance score, which is a primary rating factor. Some specialty insurers may offer quotes without an SSN, but these often come with significantly higher premiums.
How often should I shop for a new auto insurance quote?
It is a best practice to request a new auto insurance quote from at least three different carriers every 12 to 18 months, or whenever you experience a major life event. Life events such as getting married, buying a home, moving to a new ZIP code, or seeing a significant improvement in your credit score can all lead to substantially lower rates.
Does getting an auto insurance quote affect my credit score?
No. When an insurance company checks your credit to provide a quote, they perform what is known as a "soft inquiry." Unlike a "hard inquiry" used for credit card or mortgage applications, a soft inquiry does not impact your credit score or appear to other lenders. You can shop for as many quotes as you like without damaging your credit health.
What is the difference between a quote and a policy?
A quote is merely an offer or an estimate. It is not a legal contract and does not provide any coverage. A policy is a legal agreement that begins only after you have accepted the quote, signed the application, and made the initial payment (premium). Coverage does not go into effect until the insurer issues a "binder" or the official policy documents.
Practical Recommendation for Your Next Quote
When you are ready to get an auto insurance quote from a new provider, the most effective strategy is the "Rule of Three." Obtain one quote from a direct-to-consumer giant, one from a local captive agent, and one from an independent broker. This triad ensures that you see the full spectrum of the market—from the highly automated, low-cost options to the highly customized, service-oriented plans. Always ensure that the liability limits and deductibles are identical across all three quotes to ensure you are making a valid financial comparison. By leveraging the technological tools available in 2026, such as telematics and pre-fill data, you can complete this entire process in less than an hour, potentially saving hundreds of dollars annually.
Image Gallery
Select an image to open it in a new tab.


Omar Farooq
EdTech Innovation and Virtual Pedagogy Journalist
