Navigating American Express credit cards requires understanding a tiered system that ranges from entry-level cash-back products to ultra-exclusive, invite-only charge cards. This hierarchy is organized by spending requirements, annual fees, reward structures, and lifestyle perks, tailoring specific financial tools to different consumer profiles and business needs.
The credit card industry features a vast array of issuers, but American Express (Amex) occupies a unique space due to its blend of traditional revolving credit cards and historic charge cards. Unlike standard bank cards, Amex portfolios are frequently segmented by tiers that denote status, purchasing power, and concierge-level services. For consumers and business owners alike, mastering these levels is the key to maximizing return on spending, unlocking travel luxuries, and choosing the right financial instrument without incurring unnecessary fees.
To fully grasp the landscape, one must look beyond simple plastic and examine how American Express structures its card families, the functional differences between credit and charge products, and the specific qualifications required to secure higher-tier plastic.
The Core Distinction: Credit Cards vs. Charge Cards
Before evaluating the individual levels of American Express products, it is vital to understand the foundational mechanical difference that sets Amex apart from competitors like Visa and Mastercard: the split between credit cards and charge cards.
Traditional credit cards allow cardholders to carry a balance from month to month, subject to interest charges, governed by a pre-set revolving credit limit. American Express issues many cards of this type, such as the Blue Cash Everyday® or Amex EveryDay® Credit Card. These products function just like standard bank cards, where minimum monthly payments are permitted, and interest accrues if the balance is not paid in full.
Conversely, historical Amex products—most notably the Membership Rewards ecosystem including the American Express® Gold Card and The Platinum Card®—are charge cards. Charge cards require the balance to be paid in full every single month. There is typically no preset spending limit, which does not mean unlimited spending, but rather that the system dynamically evaluates transactions based on factors like payment history, credit record, and financial resources. Understanding this distinction prevents costly mistakes regarding interest accumulation and credit score impacts.
Entry-Level and No-Annual-Fee Tiers
At the foundational level of the American Express ecosystem are entry-level cards, many of which carry no annual fee. These products are designed for individuals building credit history, optimizing everyday household expenses, or seeking straightforward cash-back rewards without complicated travel point transfers.
Everyday Cash-Back Cards
The cash-back tier focuses on direct statement credits for routine spending categories such as groceries, gas stations, and online retail.
- Blue Cash Everyday® Card: Offers structured rewards on U.S. supermarkets, U.S. online retail purchases, and gas stations, making it a staple for domestic budgeting.
- Blue Cash Preferred® Card: Introduces a modest annual fee in exchange for elevated cash-back rates on the same core categories, plus transit and streaming subscriptions, catering to higher-volume household spenders.
Basic Membership Rewards Cards
For those looking to enter the valuable American Express Membership Rewards ecosystem without paying a heavy annual fee, options like the Amex EveryDay® Credit Card provide access to transferable points. Cardholders can earn points on everyday purchases and transfer them to various airline and hotel loyalty partners, provided they meet basic transaction volume thresholds each billing cycle.
Mid-Tier Rewards and Lifestyle Cards
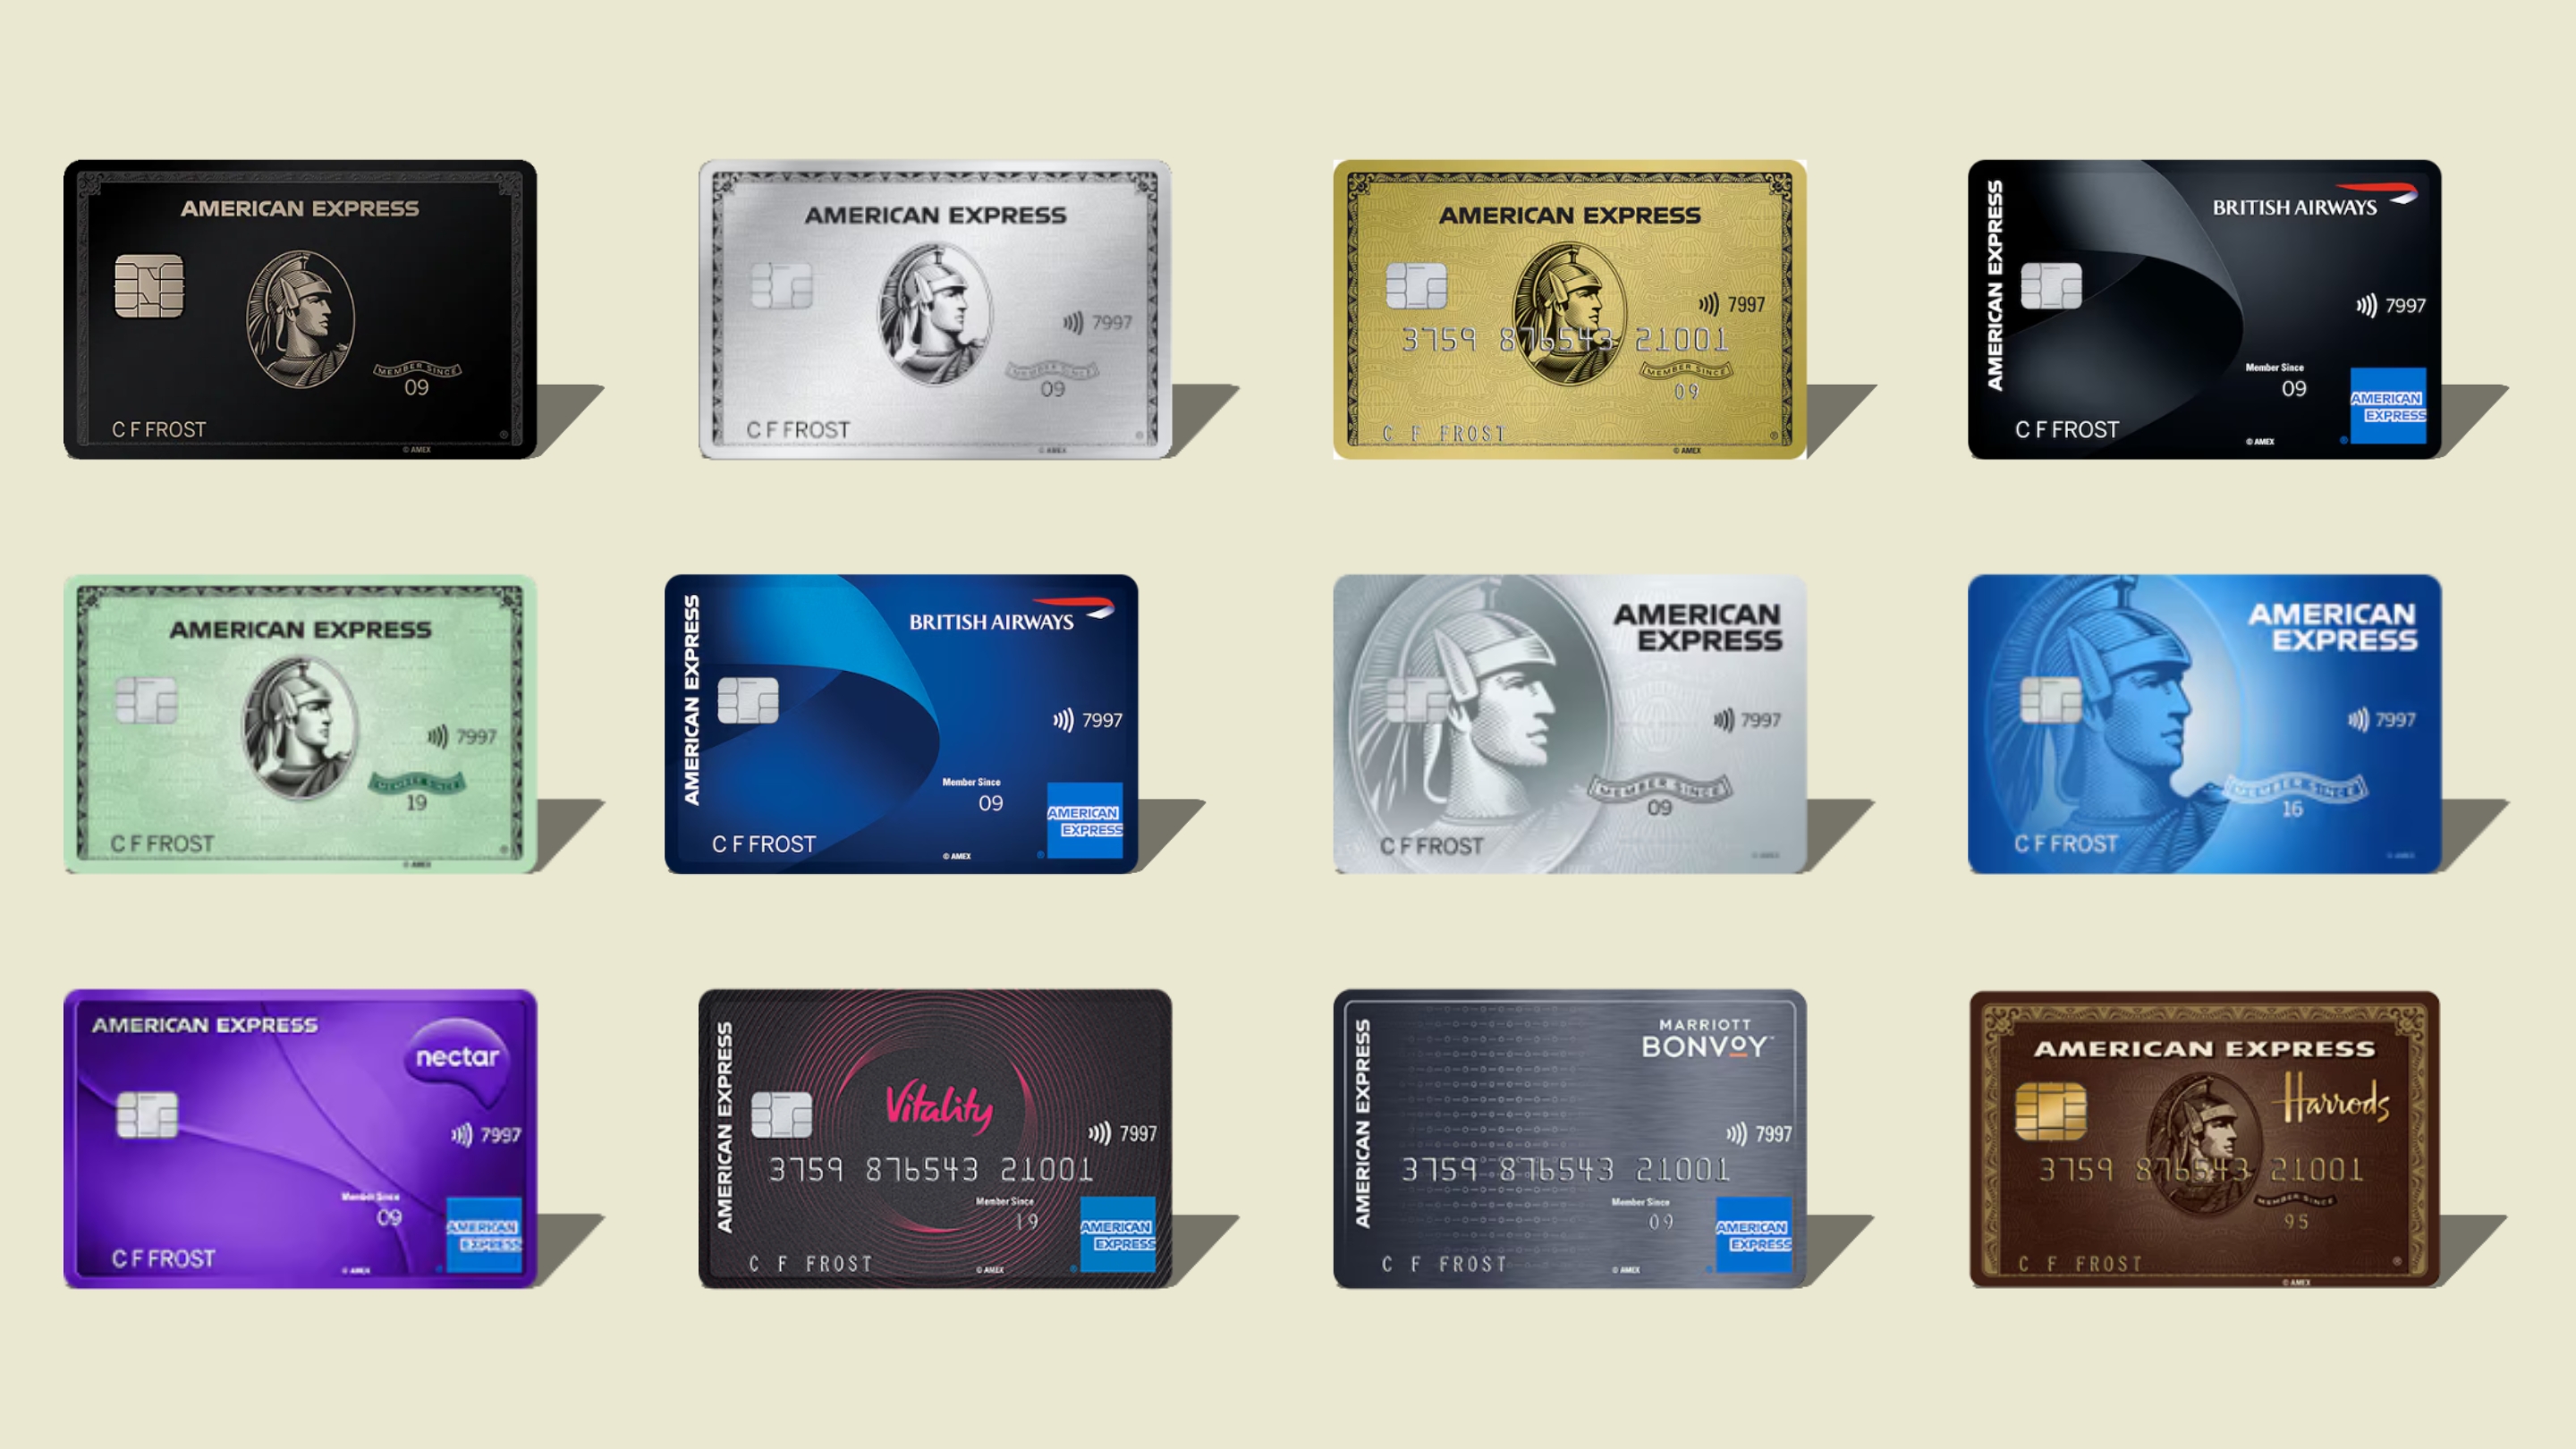
Moving up the ladder brings cardholders into the mid-tier ecosystem, which is dominated by lifestyle, dining, and travel rewards. These cards generally feature substantial annual fees, but they offset those costs with robust credit statements, point multipliers, and specialized insurance protections.
| Card Tier | Typical Annual Fee | Primary Focus |
|---|---|---|
| Entry-Level / No Annual Fee | $0 | Cash-back, basic credit building |
| Mid-Tier Lifestyle / Rewards | $150 - $350 | Dining, supermarkets, travel |
| Premium Travel / Luxury | $600 - $700+ | Airport lounges, elite status |
| Ultra-Exclusive (Centurion) | Initiation + Annual | Invitation-only concierge, status |
The American Express® Gold Card
Occupying a prominent position in the mid-tier space, the Gold Card is engineered for food enthusiasts and frequent travelers. It features high point multipliers on dining worldwide, takeout and delivery in the U.S., and purchases at U.S. supermarkets. Additionally, it offsets its annual fee with annual dining credits and Uber Cash allocations, making it a favorite for urban professionals who dine out frequently.
Mid-Tier Business Solutions
The hierarchy is mirrored in the business sector. The American Express® Business Gold Card, for instance, automatically adapts to a business's highest spending categories each billing cycle—such as advertising, shipping, or computer hardware—maximizing point yields for small-to-medium enterprise owners without requiring manual category selection.
Premium Travel and Luxury Tiers
At the apex of publicly available American Express offerings sit the premium travel and luxury cards. These products are characterized by substantial annual fees, which are marketed toward frequent flyers, luxury travelers, and high-net-worth individuals who can extract value from extensive credit portfolios and airport lounge access networks.
The Platinum Card® from American Express
The Platinum Card is the flagship consumer travel product. While it carries a steep annual fee, it provides access to the Global Lounge Collection—including Centurion Lounges, Priority Pass Select, Delta Sky Clubs (when flying Delta), and Escape Lounges. Furthermore, it bestows automatic elite status with select hotel chains and car rental agencies, alongside a suite of annual statement credits covering digital entertainment, airline incidental fees, global entry or TSA PreCheck application fees, and luxury hotel bookings through Fine Hotels + Resorts.
The Business Platinum Card®
Tailored for corporate spending, the business variant mirrors many of the personal Platinum travel perks while adding heavy multipliers on large business purchases, software subscriptions, and shipping providers, alongside software and airline fee credits designed to reduce overhead for scaling companies.
The Ultra-Exclusive Tier: The Centurion Card
Beyond the public-facing tiers lies the most elite level of the American Express hierarchy: the Centurion® Card, colloquially known as the "Black Card."
The Centurion card is strictly invite-only. Eligibility is not merely a matter of having a high credit score; it requires substantial annual spending (often hundreds of thousands of dollars per year) across existing Amex accounts, combined with significant overall asset levels and a willingness to pay a steep initiation fee alongside a recurring annual membership fee.
Cardholders receive a titanium card, a dedicated personal concierge service, elite status across multiple airlines and hotel chains without needing to meet normal qualification thresholds, and access to exclusive events and private aviation partnerships. Because of its restrictive criteria, it functions as much as a status symbol as it does a financial instrument.
Application Rules, Eligibility, and Credit Requirements
Navigating Amex levels successfully requires understanding the issuer's internal policies regarding approvals, welcome bonuses, and credit limits.
Credit Score and Financial Prerequisites
While entry-level no-fee cards are accessible to applicants with good credit scores (typically 670 and above), mid-tier and premium cards like the Gold and Platinum variants generally require good to excellent credit (700+), stable verified income, and a healthy debt-to-income ratio. American Express evaluates internal data carefully; existing customers with a history of responsible payment behavior often benefit from streamlined application processes.
The "Once in a Lifetime" Welcome Offer Rule
American Express enforces a strict policy stating that individuals are generally eligible to receive the welcome bonus for a specific card only once in their lifetime. If a consumer has previously held The Platinum Card, they cannot open a new one years later and collect a second introductory bonus point allocation. This necessitates strategic planning when deciding which card tier to enter first.
Application Velocity Rules
Amex restricts how quickly consumers can acquire new plastic. Generally, applicants are limited to acquiring no more than two credit cards within a rolling 90-day window, though charge cards operate under slightly more flexible guidelines. Monitoring these velocity rules prevents automatic application rejections.
Choosing the Right Level for Your Financial Profile
Selecting the appropriate American Express card level depends entirely on an objective assessment of annual spending habits, travel frequency, and the ability to utilize complex credit offsets.
- Calculate the True Cost: Always subtract guaranteed statement credits (such as Uber Cash, airline fee credits, or dining stipends) from the stated annual fee to find the net cost of holding a mid-tier or premium card.
- Audit Spending Categories: If the majority of a budget goes toward dining and groceries, a mid-tier lifestyle card yields a higher return than a flat-rate cash-back card. Conversely, infrequent spenders should avoid high annual fees entirely and stick to no-fee tiers.
- Assess Lounge and Travel Needs: Paying for a premium travel card is only mathematically sound if the cardholder regularly uses airport lounges, hotel upgrades, and flight transfer partners.
Frequently Asked Questions
What is the difference between an American Express credit card and a charge card?
Credit cards allow you to carry a balance from month to month subject to interest charges, backed by a fixed revolving credit limit. Charge cards require you to pay your balance in full every month and typically do not feature a preset spending limit, dynamically approving transactions based on your financial history and spending patterns.
Can I upgrade my American Express card from a lower tier to a higher tier?
Yes, cardholders can often request a product change—such as moving from the Blue Cash Everyday to the Blue Cash Preferred, or from the Gold Card to the Platinum Card. However, upgrading typically disqualifies you from earning introductory welcome bonuses associated with the new card, which are usually reserved for brand-new applications.
What credit score is needed to qualify for American Express premium cards?
Premium cards like the Platinum Card generally require a good-to-excellent credit score, typically 700 or higher, along with a stable income and a positive internal history with American Express if you are an existing customer.
How do American Express Membership Rewards points work?
Membership Rewards is the proprietary loyalty currency earned by spending on eligible Amex charge and credit cards. These points can be redeemed for statement credits, gift cards, or bookings through the Amex travel portal, but they deliver maximum value when transferred out to participating airline and hotel frequent-traveler partners.
Are business credit cards separate from personal cards at American Express?
Yes, American Express issues distinct business portfolios. Business cards do not typically appear on personal credit bureau reports unless the account falls severely delinquent, helping keep personal and commercial liabilities separated while still earning business-tailored rewards.
Conclusion and Next Actions
Mastering the American Express credit card levels transforms a potentially overwhelming array of financial products into a strategic portfolio. Whether you are initiating your financial journey with a no-fee cash-back card, optimizing food and travel spend with a mid-tier charge card, or targeting ultra-premium status, aligning your choices with your actual spending behavior is essential. Begin by auditing your past twelve months of expenditures to identify your heaviest spending categories, calculate your true net annual fee tolerances, and select the specific tier that maximizes your purchasing power without adding unwanted debt.
Image Gallery
Select an image to open it in a new tab.


Omar Farooq
EdTech Innovation and Virtual Pedagogy Journalist
