
A small business line of credit works exceptionally well for startups because it provides flexible, revolving access to capital that accommodates unpredictable cash flow, allowing founders to draw funds only when needed and pay interest solely on the amount borrowed.
Launching a new enterprise requires navigating a maze of financial uncertainties. Unlike established corporations with predictable revenue streams and extensive financial histories, startups face volatile cash flows, sudden operational expenses, and delayed accounts receivable. Traditional term loans often fail to meet these dynamic needs because they provide a lump sum upfront, triggering immediate interest accrual on the entire balance regardless of whether the capital is actively deployed. For early-stage companies trying to balance inventory purchases, payroll, and unexpected equipment repairs, a small business line of credit offers a tailored financial safety net.
Understanding the mechanics of this funding instrument, how it compares to alternative financing options, and what criteria financial institutions require can mean the difference between sustainable growth and early financial distress.
Understanding the Small Business Line of Credit
A small business line of credit operates similarly to a credit card rather than a traditional term loan. A lender establishes a maximum credit limit based on the startup's creditworthiness, cash flow projections, and owner financials. The business can draw from this pool of funds up to the approved limit at any time. As the borrowed principal is repaid—along with any accrued interest and fees—the available credit replenishes back to its original limit.
This revolving nature provides unmatched versatility for early-stage companies. When a startup secures a term loan, it receives a single disbursement, incurs interest on the full amount immediately, and must make fixed monthly payments regardless of business cycles. Conversely, a line of credit functions as an on-demand liquidity reservoir. If a startup experiences a slow month, the credit line cushions the cash flow gap. During high-revenue months, the balance can be paid down quickly, minimizing overall borrowing costs.
Revolving Versus Non-Revolving Lines of Credit
When evaluating credit lines, founders typically encounter two distinct structures:
- Revolving Lines of Credit: These function dynamically. As repayments are made, the credit becomes available to borrow again. This structure is ideal for ongoing, cyclical cash flow management and recurring operational expenses.
- Non-Revolving Lines of Credit: These offer a fixed pool of capital that, once drawn and repaid, cannot be drawn again without applying for a new line or a credit limit increase. They behave more like short-term loans with flexible draw periods, making them less suitable for continuous, fluid capital needs.
Why Traditional Term Loans Often Fail Startups
To fully appreciate the utility of a line of credit, it is helpful to examine why traditional term loans frequently frustrate startup founders. Traditional financing assumes a level of operational stability and historical data that most startups simply do not possess.
When a bank issues a term loan, it evaluates historical balance sheets, multi-year tax returns, and consistent profit margins. Startups by definition lack a multi-year track record. Furthermore, taking a lump sum of cash creates immediate financial overhead. If a founder borrows one hundred thousand dollars for anticipated inventory expansion, but supply chain bottlenecks delay delivery for six months, the capital sits idle while interest accumulates daily.
Furthermore, startups frequently struggle to forecast exact capital requirements. Underestimating expenses with a term loan leaves the business short of funds, forcing a difficult secondary borrowing process. Overestimating leads to paying interest on excess capital. A line of credit eliminates this guesswork by letting the business borrow precisely what is needed, down to the dollar and day.

Key Operational Advantages for Early-Stage Companies
Startups require financial instruments that adapt to rapid pivots, seasonal fluctuations, and unexpected hurdles. A line of credit addresses these operational realities through several distinct benefits.
Bridging Cash Flow Gaps
Cash flow timing is one of the leading causes of startup mortality. A business might land a major client, deliver the service or product, and issue an invoice with net-60 payment terms. Meanwhile, rent, software subscriptions, and employee payroll remain due every two weeks. A line of credit bridges this gap instantly, allowing the startup to fulfill current obligations without halting operations while waiting for clients to pay.
Building Business Credit History
Establishing a strong corporate credit profile is essential for securing larger commercial loans, favorable trade credit terms, and lower insurance premiums as the startup scales. Utilizing a business line of credit responsibly—making timely repayments and maintaining a low credit utilization ratio—reports positively to major commercial credit bureaus such as Dun & Bradstreet, Experian Business, and Equifax Business. This lays a solid foundation for future enterprise financing.
Managing Seasonal Volatility
Many startups operate in seasonally sensitive industries, such as retail, tourism, or agricultural tech. Revenues spike during specific quarters and slump during others. Fixed overhead expenses, however, remain constant year-round. A line of credit empowers founders to draw funds during the off-season to cover fixed costs and aggressively pay down the balance when the revenue surge arrives, smoothing out the financial peaks and valleys.
Evaluating Financing Options for Startups
Choosing the right financial product requires a clear comparison of terms, flexibility, and cost structures. The following table contrasts a small business line of credit with other common startup funding sources.
| Feature | Small Business Line of Credit | Term Loan | Business Credit Card | Invoice Factoring |
|---|---|---|---|---|
| Access to Capital | On-demand draws up to limit | Lump sum upfront | Revolving credit limit | Advance against unpaid invoices |
| Interest Accrual | Only on drawn funds | On the entire principal immediately | On unpaid monthly balances | Factor fees / discount rates |
| Repayment Structure | Flexible, minimum monthly payments | Fixed monthly installments | Minimum or full balance monthly | Collected when customer pays invoice |
| Best Used For | Cash flow gaps, inventory, payroll | Large equipment, real estate, acquisitions | Travel, software, office supplies | Immediate cash flow from slow-paying clients |
| Collateral Requirement | Unsecured or secured (assets/receivables) | Typically secured by hard assets | Usually unsecured (personal guarantee) | The unpaid invoices themselves |
Navigating Qualification Requirements and Costs
While lines of credit offer superior flexibility, qualifying for them as a startup requires careful preparation. Lenders perceive early-stage ventures as high risk, meaning underwriting standards can be rigorous.
What Lenders Look For
Because startups lack extensive historical revenue, lenders evaluate alternative indicators of financial health and creditworthiness:
- Personal Credit Score: For newer businesses, lenders rely heavily on the founder's personal credit score. A score of 680 or higher is typically expected for traditional bank products, though alternative online lenders may accept lower scores with higher interest rates.
- Time in Business: Traditional banks often require at least two years of operating history. However, specialized fintech lenders and specific programs, such as certain U.S. Small Business Administration (SBA) microloans or lines of credit, work with businesses operating for six months to a year.
- Business Cash Flow: Lenders examine bank statements to verify steady incoming revenue. Showing consistent deposits, even if modest, demonstrates the ability to service debt.
- Collateral and Guarantees: Many credit lines require a personal guarantee, meaning the founder's personal assets are legally tied to the debt. Some lines are secured by business assets, such as accounts receivable or equipment inventory.
Understanding the True Cost of Borrowing
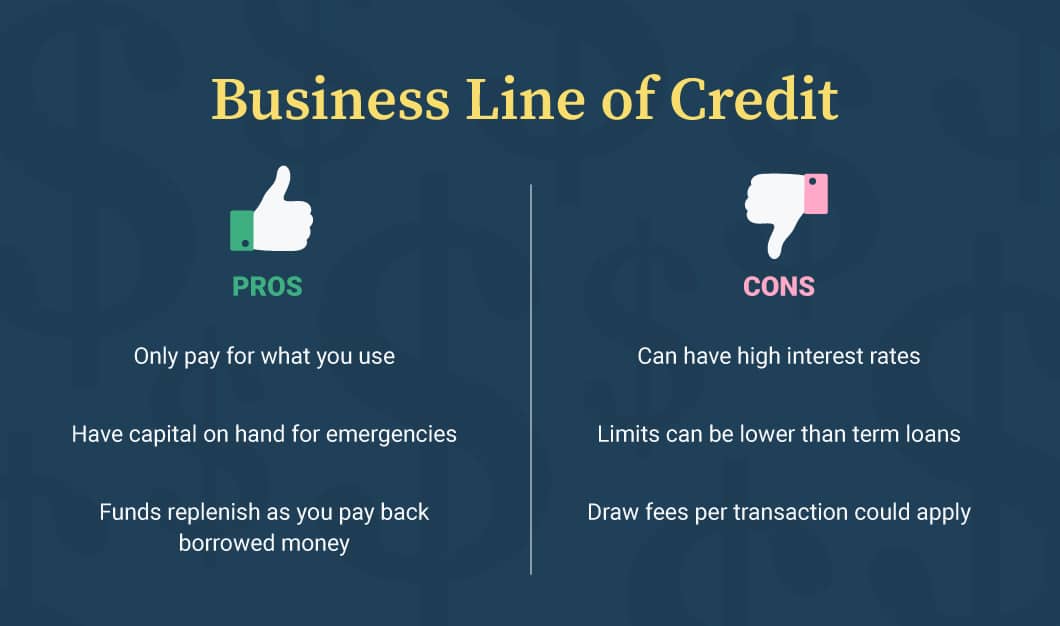
Interest rates on a line of credit can be variable or fixed. Variable rates fluctuate with the prime rate, meaning monthly carrying costs can rise during periods of macroeconomic tightening. Additionally, businesses should watch out for hidden fees:
- Draw Fees: A flat fee or percentage charged each time funds are withdrawn from the line.
- Maintenance or Annual Fees: A recurring fee charged by the lender to keep the credit line open, regardless of whether it is used.
- Origination Fees: An upfront fee charged when the credit line is established.
Reviewing the annual percentage rate (APR) alongside fee schedules ensures that the convenience of a line of credit does not become a financial drag on profit margins.
Common Missteps and How to Avoid Them
Even with an approved line of credit, inexperienced founders can run into structural pitfalls that threaten company stability.
Treating a credit line as free or permanent money is a primary hazard. Because the credit replenishes upon repayment, it is easy to fall into the trap of using revolving debt to fund ongoing operational losses rather than short-term cash flow smoothing. If a startup is consistently losing money month after month, drawing on a credit line only accelerates debt accumulation, culminating in a severe financial crisis when the credit limit is finally exhausted.
Another frequent error is failing to read the fine print regarding penalty rates and default triggers. A missed payment or a sudden drop in the business bank account balance can prompt a lender to freeze the line of credit entirely. Since lines of credit can often be reviewed and revoked annually by the lender, maintaining transparent financial reporting and proactive communication is essential.
Frequently Asked Questions
Can a startup with zero revenue qualify for a business line of credit?
Securing a line of credit with zero revenue from a traditional bank is exceedingly difficult. Most lenders require proof of consistent monthly cash flow to ensure the business can handle repayments. However, some online lenders and fintech platforms evaluate founders based on personal credit scores, liquid assets, and business plans, though these options typically carry higher interest rates and lower initial limits.
Is a business line of credit better than a business credit card?
Both offer revolving credit, but they serve different purposes. Business credit cards are generally better for small, recurring everyday expenses like software subscriptions, office supplies, and travel, often accompanied by reward points. A business line of credit is designed for larger cash injections, such as bridging a 60-day invoice payment gap or purchasing bulk inventory, and usually features lower interest rates and higher borrowing limits.
What is the difference between a secured and unsecured line of credit?
An unsecured line of credit does not require physical collateral, meaning the lender cannot automatically seize business assets if you default, though they can sue or collect through legal means. These are harder to qualify for and require strong credit. A secured line of credit requires collateral—such as equipment, real estate, or accounts receivable—which reduces risk for the lender, often resulting in higher credit limits and lower interest rates.
How quickly can a startup access funds from an approved credit line?
The speed of access depends heavily on the type of financial institution. Traditional commercial banks may take anywhere from a few days to several weeks to disburse funds or make a credit line active. Modern online lenders and fintech platforms often feature streamlined digital applications, allowing approved borrowers to draw funds directly into their business bank accounts within 24 to 48 hours.
Strategic Next Actions for Startup Founders
If your startup faces cash flow timing challenges or requires agile capital to capture growth opportunities, evaluating a business line of credit is a prudent next step. Begin by pulling your personal and business credit reports to identify and correct any errors. Review your recent bank statements to calculate your average monthly cash flow and determine precisely how much capital you need to smooth out operational bumps. Research multiple lending institutions—comparing regional banks, credit unions, and reputable online fintech lenders—to find a product that aligns with your growth stage, offers transparent fee structures, and supports your long-term business objectives.
Image Gallery
Select an image to open it in a new tab.





Zara El-Hashem
Sociocultural Dynamics and Academics Writer
