Navigating Life Insurance in Ocoee, Florida: Coverage Options, Local Factors, and Selection Strategies
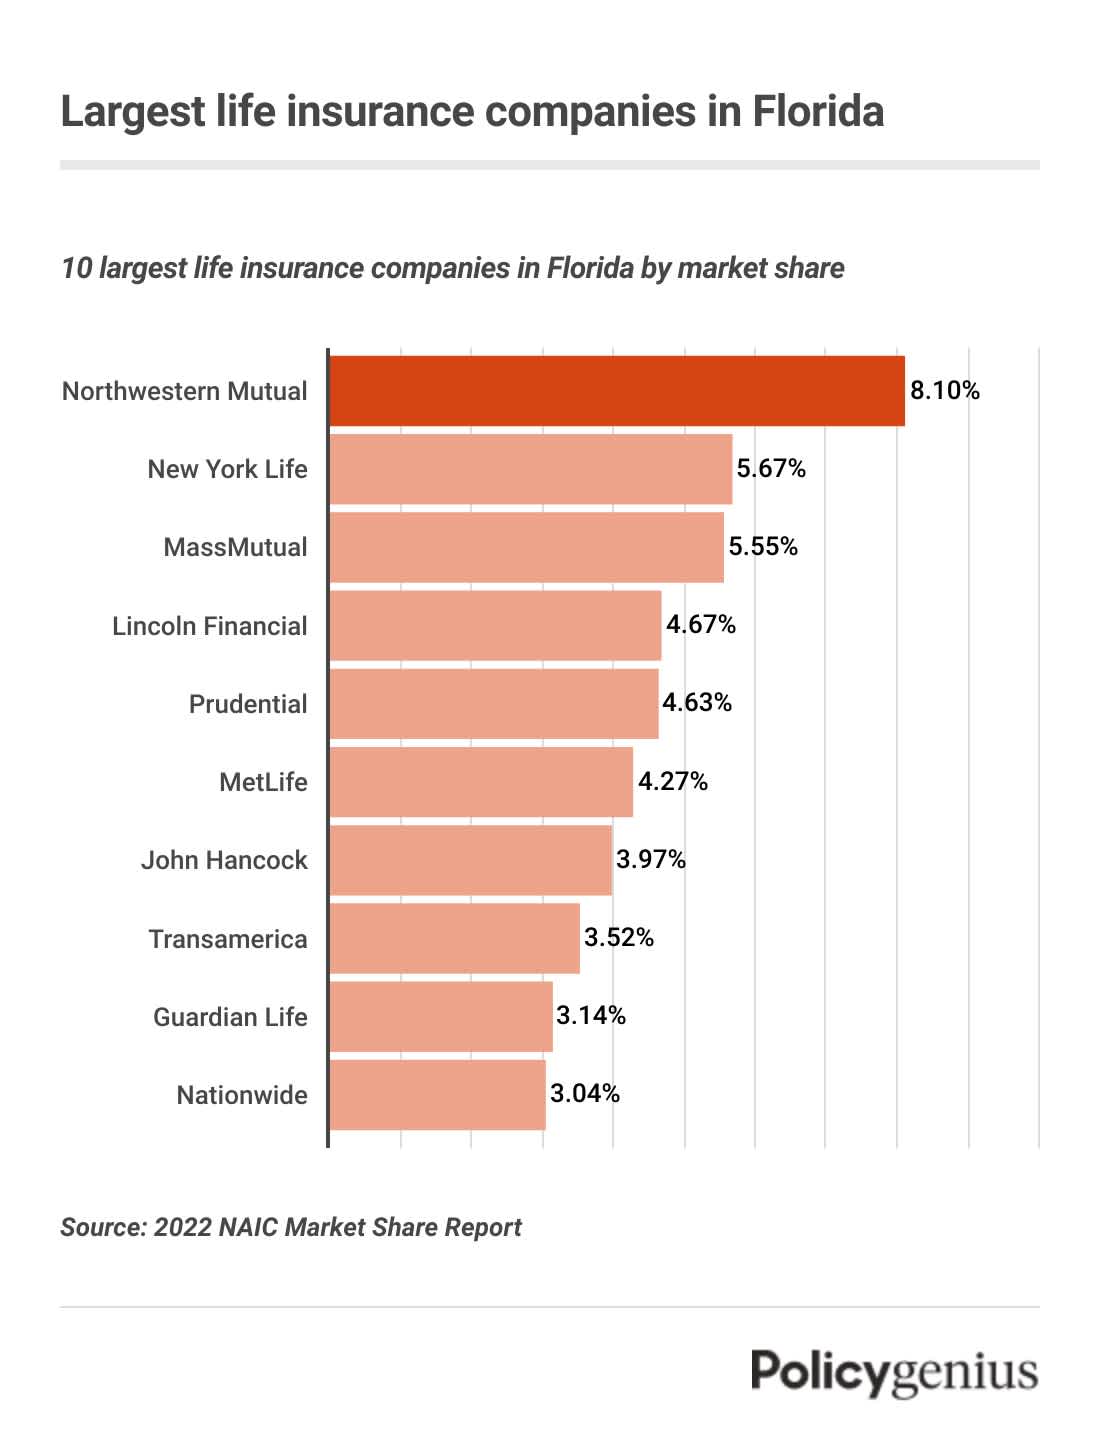
Securing life insurance in Ocoee, Florida, involves balancing standard state insurance regulations with local economic factors, health profiles, and personal financial goals. Residents of this growing Orange County city can choose from term, whole, and universal life policies, all governed by Florida Department of Financial Services regulations and backed by a mandatory 30-day grace period for premium payments. Choosing the right coverage requires evaluating your income replacement needs, family obligations, and whether local cost-of-living factors influence your long-term budget.
Evaluating life insurance policies requires looking beyond national averages to understand how local cost structures, state regulations, and medical underwriting intersect. Whether you reside near the bustling West Oaks Mall or closer to the quiet shores of Lake Apopka, your policy options, premium calculations, and legal protections are shaped by a combination of Florida state law and your individual profile.
Understanding the Florida Life Insurance Regulatory Environment
Life insurance in Ocoee is fundamentally governed by the Florida Insurance Code, overseen by the Florida Office of Insurance Regulation (OIR) and the Department of Financial Services (DFS). These regulatory bodies enforce consumer protection laws that apply uniformly across Orange County and the rest of the state.
Key Consumer Protections Under Florida Law
- The Free-Look Period: Florida law mandates a minimum 14-day free-look period for life insurance contracts. During this window, policyholders can examine the contract, cancel it for any reason, and receive a 100% refund of all premiums paid.
- Grace Period Provision: Insurers must provide a minimum 30-day grace period for premium payments after the due date. The policy remains in active force during this window, ensuring that a delayed payment does not instantly result in a lapse of coverage.
- Incontestability Period: Under Florida Statute § 627.455, life insurance policies generally become incontestable after they have been in force during the insured's lifetime for two years from the date of issue. This prevents insurers from denying death claims based on misstatements in the initial application, except in cases of proven fraud.
- Guaranty Association Protection: The Florida Life and Health Insurance Guaranty Association (FLHIGA) provides a safety net for policyholders if an authorized insurance company becomes insolvent. FLHIGA protects life insurance death benefits up to $300,000 and net cash surrender values up to $100,000, subject to statutory limits.
Primary Types of Life Insurance Policies Available in Ocoee
Insurance carriers operating in Ocoee offer a spectrum of products designed to address temporary debts, long-term income replacement, estate planning, and cash-value accumulation.
Term Life Insurance
Term life insurance provides pure death-benefit protection for a specified period—typically 10, 20, or 30 years. It is generally the most affordable coverage option, making it well-suited for young families in Ocoee seeking to cover a mortgage, replace lost income during peak earning years, or fund children's college education.
- Key Characteristic: No cash value component. If the insured outlives the term, the policy expires unless it includes a conversion rider.
- Conversion Feature: Many term policies allow policyholders to convert all or part of their term coverage into a permanent policy without undergoing a new medical exam.
Whole Life Insurance
Whole life insurance is a form of permanent coverage that remains active for the entire life of the insured, provided premiums are paid. It features guaranteed level premiums, a guaranteed death benefit, and a cash-value account that grows at a fixed interest rate set by the insurer.
- Key Characteristic: Predictability and forced savings. A portion of each premium payment builds tax-deferred cash value against which the policyholder can borrow.
- Suitability: Best for individuals seeking lifelong coverage, final expense funding, or a conservative asset accumulation vehicle.
Universal Life Insurance
Universal life (UL) is another permanent insurance option, but it offers greater flexibility than whole life. Policyholders can often adjust their premium payments and death benefits within specified contract limits, depending on changing financial circumstances.
- Key Characteristic: Unbundled pricing, allowing the policyholder to see how much of their premium goes toward the cost of insurance versus cash-value growth.
- Variations: Indexed universal life (IUL) ties cash-value crediting to the performance of an external market index, such as the S&P 500, offering caps and floors to limit downside risk while participating in market gains.

Comparison of Life Insurance Structures
| Feature | Term Life Insurance | Whole Life Insurance | Universal Life Insurance |
|---|---|---|---|
| Duration | Specific term (10–30 years) | Lifelong | Lifelong |
| Cash Value | None | Guaranteed fixed growth | Variable based on interest/index |
| Premium Costs | Lowest initial cost; rises if renewed | Highest initial cost; fixed for life | Flexible; adjustable within limits |
| Primary Use | Income replacement, mortgage protection | Estate planning, lifelong security | Flexible permanent coverage, cash growth |
| Medical Underwriting | Required (Exam usually required) | Required (Can be simplified for final expense) | Required |
Factors Influencing Life Insurance Premiums in Ocoee
Insurance underwriters evaluate several risk variables when determining premium rates for applicants in Ocoee, FL. While national mortality tables form the baseline, individual underwriting determines your specific rate class.
Age and Gender
Age is the most significant pricing factor. Insurance costs increase incrementally each year you age, making early purchase advantageous. Additionally, statistical life expectancy differences mean women generally pay lower life insurance premiums than men for identical coverage amounts.
Health and Medical History
Underwriters review your current health status, height-to-weight ratio, blood pressure, cholesterol levels, and medical history. Conditions such as diabetes, cardiovascular disease, or a history of tobacco use will increase premium rates. Most traditional policies require a paramedical exam, which includes blood and urine samples drawn at your Ocoee home or workplace by a licensed medical technician.
Lifestyle and Occupation
Hazardous hobbies—such as skydiving, private aviation, or rock climbing—can result in premium surcharges or exclusions. Similarly, high-risk occupations are evaluated during underwriting, though standard office workers and professionals face no such occupational rating.
Step-by-Step Process for Securing Coverage
- Calculate Your Coverage Needs: Assess your financial obligations, including outstanding mortgage balances, existing debts, future living expenses for dependents, and educational costs. A standard formula is 10 to 15 times your annual income, adjusted for personal liabilities.
- Determine the Policy Type: Decide whether temporary protection (term) or lifelong coverage (permanent) aligns best with your financial objectives.
- Compare Quotes from Multiple Carriers: Request quotes from independent insurance brokers or direct insurers licensed to operate in Florida to compare premium rates and financial strength ratings (such as those from A.M. Best).
- Complete the Application and Underwriting: Submit the formal application and schedule your paramedical exam. Answer all medical and lifestyle questions accurately; misrepresentations can result in claim denials later.
- Review and Accept the Policy: Once underwriting is complete, review the policy contract during your free-look period. Sign the delivery receipt, set up recurring premium payments to prevent accidental lapses, and store the physical or digital contract in a secure location.
Frequently Asked Questions About Life Insurance in Ocoee
Do I need a medical exam to get life insurance in Ocoee?
Not necessarily. While traditional policies with the lowest rates require a paramedical exam, many insurers offer no-exam life insurance, accelerated underwriting, or simplified issue policies. These options rely on electronic databases, prescription history checks, and motor vehicle reports instead of physical blood draws, though they may carry higher premiums or lower coverage limits.
How much life insurance coverage do I realistically need?
Your coverage amount should cover immediate end-of-life expenses, outstanding debts (including car loans and credit cards), your remaining mortgage balance, and an income replacement multiplier to support your family's lifestyle for 5 to 10 years or until dependents are self-sufficient. Consulting a financial advisor or using an insurance calculator helps quantify this figure.
Can non-citizens or permanent residents buy life insurance in Florida?
Yes. Legal permanent residents (Green Card holders) and certain visa holders living in Ocoee can purchase life insurance, though options may depend on your visa classification, length of residency in the United States, and ties to the country. Underwriters may require proof of legal status and a valid Social Security Number or Individual Taxpayer Identification Number (ITIN).
What happens if I miss a life insurance premium payment?
Florida law requires a 30-day grace period for life insurance premium payments. If you miss your due date, your policy remains active throughout this 30-day window. If you do not pay the overdue premium before the grace period expires, the policy will lapse. For permanent policies with accumulated cash value, the insurer may automatically draw from the cash value to pay the premium if specified in the contract.
Next Actions for Ocoee Residents
To secure appropriate financial protection, begin by calculating your family's precise income replacement and debt obligations. Gather your medical history, current medication list, and financial records. Contact an independent insurance agent licensed in Florida to review quotes from multiple top-tier carriers, ensuring you secure a policy that balances affordability with robust financial security.
Image Gallery
Select an image to open it in a new tab.

Zara El-Hashem
Sociocultural Dynamics and Academics Writer
