
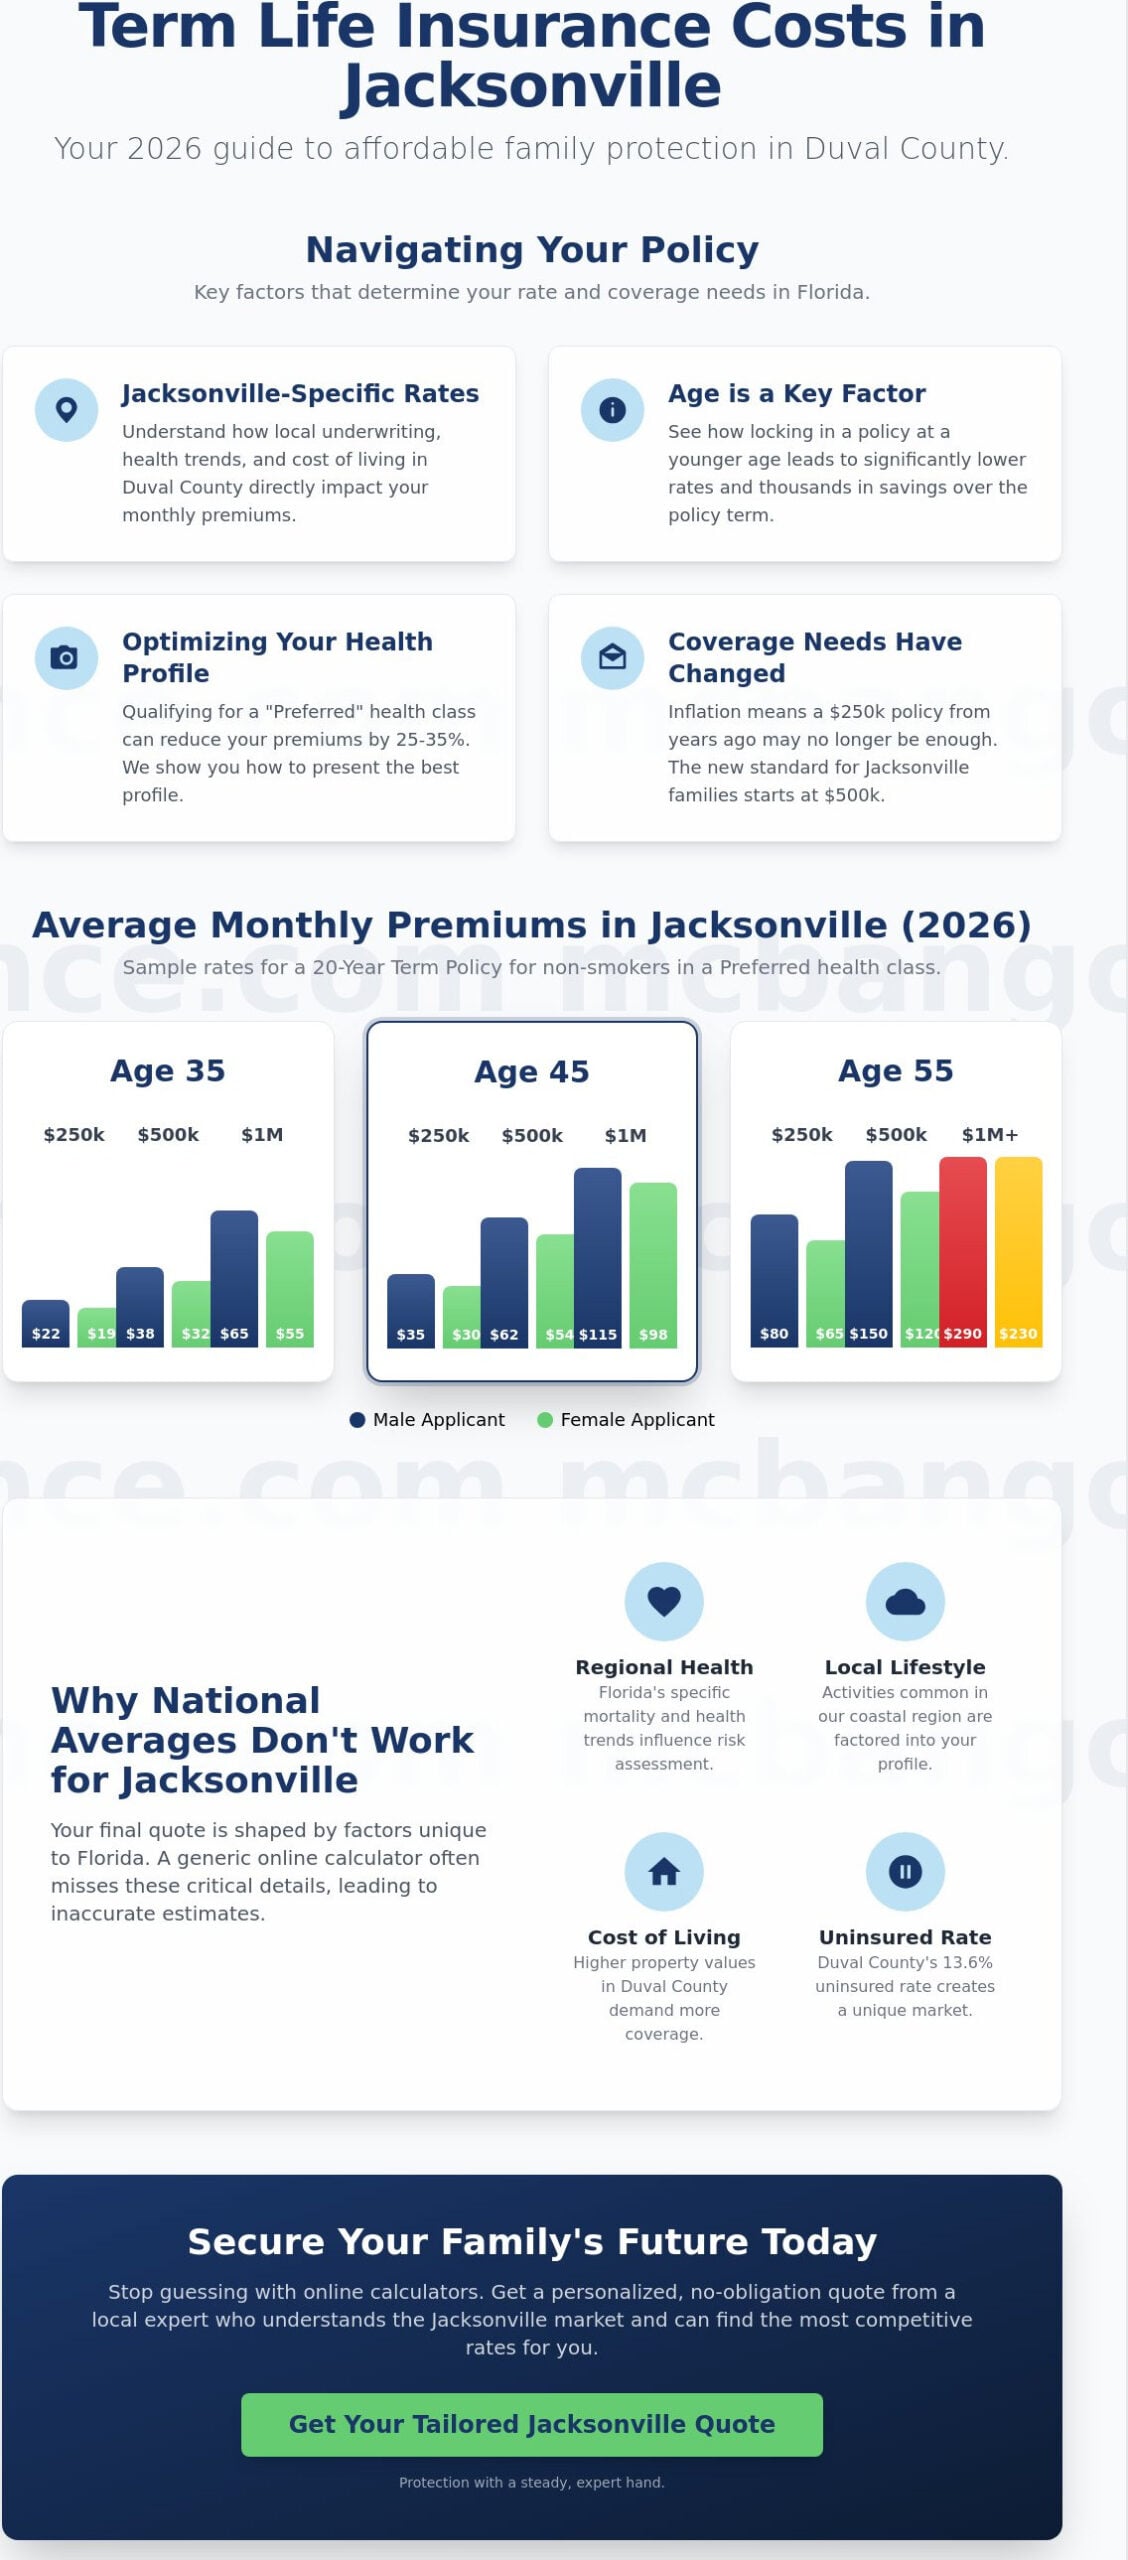
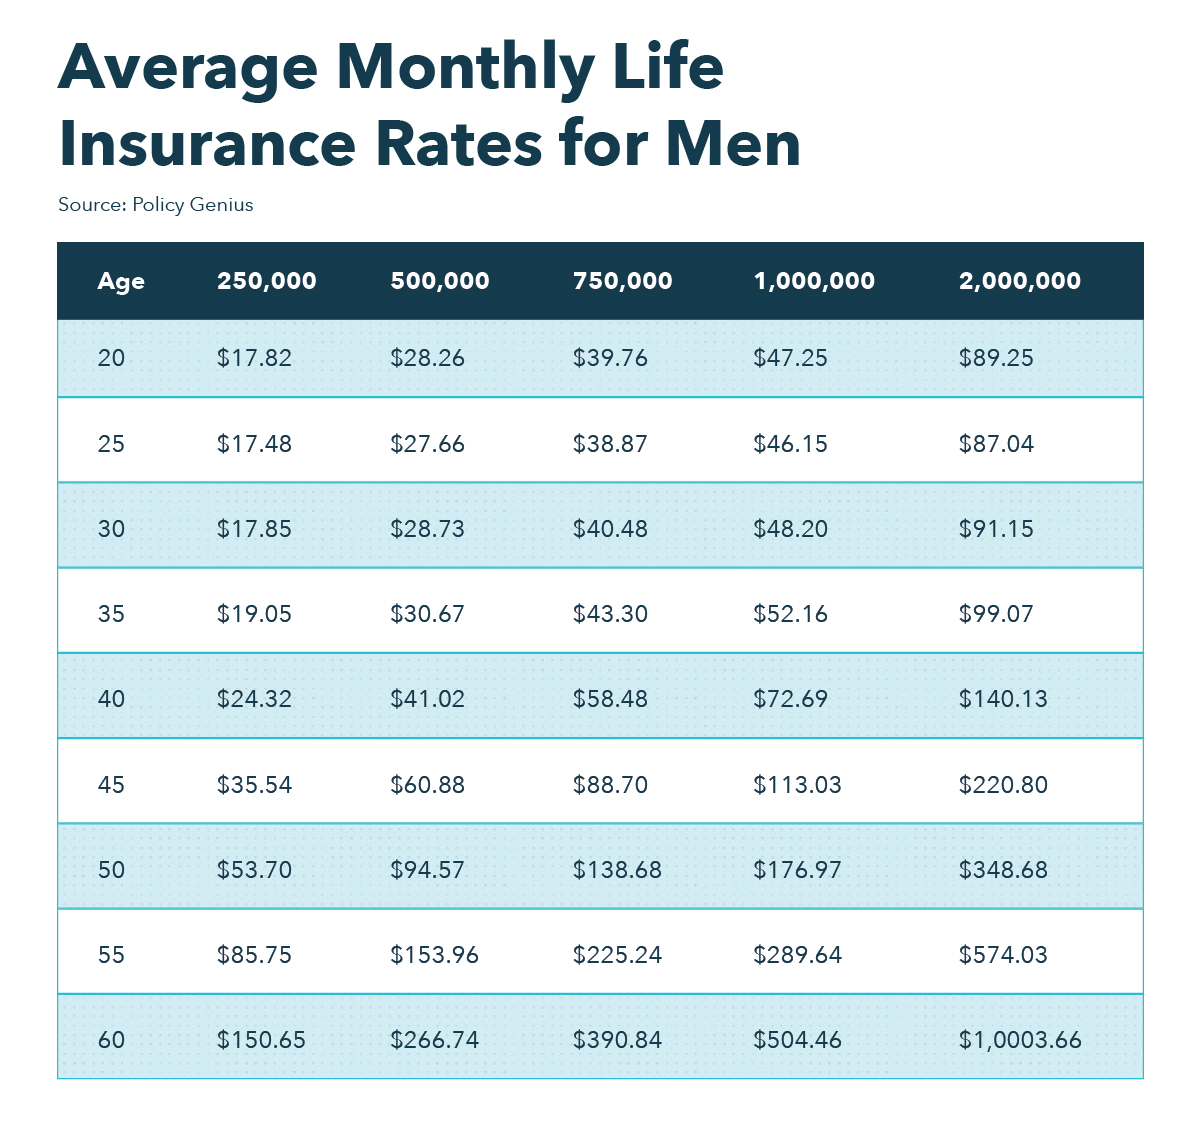
Average term life insurance monthly rates increase steadily as you age, ranging from roughly $15 to $25 per month for a healthy 30-year-old seeking $500,000 in 20-year term coverage to approximately $45 to $70 per month for a 50-year-old for the exact same policy. Premiums typically compound by 8% to 12% per year as you reach middle age.
Understanding Term Life Insurance Pricing Fundamentals
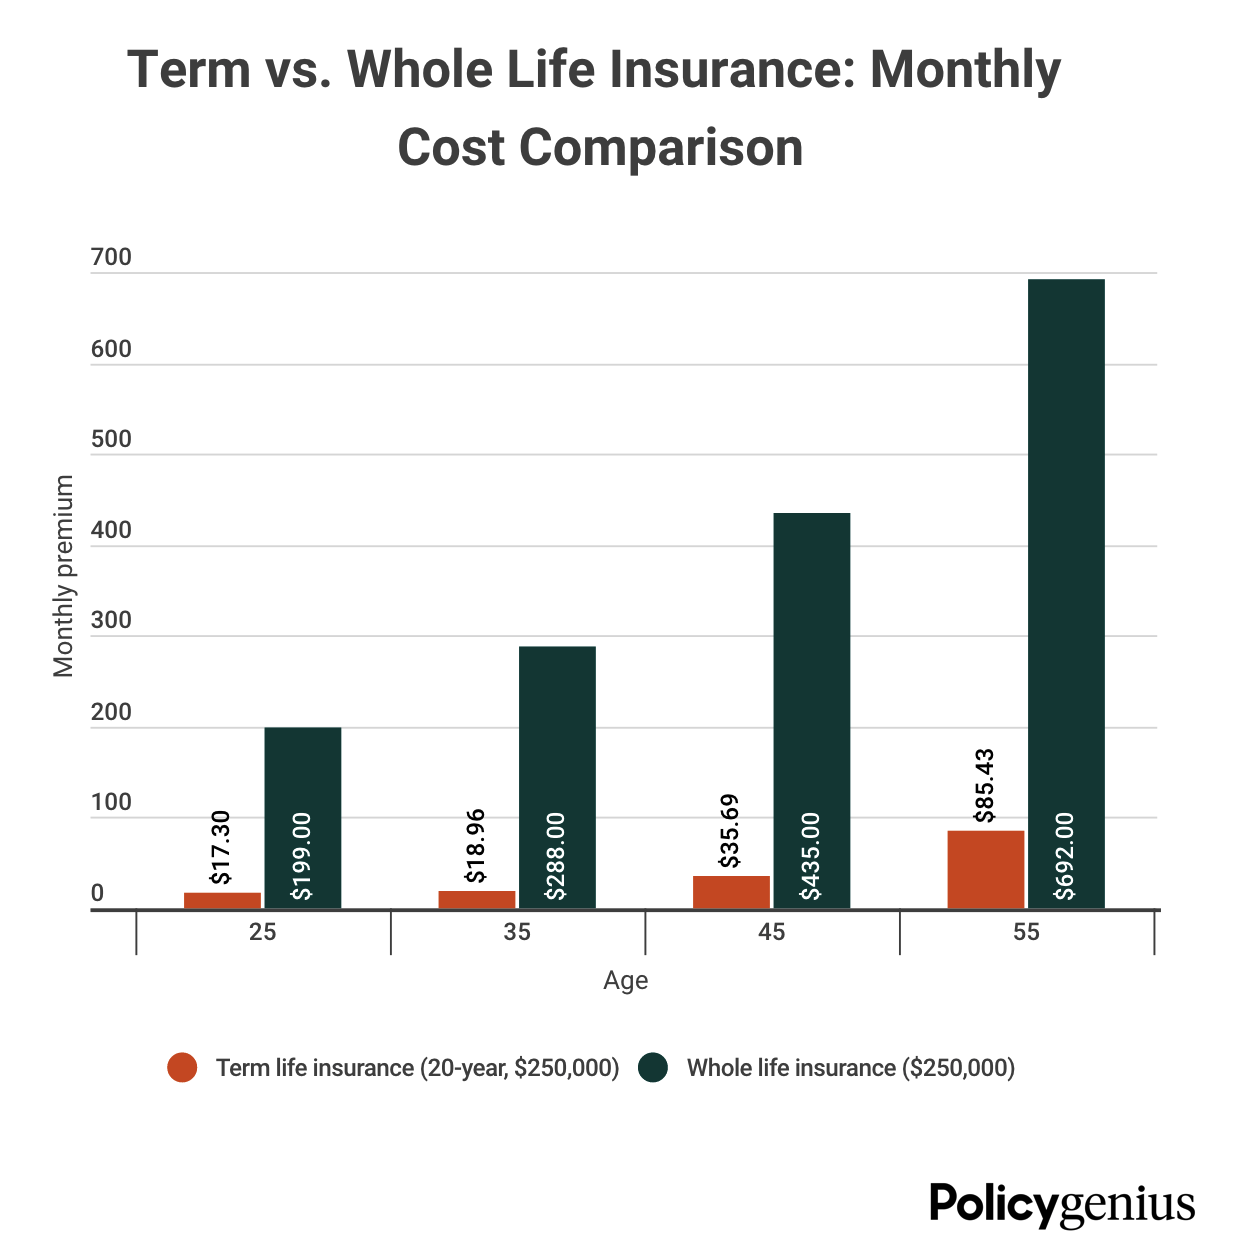
Term life insurance is designed to provide straightforward financial protection for a specified period—typically 10, 15, 20, 25, or 30 years. Unlike permanent life insurance policies (such as whole or universal life), term policies do not contain a cash value component. Every dollar paid in monthly premiums goes directly toward covering the risk of death during the active term, making term life the most affordable and cost-effective form of life insurance available.
Insurance underwriters calculate life insurance rates using actuarial science, which projects mortality risk based on large statistical populations. Age is the single most influential variable in this equation. As an applicant grows older, statistical life expectancy decreases, increasing the insurer's likelihood of paying out a death benefit during any given term. Consequently, insurance carriers adjust premiums upward for older entry ages to offset this statistical risk.
Beyond age, insurers evaluate several secondary risk categories during underwriting to assign an applicant to a specific rate class (sometimes called a risk classification). The standard risk categories, from least expensive to most expensive, include:
- Preferred Plus (Super Preferred): Exceptional health, optimal body mass index (BMI), clean personal and family medical history, non-tobacco user.
- Preferred: Excellent health, slight deviations in BMI or minor managed conditions (like mild controlled cholesterol), non-tobacco user.
- Standard Plus: Above-average health, moderate family medical history risks or slightly higher BMI, non-tobacco user.
- Standard: Average health and life expectancy, controlled minor medical conditions, non-tobacco user.
- Preferred / Standard Tobacco: Applicants who use cigarettes, cigars, e-cigarettes/vapes, or smokeless tobacco, regardless of general physical health.
Understanding how age intersects with these rating classes is essential for estimating baseline costs and evaluating life insurance quotes.
Average Monthly Term Life Insurance Rates by Age
The following representative table illustrates average monthly rates for non-tobacco users in the Preferred underwriting tier across various age brackets, coverage amounts, and term lengths. Rates reflect industry averages across major national life insurance carriers.
| Entry Age | Gender | $250,000 / 10-Yr Term | $500,000 / 20-Yr Term | $1,000,000 / 20-Yr Term | $500,000 / 30-Yr Term |
|---|---|---|---|---|---|
| 20 Years | Female | $11.50 | $16.20 | $26.80 | $23.50 |
| 20 Years | Male | $13.10 | $19.80 | $33.40 | $30.10 |
| 30 Years | Female | $12.30 | $18.50 | $30.20 | $28.40 |
| 30 Years | Male | $14.20 | $22.70 | $38.90 | $36.80 |
| 40 Years | Female | $16.80 | $28.90 | $49.50 | $47.20 |
| 40 Years | Male | $19.50 | $35.40 | $62.80 | $59.60 |
| 50 Years | Female | $31.40 | $61.20 | $112.50 | $108.30 |
| 50 Years | Male | $41.80 | $82.60 | $154.10 | $146.90 |
| 60 Years | Female | $74.20 | $168.40 | $318.90 | N/A* |
| 60 Years | Male | $104.50 | $235.10 | $448.20 | N/A* |
*Note: Most life insurance underwriters restrict 30-year term policy issuances to applicants under age 50 or 55 due to maximum age cutoffs at policy expiration.
Detailed Breakdown by Age Group
Rates for Applicants in Their 20s
Purchasing term life insurance in your 20s secures the lowest baseline rates available in adulthood. At this stage, chronic health conditions are statistically rare, and mortality risk is at its lowest. A healthy 25-year-old can secure a $500,000 20-year term policy for under $20 per month. Locking in a long-term policy early shields young adults against future price increases caused by aging or newly diagnosed medical conditions.
Rates for Applicants in Their 30s
During your 30s, premium rates remain highly affordable, though they begin a gradual upward slope. Rates for a 20-year or 30-year term policy generally increase by roughly 3% to 5% for each year you wait between ages 30 and 39. This decade represents the peak demand window for term life insurance, as people frequently buy homes, marry, and raise young children. Securing coverage during early 30s provides substantial financial protection for growing families at manageable monthly rates.
Rates for Applicants in Their 40s
In your 40s, the slope of annual premium increases steepens noticeable. Between ages 40 and 49, monthly costs for a 20-year term policy often increase by 8% to 10% per year of age. A 45-year-old applicant pays significantly more for identical coverage than a 40-year-old. This rate acceleration reflects a higher statistical prevalence of cardiovascular changes, metabolic markers, and early-stage chronic illnesses identified during underwriting medical exams.
Rates for Applicants in Their 50s
Entering your 50s shifts term life insurance from modest monthly line items into significant household budget allocations. A 20-year term policy for $500,000 that costs $35 per month at age 40 can easily rise past $80 to $100 per month for a 50-year-old male. Furthermore, 30-year term options become scarce or restricted by insurance carriers as maximum issue age caps (often set between 50 and 58 depending on the insurer) take effect.
Rates for Applicants in Their 60s and Beyond
By age 60, term life insurance costs reflect elevated short-to-medium-term mortality risks. Policy terms are frequently restricted to 10-year or 15-year options. A 60-year-old male purchasing a 20-year, $500,000 policy will face premiums exceeding $200 per month, even in standard health. At this stage, policyholders often opt for smaller coverage amounts tailored to specific needs, such as paying off a remaining mortgage balance or covering final expenses.
Key Factors That Drive Monthly Premiums Beyond Age
While age establishes the baseline premium tier, several additional factors determine the actual rate quoted by an insurance company.
1. Gender Differences
Biological females systematically pay lower life insurance premiums than males of the same age across all health classes. According to demographic mortality data published by national public health agencies such as the Centers for Disease Control and Prevention (CDC), females in the United States have a higher average life expectancy than males. On average, women pay 15% to 25% less per month for identical term life policies.
2. Physical Health and Medical History
Underwriting processes thoroughly examine an applicant's current health and historical medical record. Primary metrics evaluated include:
- Blood Pressure and Cholesterol: Controlled levels through lifestyle or basic medication keep applicants in top rating categories, while unmanaged hypertension or severe lipid imbalance elevates rates.
- Body Mass Index (BMI): Height-to-weight ratios are compared against insurer-specific build charts. Overweight or obese classifications can push an applicant from Preferred to Standard rates, doubling monthly costs.
- Personal and Family Medical History: A history of cancer, heart disease, stroke, or diabetes in the applicant or immediate family members (parents/siblings) before age 60 can trigger higher risk classifications.
3. Tobacco and Nicotine Usage
Tobacco use has the single largest immediate impact on term life rates outside of severe medical diagnoses. Smokers pay roughly 200% to 300% more per month than non-smokers of the same age. Insurers test for cotinine (a nicotine metabolite) during blood and urine screenings. Products triggering tobacco rates typically include:
- Cigarettes and cigars
- E-cigarettes and nicotine delivery vapes
- Chewing tobacco and nicotine pouches
- Nicotine replacement therapies (gum, patches) under certain carrier guidelines
4. Policy Length and Benefit Amount
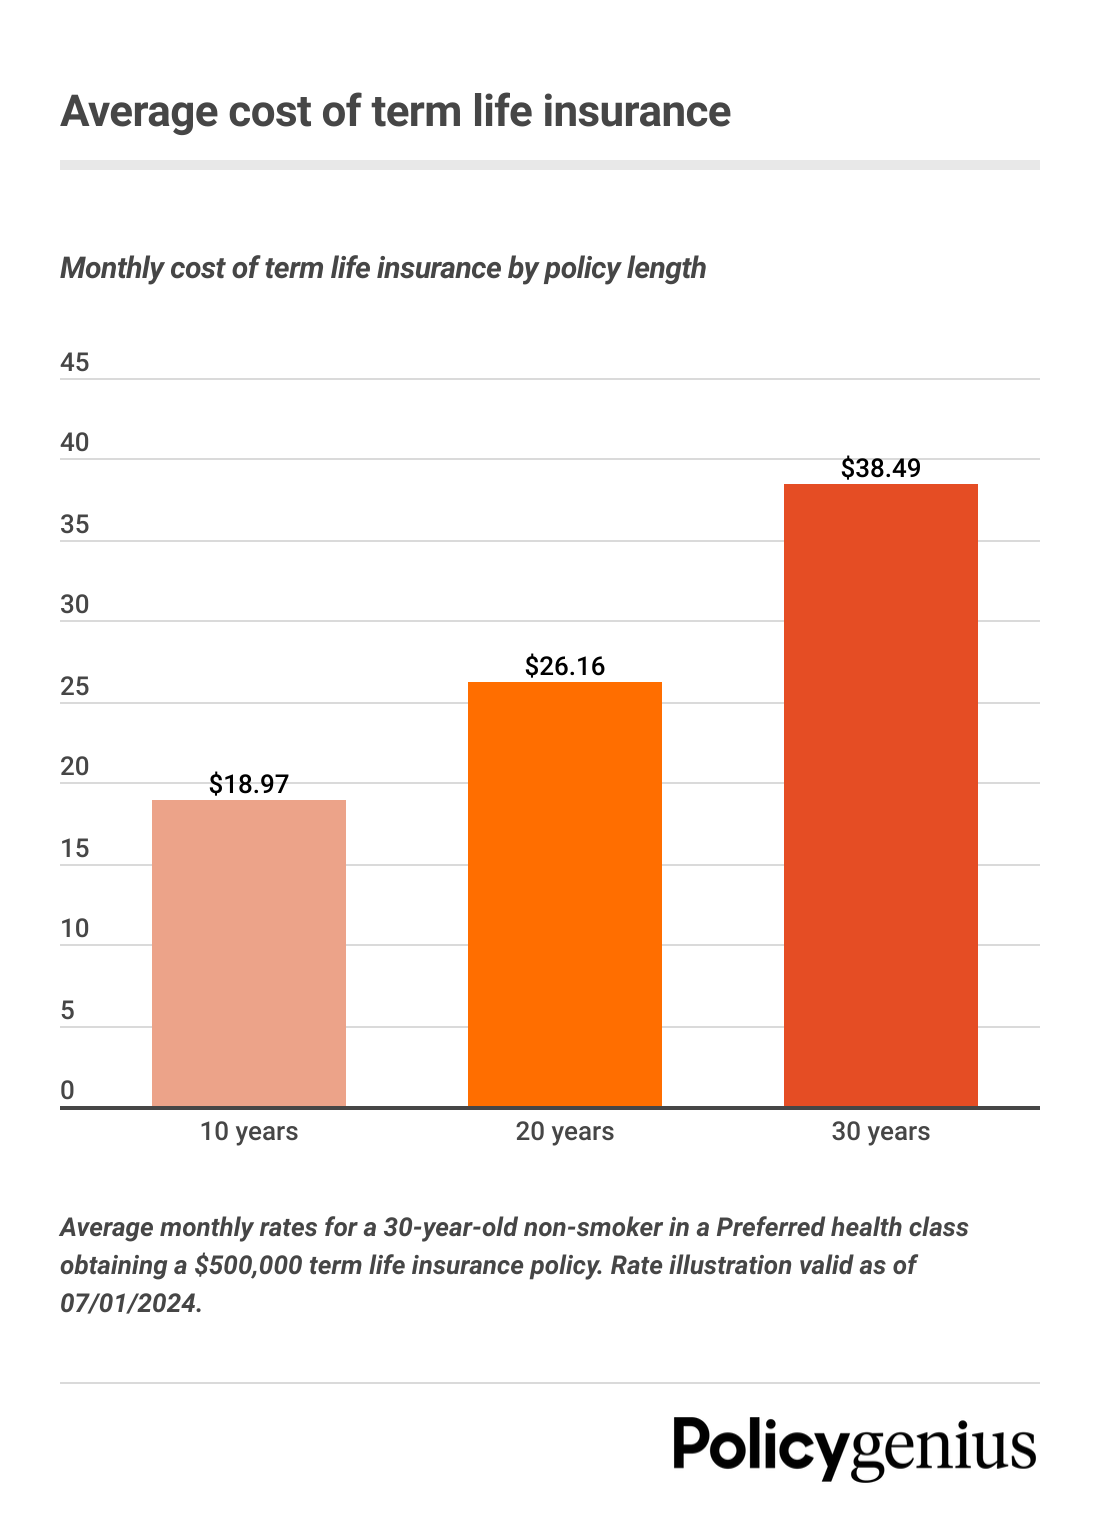
The mathematical structure of the coverage directly dictates price. Doubling the coverage amount from $250,000 to $500,000 does not double the premium; fixed administrative costs remain constant, so cost per thousand dollars of coverage decreases as benefit levels rise. However, increasing term length (e.g., from a 10-year term to a 30-year term) exponentially increases the carrier's exposure window, driving up the monthly rate significantly.
Strategies to Secure the Lowest Term Life Insurance Rates
Navigating life insurance purchases effectively requires balancing long-term financial obligations with immediate monthly affordability.
| Strategy | Description |
|---|---|
| 1. Lock In Rates Early | Buy coverage as early as possible to lock in lower age brackets. |
| 2. Utilize Laddering | Stagger multiple policies with varying terms to reduce total cost. |
| 3. Work with Brokers | Compare multiple carriers via independent insurance brokers. |
| 4. Request Re-evaluation | Reapply after improving health or quitting tobacco for 12+ months. |
Apply as Early as Possible
Because age is an unchangeable variable that guarantees annual rate increases, locking in a policy today is almost always cheaper than waiting until next year. If you anticipate financial obligations over the next two decades (such as a mortgage or dependents), securing a level-term policy early guarantees that your monthly rate remains fixed for the entire duration, regardless of future health developments.
Implement a Policy Laddering Strategy
Rather than purchasing a single $1,000,000 30-year term policy to cover all potential needs, consider "laddering" multiple policies with different durations. For example:
- Policy A: $500,000 10-year term (covers immediate high-cost years like childcare)
- Policy B: $300,000 20-year term (covers remaining mortgage balance)
- Policy C: $200,000 30-year term (covers income replacement until retirement)
As shorter-term policies expire, your total monthly premium payments step down over time, matching your declining liability profile while saving thousands of dollars over 30 years.
Improve Health Metrics Prior to Application
While you cannot change your age, you can optimize manageable health markers prior to underwriting. Taking 3 to 6 months to lower blood pressure through diet, bring glucose levels into normal ranges, or achieve a lower BMI category can elevate your classification from Standard to Preferred, yielding permanent monthly savings for the life of the term.
Compare Quotes from Independent Brokers
Life insurance carriers maintain distinct underwriting niches. One insurer may penalize family history of cancer less severely, while another may offer favorable rates for controlled high blood pressure. Captive agents represent only a single insurer, whereas independent brokers can compare rates across dozens of top-rated carriers (evaluated for financial stability by agencies like A.M. Best) to find the carrier whose underwriting guidelines best match your specific health profile.
Frequently Asked Questions
Why do life insurance rates increase as you get older?
Life insurance premiums increase with age because mortality risk rises statistically over time. Actuaries calculate pricing based on life expectancy tables. As an applicant ages, the probability of the insurance company having to pay out a claim during the term window increases, requiring higher monthly premiums to compensate for that underwriting risk.
Can rates change during the middle of a term policy?
No. Standard level-term life insurance policies guarantee fixed premium rates for the entire agreed-upon term (such as 10, 20, or 30 years). Your monthly payment will remain identical from year one to the final year of the term, regardless of changes to your health, age, occupation, or lifestyle during that period.
What happens to my rate when my term policy expires?
When a term life insurance policy reaches the end of its duration, coverage typically terminates. Many policies offer a "guaranteed renewability" rider, allowing you to extend coverage on an annual basis without undergoing a new medical exam. However, the renewed rates will be recalculated based on your current age, resulting in astronomical cost increases—often 500% to 1,000% higher than your original locked-in monthly payment.
How far back do insurers check for tobacco use?
Most term life insurance companies ask about tobacco and nicotine usage over the preceding 12 to 24 months. To qualify for non-smoker rates, you must generally be completely free of all nicotine products—including cigarettes, cigars, vapes, and nicotine replacement therapies—for at least one full year prior to application. Some carriers require 3 to 5 years of non-use to qualify for their highest "Preferred Plus" tiers.
Is a medical exam always required to get the best rate?
Not always, but fully underwritten policies involving a medical exam (blood test, urine test, blood pressure check) traditionally yield the lowest rates for healthy individuals. While many modern carriers offer accelerated underwriting or "no-exam" term policies using digital health data and pharmacy records, those applicants with complex medical histories may still achieve lower rates by taking a traditional physical exam to prove their health status.
Next Steps: Calculating Your Coverage Needs
To select the right term duration and coverage amount for your budget, calculate your household's total financial liabilities. Add outstanding debt (mortgage, auto loans, student loans) to expected future expenses (college tuition, living expenses for dependents) and subtract existing liquid assets.
Once your baseline need is established, request quotes from multiple independent carriers to evaluate how your current age aligns with policy offerings. Securing level-term protection early locks in your lowest rate, preserving financial stability for your beneficiaries over the coming decades.
Disclaimer: This article is provided for informational and educational purposes only and does not constitute formal legal, financial, or insurance advice. Life insurance rates, underwriting rules, and policy availability vary by state jurisdiction, carrier policies, and individual health profiles. Consult a licensed insurance agent or financial adviser before making purchasing decisions.
Image Gallery
Select an image to open it in a new tab.


Zara El-Hashem
Sociocultural Dynamics and Academics Writer
