
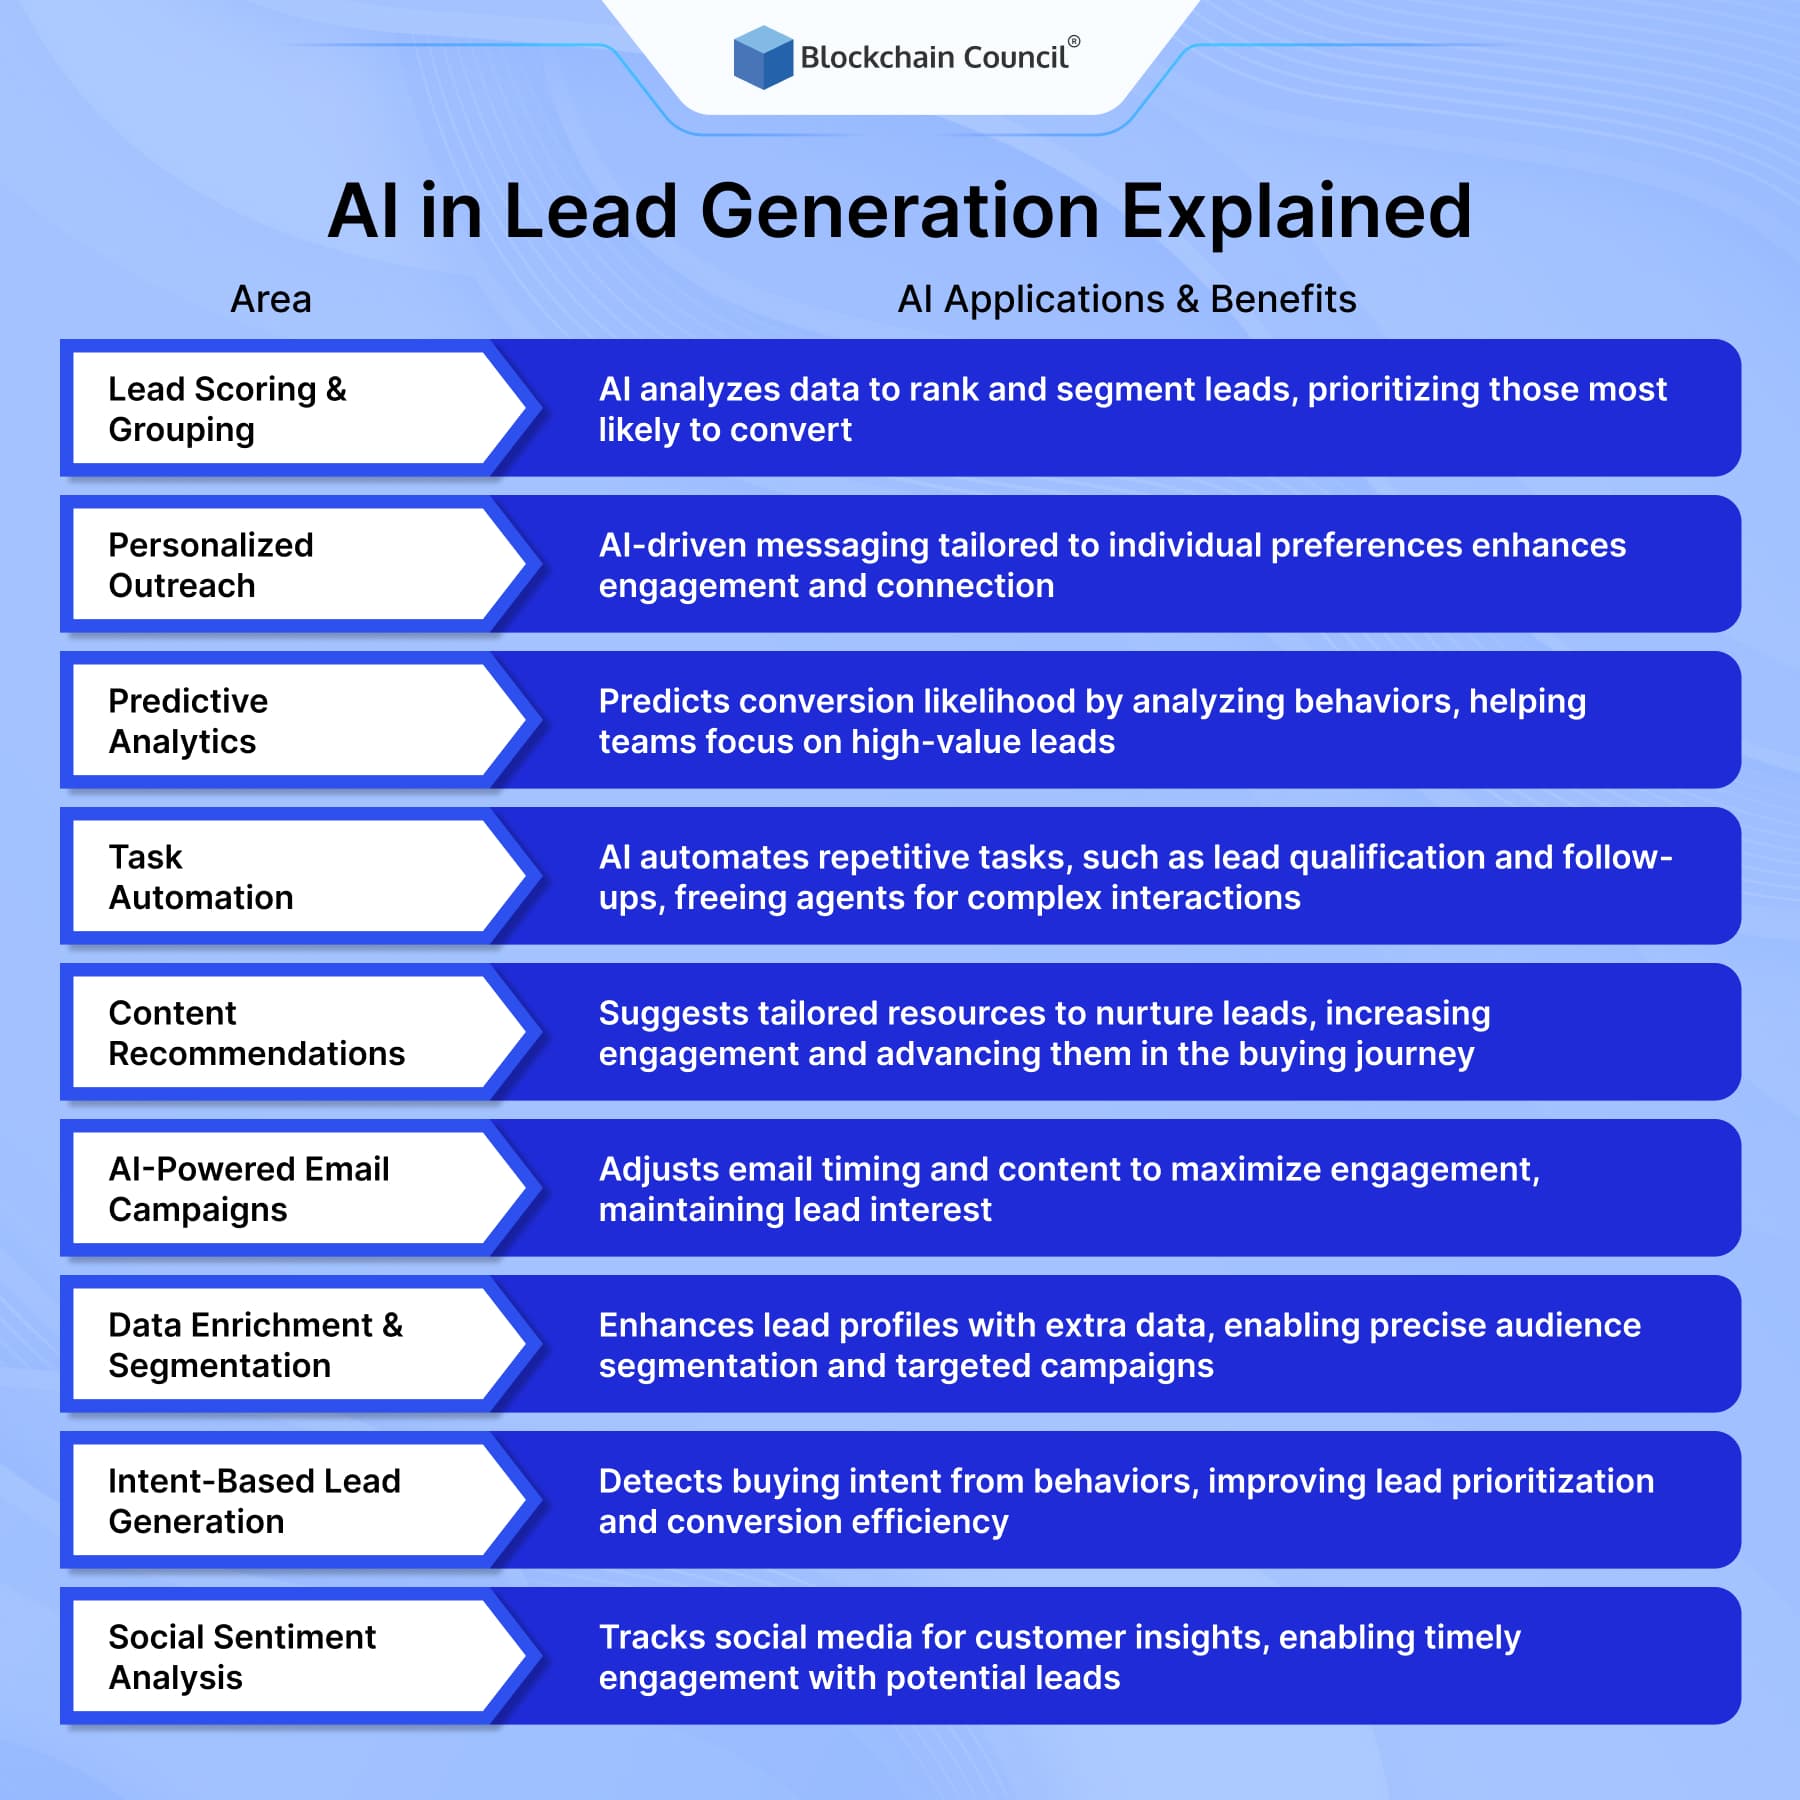
AI lead generation for life insurance uses machine learning, predictive analytics, and natural language processing to identify and qualify high-intent prospects autonomously. In 2026, these systems have evolved from simple chatbots to integrated ecosystems that analyze consumer behavior, automate personalized outreach, and deliver "ready-to-buy" leads directly into an agent's CRM, significantly reducing acquisition costs.
The Transformation of Insurance Prospecting in 2026
The life insurance industry has undergone a fundamental shift in how it identifies potential policyholders. Traditional methods—such as cold calling, generic direct mail, and unoptimized digital ads—have largely been replaced by AI-driven systems. These modern tools do not just find "contacts"; they identify "intent." By 2026, the maturity of large language models (LLMs) and the availability of real-time consumer data allow agencies to predict who needs coverage before the consumer even begins a manual search.
AI lead generation operates on the principle of hyper-personalization. Instead of casting a wide net, AI algorithms analyze thousands of data points—including major life events, financial shifts, and online interactions—to determine a prospect's propensity to purchase. For life insurance agents, this means the end of the "numbers game" where hundreds of calls were required to find one interested party. Today, the focus is on high-quality engagement with prospects who have already been pre-qualified by an autonomous system.
Core Technologies Powering Modern Lead Generation
To understand how AI generates leads for life insurance, it is essential to examine the underlying technologies that have become industry standards as of 2026.
Predictive Analytics and Propensity Modeling
Predictive analytics uses historical data to forecast future outcomes. In life insurance, AI models are trained on millions of past successful conversions. The software looks for patterns in demographic data, credit signals, and public records (such as home purchases or marriages). When a consumer’s data profile matches these historical success patterns, the AI flags them as a high-propensity lead. This allows agents to prioritize their time on individuals most likely to pass underwriting and commit to a policy.
Natural Language Processing (NLP) and Conversational AI
By 2026, conversational AI has moved far beyond the "if-then" logic of early chatbots. Modern NLP allows AI assistants to conduct complex, empathetic conversations with prospects via SMS, web chat, or voice. These assistants can answer detailed questions about term vs. whole life policies, explain riders, and handle common objections. This "top-of-funnel" nurturing happens 24/7, ensuring that no lead is lost due to a delayed human response.
Automated Data Enrichment
Lead quality is often hampered by incomplete information. AI lead generation platforms now automatically "enrich" a lead the moment a name or email is captured. The system pulls data from social media, professional networks, and public databases to provide the agent with a full profile, including estimated income, family size, and current home equity. This context allows the agent to tailor their sales pitch perfectly during the first human-to-human interaction.
The AI Lead Generation Workflow
Implementing AI into the lead generation process involves a structured pipeline that transforms raw data into a closed policy.
- Data Ingestion and Monitoring: The AI monitors digital signals across the web. This includes search queries related to "estate planning," interactions with financial calculators, or social media updates regarding new additions to a family.
- Intent Scoring: Not every search for "life insurance" is a lead. The AI scores intent by analyzing the depth of engagement. A user who spends ten minutes on a "term life vs. permanent life" comparison page receives a higher score than someone who accidentally clicked an ad.
- Autonomous Initial Contact: High-scoring leads are immediately contacted by an AI agent. This initial outreach is designed to qualify the lead further—asking about health history, budget, and specific needs.
- Qualification and Routing: If the prospect meets the agency’s specific criteria (e.g., age, income bracket, or health status), the lead is "hot-transferred" to a human agent. In 2026, this often includes a brief summary generated by the AI for the human agent, outlining exactly what the prospect cares about most.
- Continuous Nurturing: Leads that are not yet ready to buy are not discarded. The AI places them in a long-term nurturing sequence, sending personalized content based on their specific concerns until they reach a state of "buying readiness."
Comparing Lead Generation Strategies
The following table compares traditional lead generation methods with the AI-enhanced systems common in 2026.
| Feature | Traditional Lead Gen | AI-Enhanced Lead Gen (2026) |
|---|---|---|
| Lead Quality | Low to Moderate (Inconsistent) | High (Pre-qualified via intent) |
| Speed to Lead | Minutes to Hours | Instant (Sub-second response) |
| Personalization | Generic/Template-based | Hyper-personalized (Context-aware) |
| Data Depth | Name, Phone, Email | Full financial and life-event profile |
| Scalability | Limited by staff hours | Virtually unlimited |
| Cost Per Acquisition | High (Due to wasted labor) | Lower (Higher conversion rates) |
| Compliance Risk | Manual tracking (High risk) | Automated (Built-in audit trails) |
Compliance, Ethics, and Data Privacy
In the 2026 insurance landscape, AI usage is strictly regulated. The National Association of Insurance Commissioners (NAIC) and various state-level privacy acts (building upon the foundations of CCPA and GDPR) require absolute transparency in how AI models make decisions.
Transparency and Algorithmic Bias
Insurance agencies must ensure their AI tools do not engage in "digital redlining" or discriminatory practices. Modern AI platforms include "Explainability Modules" that can justify why a lead was scored a certain way. This is crucial for maintaining compliance with fair lending and insurance practices. Agencies are responsible for auditing their AI vendors to ensure that the training data used for lead scoring is representative and unbiased.
Consent-Based Marketing
With the tightening of TCPA (Telephone Consumer Protection Act) regulations through 2025 and 2026, AI systems are now designed with "Consent-First" architectures. Before an AI assistant initiates a call or text, it verifies the lead's opt-in status through a blockchain-verified or encrypted digital handshake. This protects agencies from the massive fines associated with unsolicited marketing in the AI age.
Implementation Costs and ROI Considerations
Adopting AI lead generation requires an initial investment, but the return on investment (ROI) is generally realized through increased agent productivity and lower churn.
- Software-as-a-Service (SaaS) Fees: Most agencies utilize specialized platforms (like upgraded versions of Salesforce, HubSpot, or industry-specific tools like Velocity or AgencyBloc) that charge a monthly subscription. In 2026, these costs typically range from $200 to $1,000 per user, depending on the level of AI automation.
- Data Acquisition Costs: Accessing high-intent data streams and third-party enrichment APIs is a variable cost. Agencies often pay "per enriched lead," which can add $5 to $50 to the cost of a lead, but this is offset by the much higher closing ratio.
- Training and Integration: There is a "human cost" to implementation. Agents must be trained to handle AI-qualified leads differently than cold leads. The focus shifts from "convincing" to "consulting," which may require a change in sales training protocols.
The ROI is typically measured by the Customer Acquisition Cost (CAC). Agencies moving to AI-led models in 2026 frequently report a 30% to 50% reduction in CAC because agents spend 90% of their time talking to qualified buyers rather than prospecting.
Common Pitfalls to Avoid
Despite the power of AI, several common mistakes can undermine the effectiveness of a lead generation program:
- Over-Automation: Relying too heavily on AI can strip the empathy out of life insurance sales. Life insurance is a sensitive, emotional purchase. If the transition from AI to human is not seamless, the prospect may feel like "just a number" and disengage.
- Poor Data Hygiene: AI is only as good as the data it processes. If an agency’s CRM is filled with old, inaccurate, or duplicate records, the AI will produce flawed scoring and outreach.
- Ignoring the Human Element: The most successful agencies in 2026 use AI to augment their agents, not replace them. The AI handles the "drudge work" of prospecting, while the human agent provides the expert guidance and emotional connection needed to finalize a policy.
Frequently Asked Questions
Does AI lead generation work for independent agents or just large carriers?
By 2026, AI lead generation is highly accessible to independent agents. While large carriers may build proprietary models, independent agents have access to numerous third-party "plug-and-play" AI platforms that integrate directly into standard CRMs. These tools allow small agencies to compete with the marketing reach of national corporations by using the same predictive data at a smaller scale.
How do I know if the AI-generated leads are compliant with 2026 privacy laws?
You must verify that your AI provider uses "Primary Source" data and has a robust system for tracking opt-in consent. Most reputable vendors provide a "Compliance Certificate" or a digital audit trail for every lead generated. Always ensure your vendor complies with the latest NAIC AI Model Bulletins and state-specific privacy requirements.
Will AI replace life insurance agents by 2026?
No. In 2026, the agent's role is more important than ever, but it has changed. AI excels at finding and qualifying leads, but it lacks the nuance required for complex estate planning or navigating the emotional aspects of a client's death benefit needs. AI replaces the prospecting function, not the advisory function.
What is the average "Speed to Lead" with AI?
In 2026, the industry standard for "Speed to Lead" is under 10 seconds. When a prospect interacts with a digital asset (like a quote tool), the AI initiates contact almost instantly. Research consistently shows that contacting a lead within the first minute increases conversion rates by over 300% compared to waiting even 30 minutes.
Can AI help with lead nurturing for people who aren't ready to buy yet?
Yes, this is one of AI's greatest strengths. AI "drip" campaigns in 2026 are dynamic. If a prospect's behavior changes—for example, if they start researching "mortgage protection" six months after their initial inquiry—the AI detects this shift and automatically adjusts the nurturing content to match their new interest, re-triggering the agent's involvement at the perfect moment.
Moving Forward: Next Steps for Agencies
To begin leveraging AI for life insurance lead generation, agencies should start with a focused pilot program.
- Audit Your Current Pipeline: Identify where you are losing prospects. Is it the initial contact speed, or is it a lack of follow-up?
- Choose a Specialized AI Tool: Look for platforms that specialize in the insurance vertical. General-purpose AI often lacks the "knowledge base" required to discuss insurance products accurately and compliantly.
- Prioritize Integration: Ensure your chosen AI tool communicates seamlessly with your existing CRM. Data silos are the primary enemy of AI efficiency.
- Test and Refine: Start by directing 20% of your marketing budget toward AI-driven lead gen. Compare the CPL (Cost Per Lead) and conversion rates against your traditional methods over a 90-day period.
By embracing AI-driven lead generation, life insurance professionals can move away from the inefficiencies of manual prospecting and toward a more profitable, data-driven future where every conversation has a high probability of resulting in a protected family.
Image Gallery
Select an image to open it in a new tab.


Ingrid Bjornson
Global Cyber Policy and Regulation Analyst
