No interest, no payment credit cards—often referred to as 0% introductory APR cards or deferred interest plans—allow consumers to finance purchases without accruing interest for a set period. While "no interest" is a standard feature of these promotional offers, "no payment" is typically a misnomer, as most cards require a minimum monthly payment to maintain the promotional rate.
Understanding the mechanics of these financial tools is essential for avoiding costly traps and maximizing debt-free windows. As of 2026, the landscape of consumer credit has evolved, with stricter regulations on disclosure but increasingly complex terms regarding how interest is calculated if a balance remains after the promotional period ends. This guide explores the technical reality of these cards, the differences between various offers, and how to navigate the fine print effectively.
How No Interest Credit Cards Actually Work
The core appeal of a "no interest" card is the introductory Period (intro APR). During this timeframe, which usually lasts between 12 and 21 months, the card issuer sets the Annual Percentage Rate (APR) to 0% for purchases, balance transfers, or both. This means that as long as you adhere to the terms of the agreement, the cost of borrowing is essentially zero.
However, the "no interest" status is not a permanent feature. It is a loss-leader strategy used by financial institutions to acquire new customers. Once the introductory period expires, the remaining balance is subject to the standard variable APR, which is determined by your creditworthiness and the prevailing federal prime rate. In 2026, standard APRs for consumers with good credit typically range from 18% to 27%, making it imperative to clear the balance before the "cliff" of the promotional expiration.
Purchase vs. Balance Transfer Offers
It is vital to distinguish between a 0% APR offer on new purchases and one on balance transfers.
- 0% Purchase APR: Applies to items you buy after opening the account. This is ideal for financing a specific large expense, such as a home appliance or a medical procedure.
- 0% Balance Transfer APR: Applies to debt moved from an existing high-interest card to the new 0% card. This is a strategic tool for debt consolidation, allowing you to pay down principal without interest eating into your monthly payments.
Many cards offer both, but the duration of the 0% period may differ for each category. Always verify the specific "end date" for each type of transaction within your cardmember agreement.
The Myth of the "No Payment" Feature
The phrase "no interest, no payment" is frequently used in retail marketing, particularly for furniture, electronics, and jewelry. However, in the context of traditional credit cards, a "no payment" requirement is extremely rare. Almost all credit card agreements require a minimum monthly payment, even during a 0% interest period.
The Minimum Payment Requirement
Even if your interest rate is 0%, the bank still requires you to pay back a small portion of the principal every month. This is usually the greater of $25–$40 or 1% to 2% of the total balance. Failure to make this minimum payment can result in:
- Immediate Forfeiture of the 0% Rate: Most issuers include a "penalty APR" clause. If you miss a payment or are more than 60 days late, they can legally revoke your promotional rate and hike your APR to 29.99% or higher.
- Late Fees: You will still be charged a late fee (typically capped by the Consumer Financial Protection Bureau at specific limits), which adds to your principal balance.
- Credit Score Damage: Late payments are reported to credit bureaus, potentially lowering your score by 50 to 100 points and making future credit more expensive.
The only true "no payment" options are usually found in deferred interest retail plans, where the merchant allows you to skip payments for a set number of months (e.g., "No payments for 6 months"). Even then, interest is often silently accruing in the background.

Deferred Interest vs. 0% Introductory APR
This is perhaps the most dangerous technical distinction in the world of credit. While they may look the same on a store sign, their mathematical impact is drastically different.
0% Introductory APR (The Safer Option)
With a standard 0% introductory APR card, interest is waived during the promotional period. If you have a $1,000 balance and only pay off $900 by the time the promo ends, you only owe interest on the remaining $100 starting from that date.
Deferred Interest (The "Trap" Option)
Commonly found in store-branded cards (e.g., home improvement or electronics retailers), deferred interest means the interest is calculated from the date of purchase but is not charged if the balance is paid in full within the promotional period.
If you miss the deadline by even one day—or if you have a single dollar left on the balance—the lender charges you the full interest accumulated from the original purchase date. For a large purchase at 25% APR over 12 months, this "interest bomb" could suddenly add hundreds of dollars to your balance. The Federal Trade Commission (FTC) provides consumer education on avoiding these "gotcha" clauses in retail financing.
Eligibility and Requirements in 2026
Securing a high-quality 0% interest card requires a strong financial profile. In 2026, lenders have become more sophisticated in their risk assessment, using "alternative data" such as rent payment history and utility bills alongside traditional credit scores.
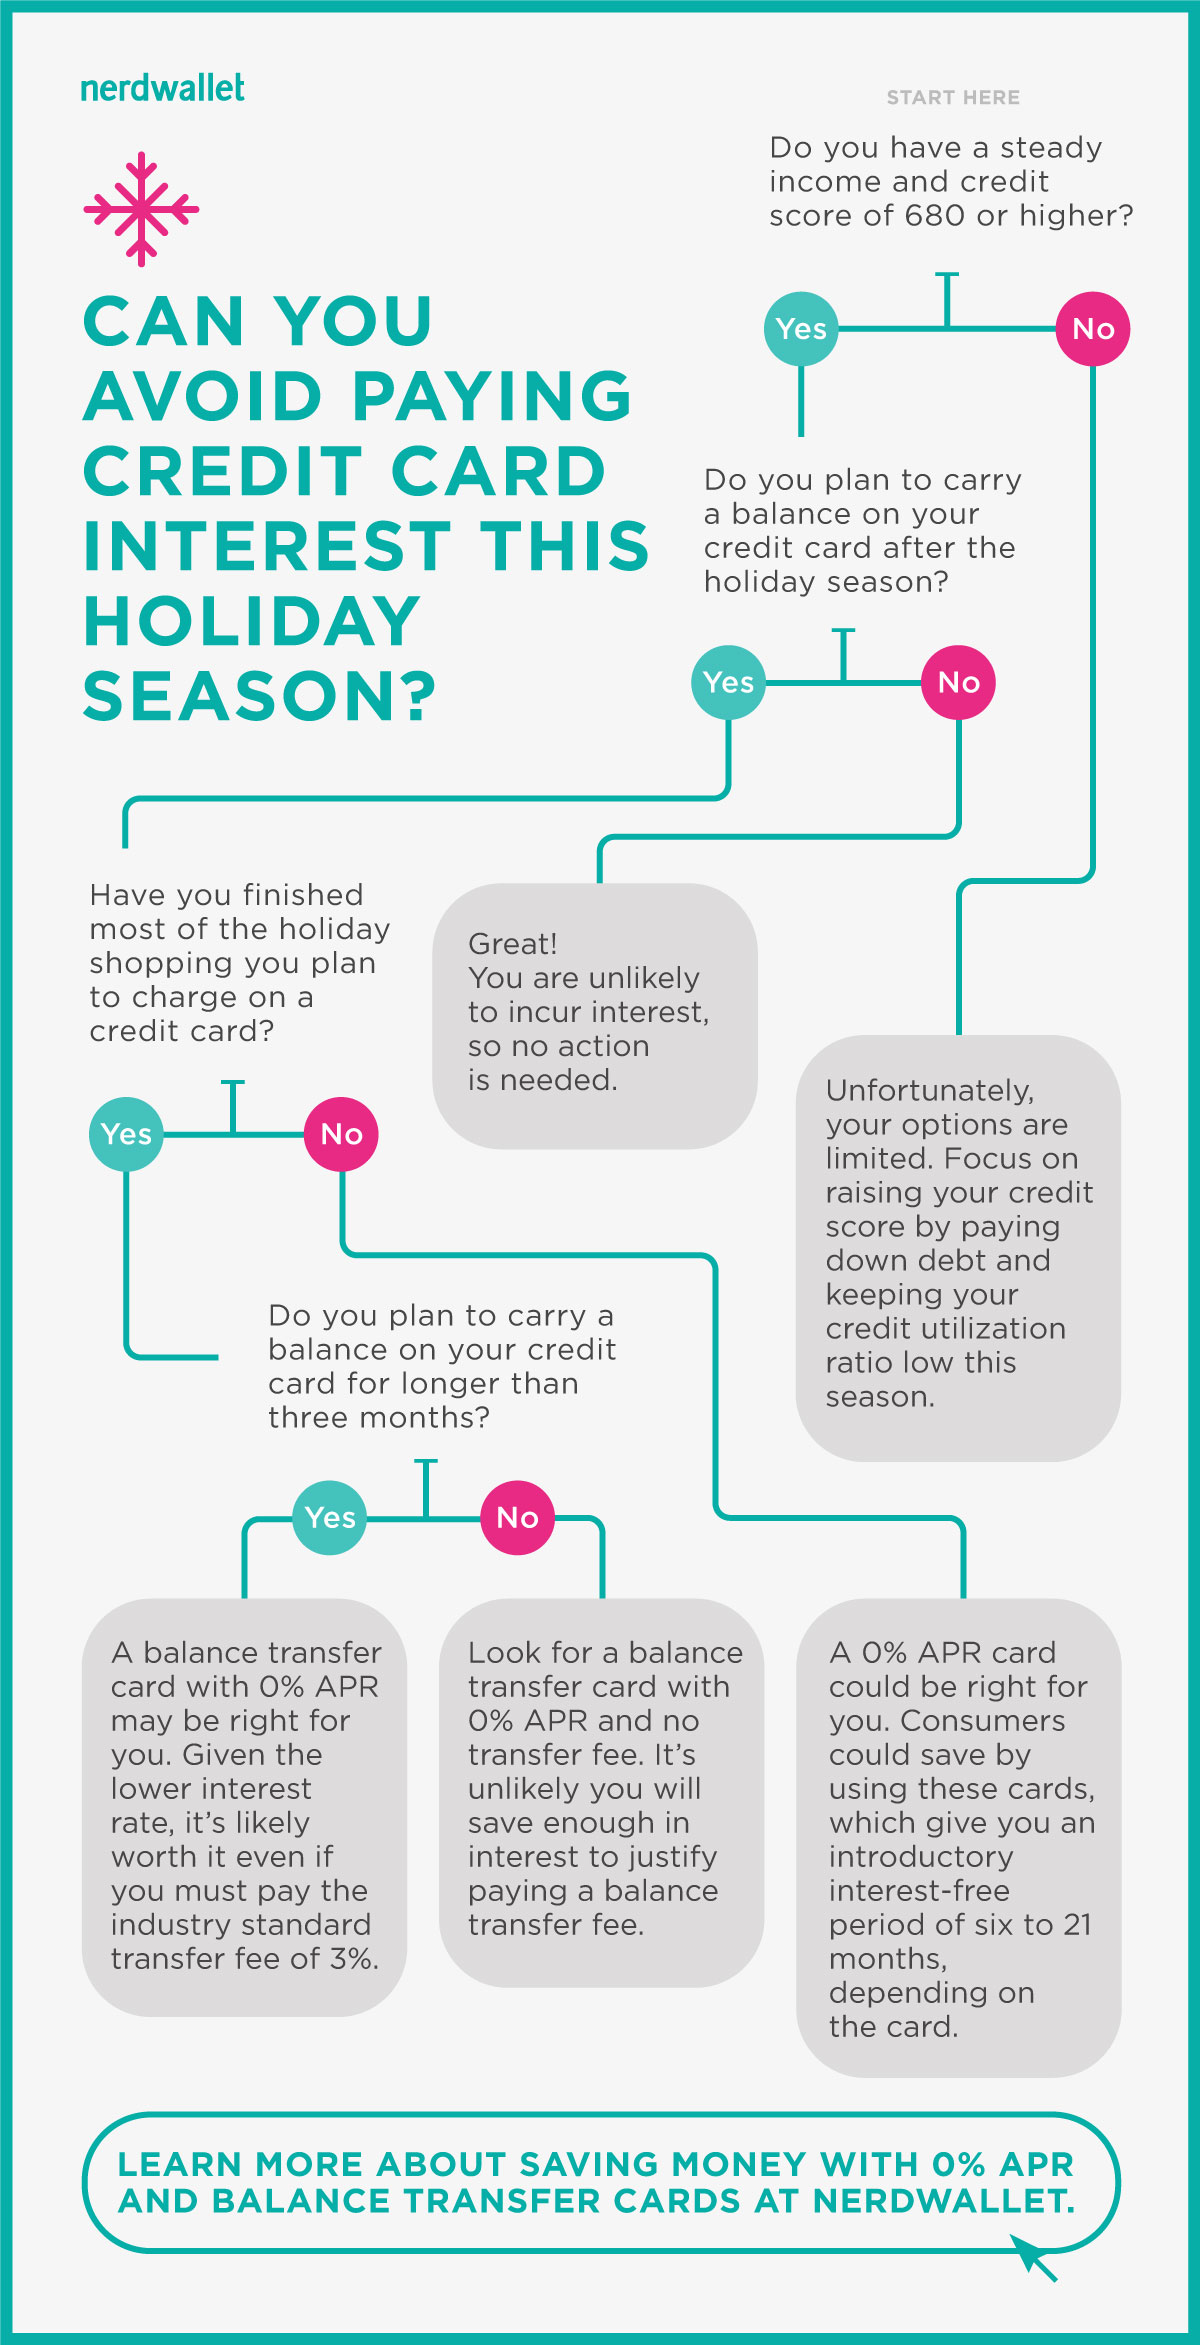
- Credit Score: Generally, a FICO score of 690 or higher (Good to Excellent) is required for the most competitive 0% offers. While some "fair credit" cards offer 0% periods, they are usually shorter (6 months vs. 18 months).
- Debt-to-Income (DTI) Ratio: Lenders look at your monthly debt obligations versus your gross monthly income. A DTI below 36% is standard for approval.
- Recent Inquiries: If you have applied for multiple credit cards in the last six months, you may be flagged as a "high-risk" borrower, leading to a denial even with a high credit score.
Hidden Costs and Potential Pitfalls
While the interest rate is 0%, these cards are not entirely "free." There are several operational costs that consumers often overlook:
- Balance Transfer Fees: If you are moving debt from another card, expect to pay a fee of 3% to 5% of the total amount transferred. For a $10,000 transfer, a 5% fee adds $500 to your debt immediately. You must calculate if the interest savings outweigh this upfront cost.
- Annual Fees: Most 0% APR cards do not have annual fees, but some "premium" cards that offer 0% interest alongside high travel rewards might. Ensure the rewards justify the fee.
- The "All-or-Nothing" Rule: As mentioned, with deferred interest, if you don't pay 100% of the balance, you lose 100% of the benefit.
- Credit Utilization Impact: Charging a large purchase to a 0% card can "max out" that specific card. Even if you aren't paying interest, high utilization (using more than 30% of your available credit) can temporarily lower your credit score.
Comparing Promotional Credit Options in 2026
The following table compares the typical structures of promotional financing available in the current market.
| Feature | 0% Intro APR Card | Deferred Interest Retail Card | Buy Now, Pay Later (BNPL) |
|---|---|---|---|
| Typical Duration | 12–21 Months | 6–12 Months | 4 Weeks – 6 Months |
| Minimum Payment? | Yes, Monthly | Sometimes No, Usually Yes | Yes, Bi-weekly/Monthly |
| Interest Penalty | Only on remaining balance | Retroactive to Day 1 | Usually none, but late fees apply |
| Impact on Credit | High (Hard Inquiry) | High (Hard Inquiry) | Variable (Soft or Hard Inquiry) |
| Best Use Case | Large purchases/Debt consolidation | Specific store purchases | Small to mid-size retail buys |
| Balance Transfer? | Yes | No | No |
Strategies for Managing 0% Interest Cards
To successfully navigate a "no interest" period without falling into debt, a technical, disciplined approach is required.
1. The Reverse Math Strategy
Divide your total balance by the number of months in the promotional period, minus one. If you have an 18-month 0% window and a $3,000 balance, divide by 17. Paying $176.47 per month ensures the balance is cleared before the interest kicks in, providing a one-month "safety buffer" for unforeseen financial hiccups.
2. Auto-Pay for Minimums
Set up an automatic payment for the minimum amount due. This ensures you never accidentally trigger a penalty APR or late fee, which would void your promotional benefits. You can then manually make larger payments to chip away at the principal.
3. Monitoring the Statement Closing Date
Interest-free periods are often tied to "billing cycles" rather than calendar months. Ensure your final payment is processed and cleared several days before the final statement of the promotional period closes.
4. Avoiding "New Debt"
If you are using a card for a balance transfer to pay off debt, avoid using that same card for new purchases. While the transfer might be at 0%, the new purchases might not be, or your payments might be applied to the 0% balance first, allowing the high-interest new purchases to grow.
Frequently Asked Questions
Can I get a 0% interest card with bad credit?
It is difficult to qualify for a traditional 0% intro APR card with a credit score below 630. Consumers with lower scores might find "no interest" offers through credit unions or specialized "secured" cards, but these often have very low limits and shorter promotional windows. Alternatively, retail store cards are easier to get but often carry the risk of deferred interest.
What happens if I can't pay the balance before the 0% period ends?
Any remaining balance will begin accruing interest at the card's standard variable rate. If it is a deferred interest card, you will also be hit with a lump-sum charge for all the interest that would have accrued since the purchase date. To mitigate this, you could attempt to move the remaining balance to another 0% balance transfer card, though this requires another credit check and a new transfer fee.
Does "0% APR" mean there are no fees at all?
No. APR (Annual Percentage Rate) only refers to the interest. You can still be charged late fees, over-limit fees, balance transfer fees, and annual fees. Always read the "Schumer Box"—the standardized table of rates and fees required by the Truth in Lending Act—before signing.
How many 0% interest cards can I have at once?
Technically, there is no legal limit, but your ability to open multiple cards is limited by your credit score and the "velocity" of your applications. Many issuers, such as Chase with their "5/24 rule," will automatically decline applicants who have opened too many accounts in a short period. Managing multiple 0% cards requires meticulous tracking to avoid missing multiple "interest cliffs."
Is "Buy Now, Pay Later" better than a 0% credit card?
BNPL (like Affirm or Klarna) is often better for smaller, short-term purchases because it usually involves a "soft" credit pull that doesn't hurt your score. However, for larger debts or consolidation, 0% credit cards offer much longer repayment windows (up to 21 months) and the ability to earn rewards or cash back.
Practical Recommendation
When seeking a "no interest no payment" credit card, prioritize Bank-issued 0% Introductory APR cards over retail-branded deferred interest plans. The lack of retroactive interest makes bank cards significantly safer.
Before applying, check your credit score through an official source like AnnualCreditReport.com to ensure you meet the "Good to Excellent" threshold. Once approved, calculate your monthly "break-even" payment by dividing the balance by the number of promotional months and automate that payment. Treat the "no payment" marketing as a myth; always pay at least the minimum to protect your credit and your 0% rate.
Image Gallery
Select an image to open it in a new tab.


Lars Thomsen
Global Labor Markets and Economic Strategy Editor
