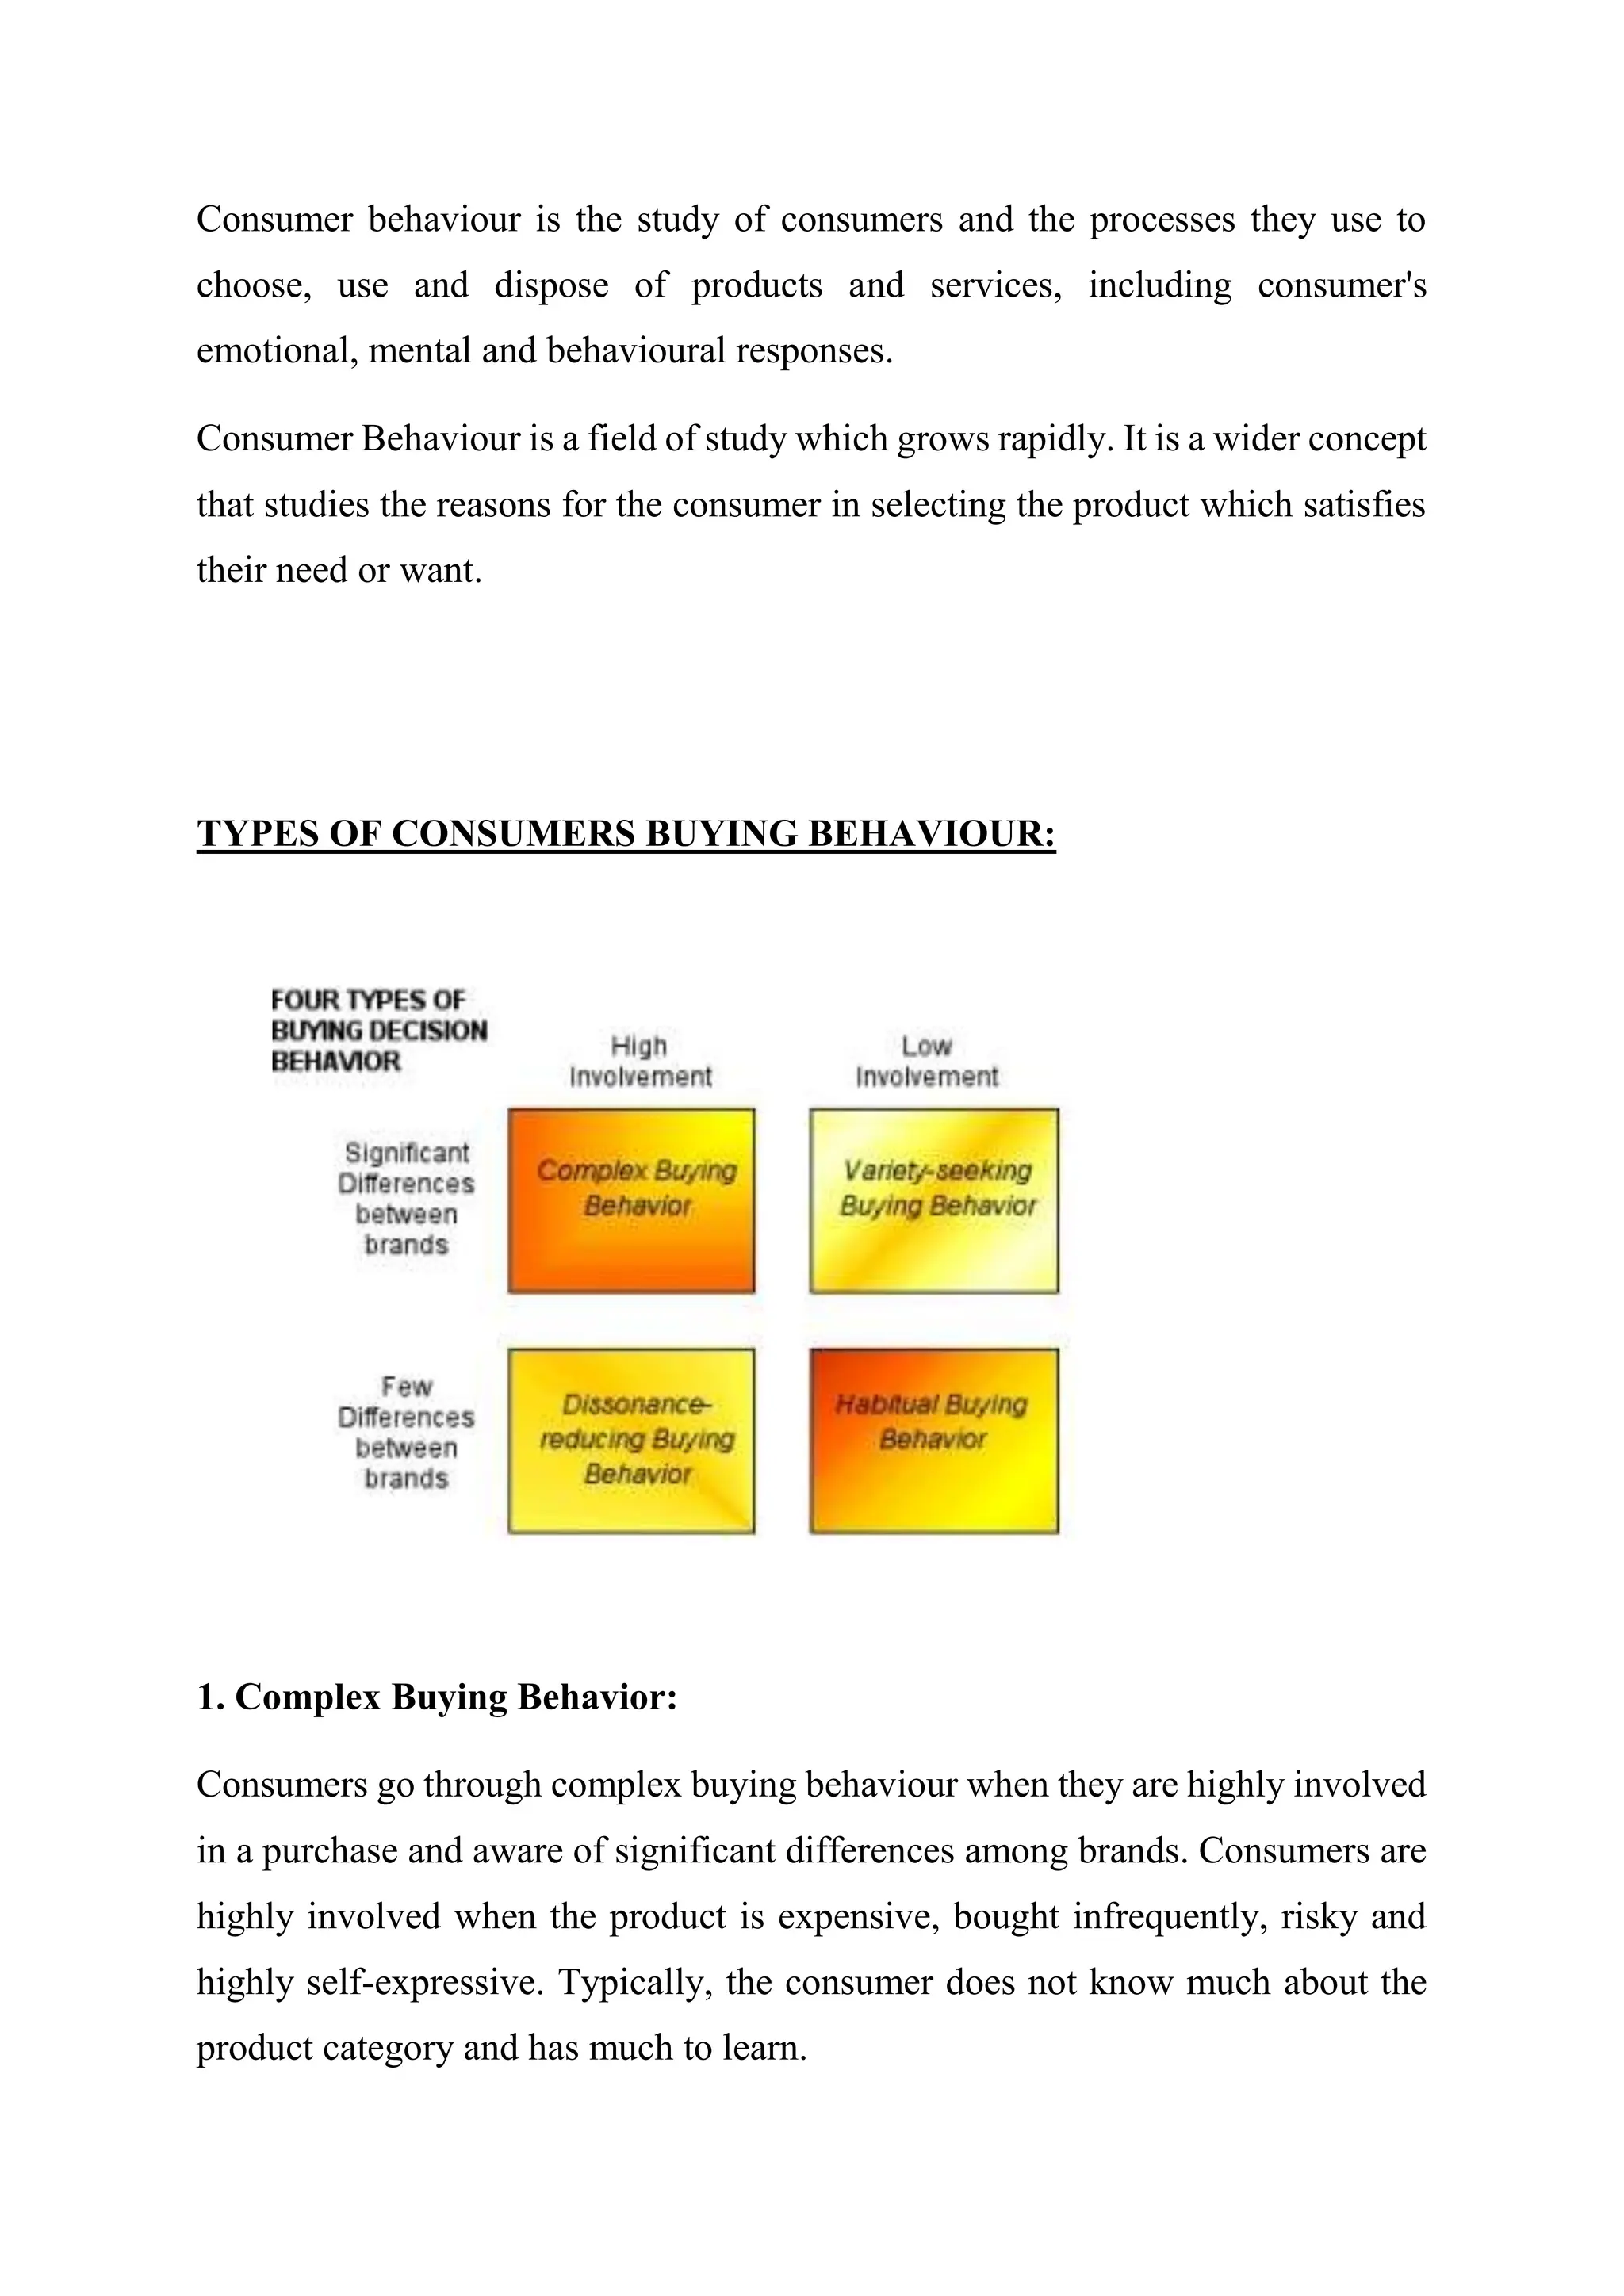
Understanding the consumer buying behaviour towards life insurance involves analyzing the psychological, social, and economic triggers that transition a person from viewing coverage as a distant necessity to completing a purchase. This process is driven by risk perception, life-stage transitions, financial literacy, and the shift toward digital-first engagement platforms in the modern insurance market.
The Psychology of Risk and Protection
At its core, the decision to purchase life insurance is a hedge against catastrophic financial loss for survivors. Unlike consumer goods, life insurance is an "intangible" product; the consumer does not receive an immediate physical benefit. Consequently, the buying behaviour is heavily influenced by the "protection gap"—the difference between the resources needed to maintain a family's standard of living and the resources actually available.
Consumers often rely on heuristics, or mental shortcuts, when assessing the need for life insurance. Many delay the decision due to the "optimism bias," where individuals underestimate the likelihood of premature death or disability. However, the motivation shifts dramatically when individuals experience "trigger events." These are life-altering milestones—such as marriage, the birth of a child, or the acquisition of a significant mortgage—that force a re-evaluation of financial vulnerability.
Key Factors Influencing Consumer Decisions
The modern consumer navigates a complex environment before settling on a policy. Several factors dictate their final decision:
- Financial Literacy: Individuals with higher financial literacy are more likely to understand the difference between term life and permanent (whole or universal) life insurance. Those with lower literacy often prioritize simple, low-cost term products or, conversely, may be overwhelmed by complex investment-linked insurance plans (ILPs).
- Trust in Providers: In the financial sector, trust is the primary currency. Consumers evaluate life insurers based on the organization's reputation for claims processing, historical financial stability, and the transparency of policy documents.
- Social Influence: Purchasing life insurance is often influenced by family tradition or the advice of peers. If parents maintained life insurance, the offspring are statistically more likely to view it as a standard financial responsibility.
- Digital Accessibility: By 2026, the rise of "InsurTech" has normalized the digital buying journey. Consumers increasingly expect to receive instant quotes, compare policy features via comparison aggregators, and complete the underwriting process with minimal human interaction.
The Stages of the Buying Journey
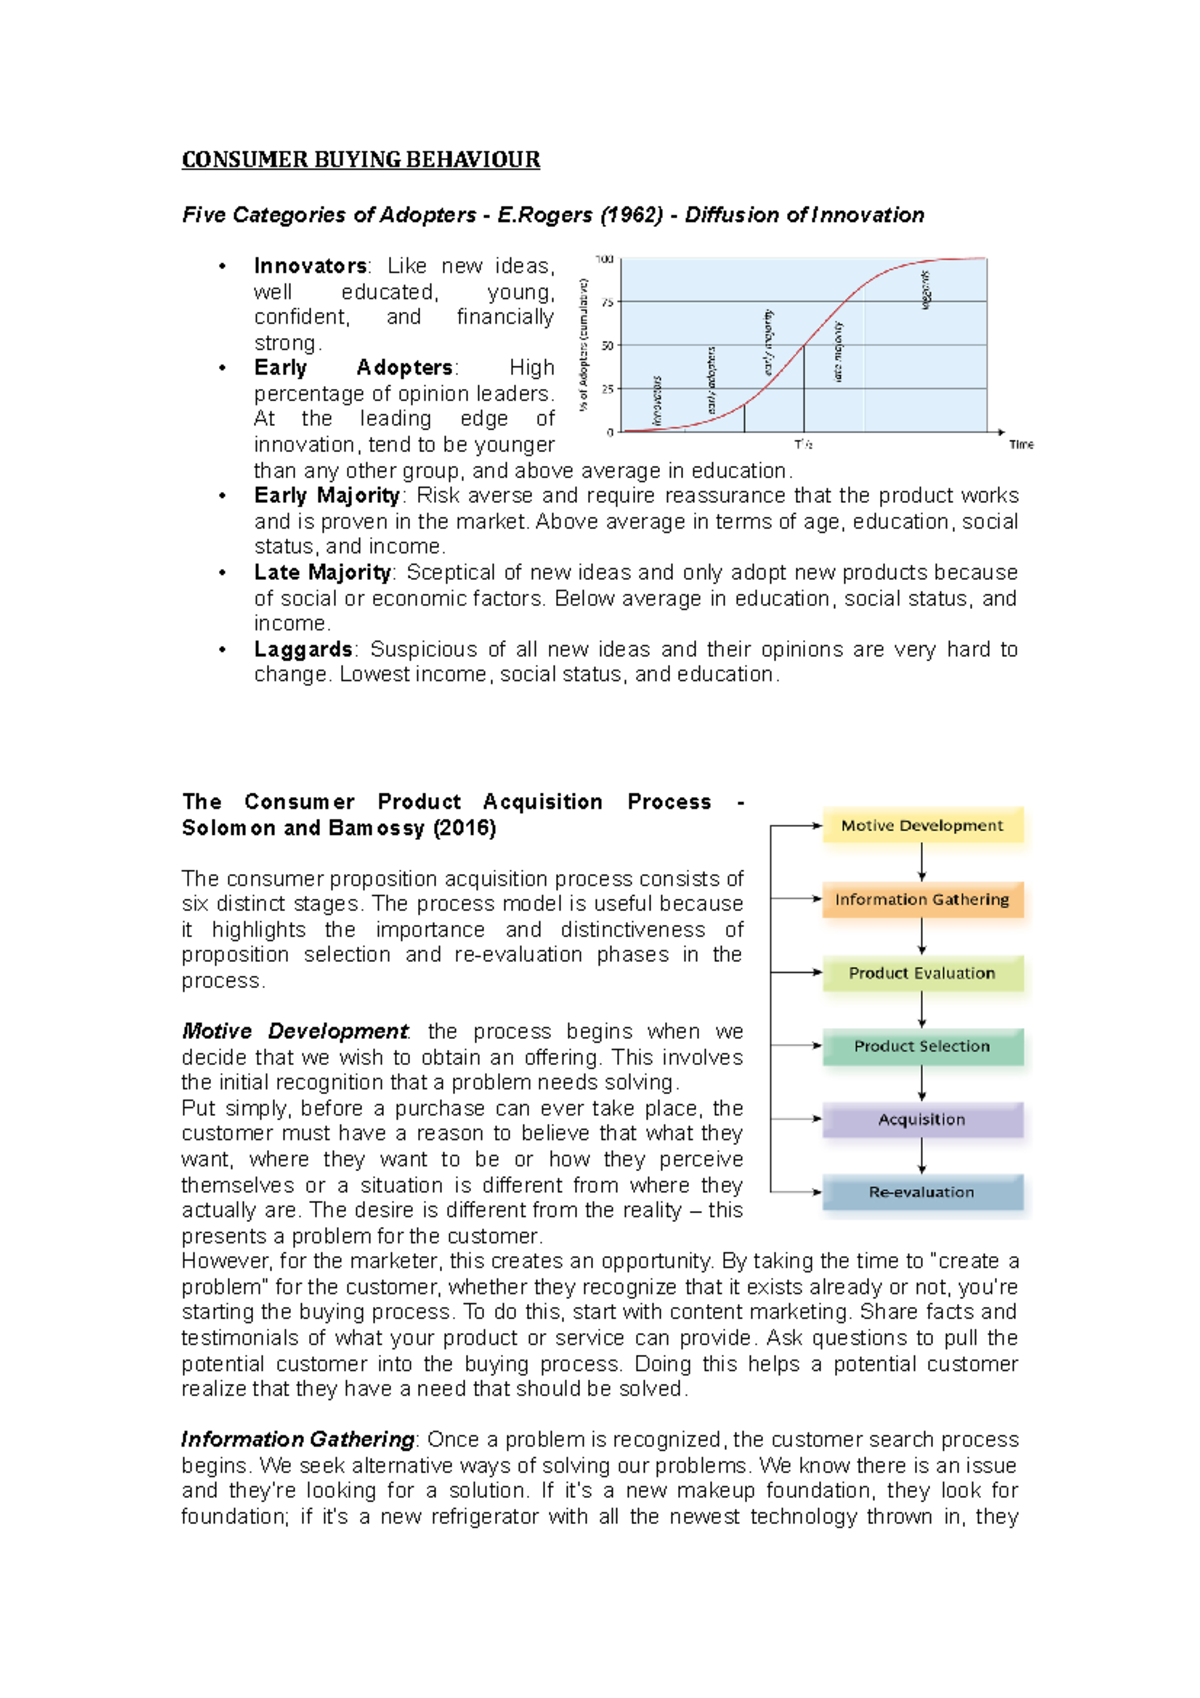
The transition from prospect to policyholder typically follows a standard sequence, though the duration of each phase varies significantly based on individual financial complexity.
- Awareness and Problem Identification: The consumer realizes a financial dependency exists. This is often sparked by external events or professional advice from a financial planner.
- Information Gathering: During this phase, consumers utilize search engines and comparison websites to learn about death benefits, premiums, and the distinction between policy types. They assess their "insurable interest" and calculate the necessary coverage amount.
- Evaluation of Alternatives: This involves comparing premiums, exclusions, and the financial strength ratings of insurance carriers. Consumers weigh the trade-offs between "buy term and invest the difference" versus bundled insurance-investment products.
- The Application and Underwriting Process: This is the most significant hurdle. It involves health assessments, medical exams, and financial disclosures. High friction in this stage—such as long wait times or invasive medical requirements—often leads to abandoned applications.
- Post-Purchase Behavior: Once the policy is in force, the consumer evaluates their decision during annual renewal periods. If the insurer provides poor customer service or lacks digital accessibility for updates, the consumer is more likely to let the policy lapse.
Comparative Overview of Life Insurance Products
Consumers must categorize products based on their objectives. The following table illustrates the common considerations for different policy types.
| Feature | Term Life Insurance | Whole Life Insurance | Universal Life Insurance |
|---|---|---|---|
| Primary Goal | Pure protection | Protection + Savings | Flexible protection + Cash value |
| Duration | Fixed (e.g., 10-30 years) | Lifetime (if paid) | Lifetime (if funded) |
| Premium Structure | Level (stays same) | Fixed/Higher | Variable |
| Complexity | Low | High | Very High |
| Target Audience | Young families, debt holders | Estate planners | High net-worth individuals |
The Impact of Technology on Buying Behavior
The integration of Artificial Intelligence (AI) and Big Data into the underwriting process has transformed consumer expectations. As of 2026, many insurers offer "accelerated underwriting," which uses data analytics to bypass traditional medical exams for low-risk applicants. This shift has removed a major friction point. When the buying process takes minutes rather than weeks, the conversion rate increases.
However, this reliance on technology introduces the "privacy paradox." While consumers demand speed and personalized premiums based on their health data (often gathered from wearable devices), they remain deeply concerned about the security of their personal information. The insurers that successfully capture market share are those that balance transparency regarding data usage with the efficiency of digital platforms.
Challenges and Barriers to Adoption
Despite the clear financial benefits of life insurance, penetration remains inconsistent. The primary barriers include:
- Perceived Cost: Many consumers overestimate the cost of term life insurance. Market studies frequently show that non-policyholders believe insurance is two to three times more expensive than it actually is.
- Complexity: The language used in insurance contracts is often filled with jargon that discourages the average consumer. The lack of simplification acts as a psychological barrier, causing potential buyers to procrastinate until "a better time."
- Inertia: Changing financial habits requires effort. Because the benefit of life insurance is realized in a distant, hypothetical future, consumers prioritize immediate expenses over long-term security.
- Misconceptions about Coverage: A common myth is that life insurance provided by an employer is sufficient. Consumers often fail to realize that employer-sponsored coverage is usually tied to the job and often provides insufficient death benefits to cover long-term family needs.
Strategies for Improved Engagement
To better understand and serve consumers, insurers and financial advisors must shift their focus toward educational engagement rather than aggressive sales. Strategies include:
- Financial Literacy Initiatives: Providing accessible calculators and educational content helps consumers demystify the coverage calculation process.
- Simplified Language: Simplifying policy riders and exclusions in communication materials can reduce anxiety and increase trust.
- Behavioral Nudges: Using timely prompts—such as reminders during major life events—can help move individuals from the "awareness" stage to the "action" stage.
- Human-Digital Hybrid Models: While many consumers prefer the ease of digital applications, they still desire access to human experts when dealing with complex estate planning or high-value policies.
Frequently Asked Questions
Why do most consumers delay buying life insurance? Consumers often delay because of the "optimism bias" and the perception that life insurance is an immediate expense rather than a long-term asset. Additionally, the complexity of navigating policy options and the fear of a rigorous medical exam often lead to procrastination.
Does age impact the buying journey? Yes. Younger buyers (20s–30s) are primarily driven by low cost and simplicity, often opting for term policies to cover short-term debts. Older buyers (50+) are typically concerned with legacy planning, tax efficiency, and wealth transfer, leading them toward permanent insurance products.
How do I know how much coverage is enough? A common rule of thumb is to secure coverage that is 7–10 times your annual income. However, a more accurate method involves a "needs analysis," which totals your debts, future educational costs for children, and the income required to maintain your family's lifestyle, then subtracts your existing liquid assets.
Are medical exams always required for life insurance? Not necessarily. In 2026, many insurance carriers offer "no-exam" or "accelerated" underwriting for healthy individuals applying for certain coverage amounts. These policies use public records, pharmaceutical databases, and AI models to assess risk instantly.
Is it better to buy life insurance through an agent or online? The choice depends on your needs. Online platforms are ideal for straightforward, low-cost term life insurance where speed is a priority. Working with an agent is generally better if you require a complex, permanent policy that involves tax planning, estate coordination, or specialized riders.
Practical Recommendations for Prospective Buyers
If you are currently evaluating your life insurance needs, begin by establishing a clear objective. Do you need protection for a specific term, such as the duration of your mortgage, or are you seeking a permanent solution for inheritance purposes?
Once your goal is set, perform a needs analysis to determine the death benefit amount. Prioritize carriers with high financial strength ratings from agencies like A.M. Best or S&P, and review their claims-paying history. If the process feels overwhelming, consult a fee-only financial advisor who does not work on commission; this ensures their advice is aligned with your best interests rather than the potential for a sales incentive. Taking these steps ensures that you move from a passive position to an active, informed decision-maker.
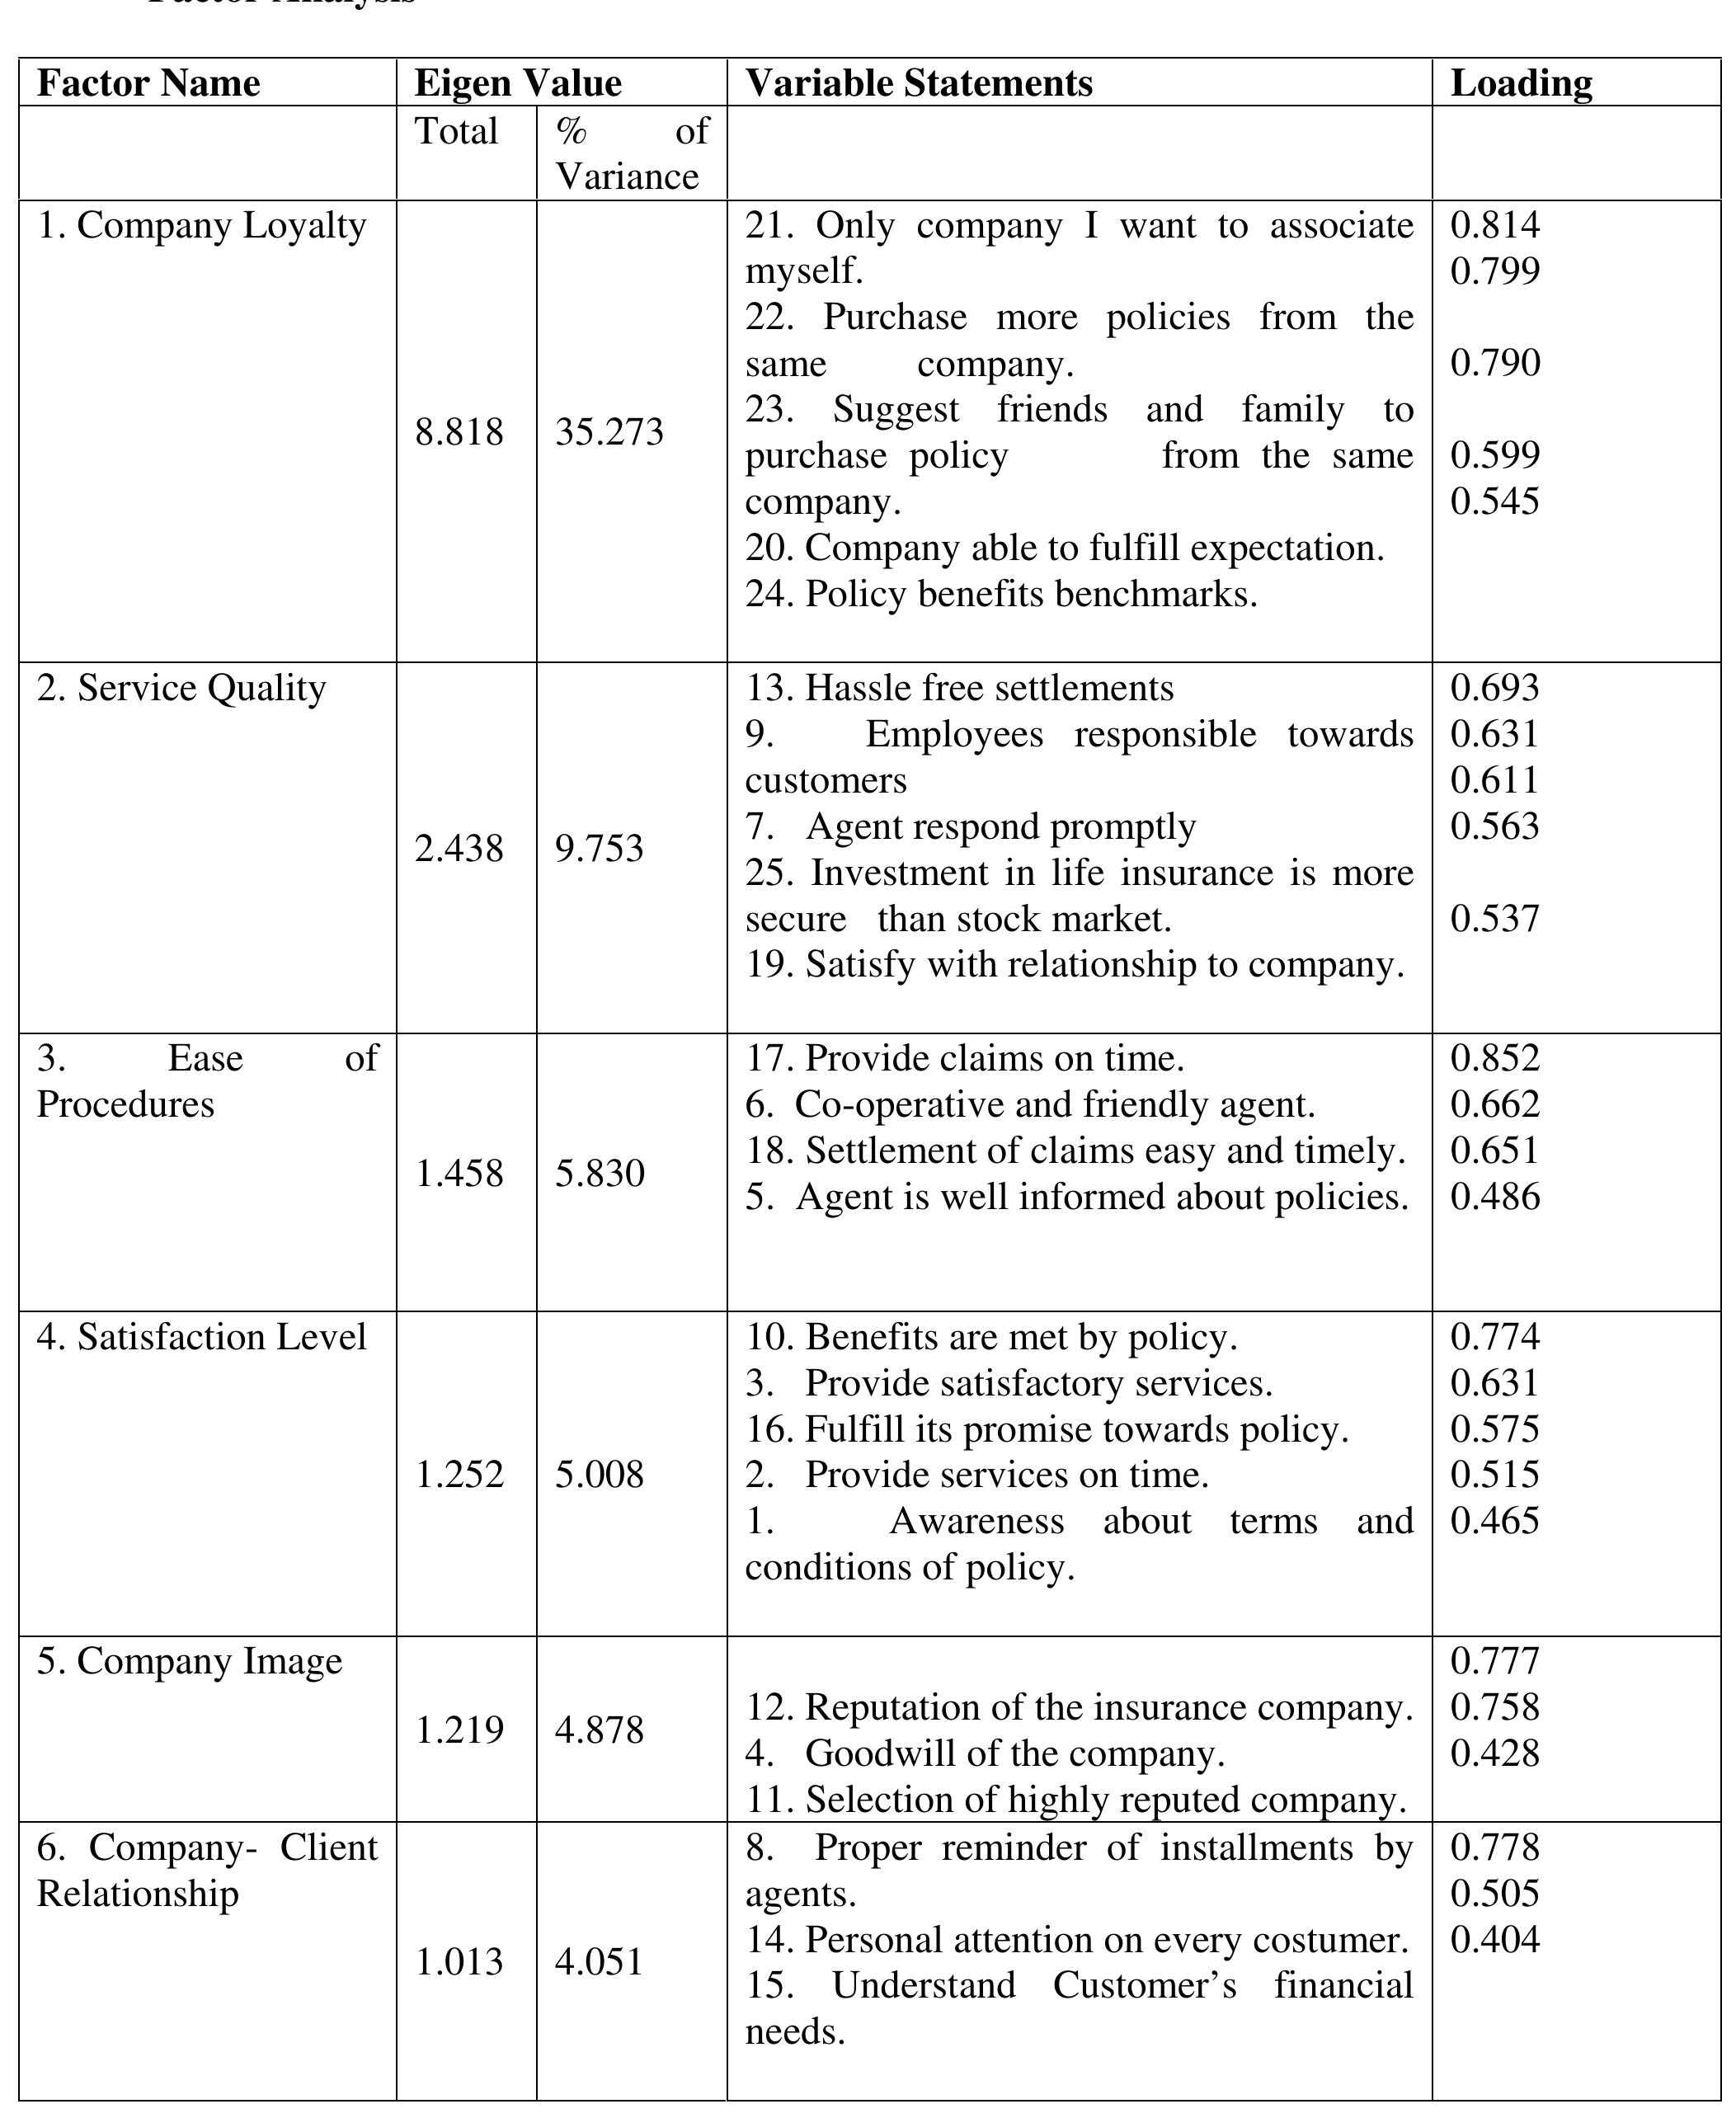
Image Gallery
Select an image to open it in a new tab.


Omar Farooq
EdTech Innovation and Virtual Pedagogy Journalist
