Land Loans for First Time Buyers: A Comprehensive Guide to Financing and Due Diligence
Securing land loans for first time buyers is a specialized financial process that differs significantly from traditional home mortgages. Because land lacks an existing structure to serve as collateral, lenders require higher down payments (often 20% to 50%), higher interest rates, and rigorous due diligence regarding zoning, utilities, and soil quality before approving a loan.
Entering the real estate market by purchasing vacant land is an ambitious and potentially rewarding strategy. For many first-time buyers in 2026, the dream of building a custom home or starting a small-scale homestead is more appealing than competing for overpriced, existing inventory. However, the path to land ownership is paved with complexities that traditional homebuyers rarely encounter. Unlike a residential mortgage, where the house itself provides immediate security for the lender, a land loan is viewed as a high-risk venture. If a borrower defaults on a vacant lot, the lender is left with a piece of dirt that may be difficult to liquidate.
Because of this inherent risk, the "first-time buyer" designation in the land market doesn't always carry the same perks as it does in the residential market—there are fewer 3% down payment programs and more stringent credit requirements. This guide explores the mechanisms of land financing, the critical stages of due diligence, and the specific programs available to help first-time buyers navigate the transition from raw earth to a titled property.
Disclaimer: The information provided in this article is for educational purposes only and does not constitute financial, legal, or professional real estate advice. Financing regulations and interest rates are subject to change based on jurisdictional laws and market conditions in 2026. Always consult with a qualified financial advisor or real estate attorney before committing to a land purchase.
Understanding the Three Categories of Land
Before applying for a loan, a first-time buyer must identify exactly what type of land they are purchasing. Lenders categorize land based on its level of development, and this classification directly dictates the loan terms, interest rates, and required down payment.
Raw Land
Raw land is completely undeveloped. It has no electricity, no water service, no sewers, and often no paved road access. For a lender, raw land represents the highest risk. Because there is no immediate way to live on or use the property, the "path to value" is long and uncertain. In 2026, most commercial banks require a down payment of 35% to 50% for raw land. Furthermore, the interest rates for raw land are typically the highest in the land-loan sector, reflecting the speculative nature of the investment.
Unimproved Land
Unimproved land is a step above raw land. It might have some basic infrastructure, such as a cleared site or a primitive access road, but it lacks essential utilities like a metered water hookup or an electrical transformer. While slightly more "ready" than raw land, it still requires significant capital investment to become buildable. Lenders often look for a well-defined plan for bringing utilities to the site before approving these loans. Down payments generally hover around 25% to 30%.
Improved Land
Improved land (also called a "build-ready" lot) is the gold standard for first-time buyers. These parcels have access to roads, water, electricity, and sometimes even sewer or fiber-optic internet lines. Because the most difficult development hurdles have already been cleared, lenders view improved land as lower risk. Consequently, first-time buyers may find more favorable terms here, with down payments as low as 15% to 20% and interest rates closer to standard construction loan levels.
Primary Financing Options for First-Time Land Buyers
Finding a lender for a land loan requires looking beyond the major national banks that dominate the residential mortgage market. Small, local institutions and government-backed programs are often the most viable routes for land acquisition.
Local Community Banks and Credit Unions
Local lenders are often the best resource for land loans because they understand the local geography and market value. A national bank may not see the value in a 5-acre plot in a rural county, but a local credit union likely has other members who have successfully built in that area. These institutions are more likely to offer "portfolio loans," which are kept on their own books rather than being sold to investors. This gives them more flexibility to approve a first-time buyer based on the specific merits of the land.
USDA Rural Development Loans
The U.S. Department of Agriculture (USDA) offers programs specifically designed for low-to-moderate-income buyers in rural areas. The USDA Section 523 and 524 loans are intended to help people acquire and develop building sites.
- Section 523 loans are for families who intend to build their own homes using the "Self-Help" method.
- Section 524 loans allow for the purchase of a site with the intent to build a home using a traditional contractor. These loans often have much lower interest rates and more accessible terms than private financing, making them a primary target for first-time buyers looking at rural acreage. You can find more information on eligibility at the USDA Rural Development official site.
SBA 504 Loans for Business Use
If a first-time buyer is purchasing land to start a business (such as a farm, a nursery, or a commercial workshop), the Small Business Administration (SBA) can be an invaluable resource. The SBA 504 loan program provides long-term, fixed-rate financing for major fixed assets, including land. This program is designed to promote economic development and usually requires only a 10% down payment from the borrower, which is significantly lower than commercial land loans. Detailed requirements are available via the SBA 504 loan portal.
Seller Financing
In a market where traditional bank financing is tight, many land sellers offer "owner financing" or a "land contract." In this scenario, the buyer makes payments directly to the seller rather than a bank. For a first-time buyer, this can be a way to bypass strict credit score requirements. However, it is vital to have a real estate attorney review the contract. Ensure the deed is properly recorded and that there are no "balloon payments" that could force you into a default situation in the future.
Critical Requirements for Loan Approval
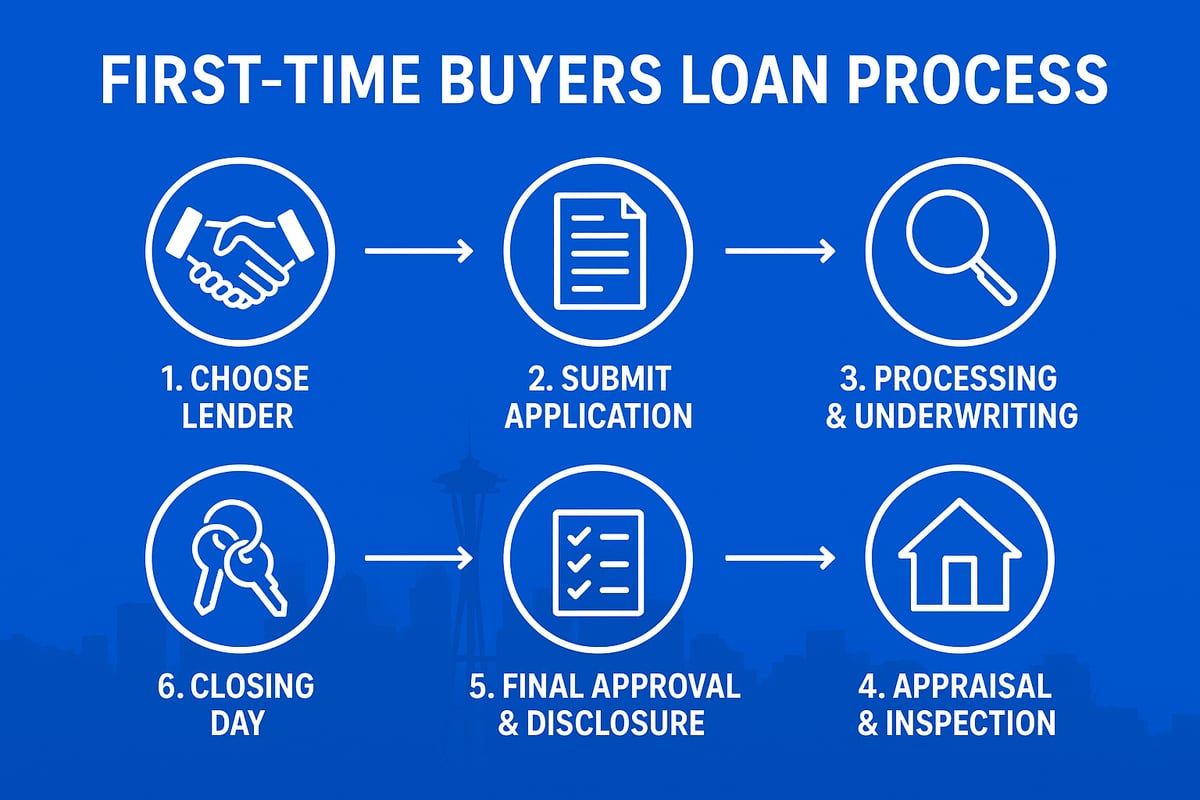
Applying for a land loan is more document-intensive than a standard mortgage. Lenders aren't just looking at your income; they are looking at the viability of the land itself.
- Credit Score and Debt-to-Income (DTI) Ratio: Most land lenders in 2026 look for a credit score of 700 or higher. Because the loan is high-risk, they want to see a history of impeccable financial management. Your DTI should ideally be below 36%, including the projected land loan payment.
- Land Survey: A professional survey is almost always mandatory. The lender needs to know the exact boundaries, any existing easements (rights for others to use your land), and potential encroachments from neighbors.
- Appraisal: Appraising vacant land is difficult because there are fewer "comps" (comparable sales) than in a suburban neighborhood. The appraiser will look at the land’s topography, location, and the recent sale prices of similar parcels.
- Zoning and Land Use Documentation: You must prove that the land is zoned for your intended use. If you plan to build a house, but the land is zoned "Exclusive Farm Use" or "Industrial," the lender will deny the loan immediately.
- Environmental Reports: In some regions, lenders require a Phase I Environmental Site Assessment to ensure the land isn't contaminated by previous industrial use or hazardous waste.
The Due Diligence Checklist: Protecting Your Investment
For a first-time buyer, the "due diligence" period is the most critical phase of the purchase. This is the window of time (usually 30 to 60 days) where you can investigate the land and back out of the deal if problems are found.
The Perc Test (Soil Evaluation)
If the land does not have access to a municipal sewer system, you will need to install a septic system. A "percolation test" (perc test) determines how quickly water drains through the soil. If the soil is too rocky or has too much clay, it may not "perc," meaning you cannot install a traditional septic system. Without a septic system, you cannot build a home. For a first-time buyer, a failed perc test is a deal-breaker.
Utility Access and Costs
Never assume that because there is a power line on the street, you can easily tap into it. In 2026, the cost of "dropping" power to a new site can range from $2,000 to over $20,000 depending on the distance from the nearest transformer. Similarly, if you need a well, check the neighboring properties' well depths. Digging a 500-foot well is significantly more expensive than a 100-foot well.
Easements and Rights-of-Way
An easement is a legal right for someone else to use part of your property. Common easements include utility companies running lines across your land or a neighbor using a driveway that crosses your corner. Some easements can severely limit where you are allowed to build your house.
Comparison of Land Loan Features (2026 Market Standards)
| Feature | Raw Land Loan | Improved Land Loan | USDA Site Loan |
|---|---|---|---|
| Typical Down Payment | 35% – 50% | 15% – 25% | 0% – 10% (Income dependent) |
| Interest Rates | High (Prime + 2-4%) | Moderate (Prime + 1-2%) | Low (Subsidized) |
| Loan Term | 5 – 10 Years | 10 – 20 Years | Up to 33 Years |
| Ease of Approval | Difficult | Moderate | Moderate (Strict Eligibility) |
| Collateral Value | Low | High | High (Targeted Areas) |
Transitioning from a Land Loan to a Construction Loan
Most first-time buyers do not plan to hold vacant land forever; they want to build. This transition is where financial strategy becomes vital.
One popular option is the Construction-to-Permanent Loan. This "all-in-one" loan covers the purchase of the land and the cost of building the home. During the construction phase, you typically pay only the interest. Once the home is finished, the loan converts into a standard 15- or 30-year mortgage.
If you already own the land through a land loan, you can often use the equity you’ve built in the land as your down payment for the construction loan. For example, if the land is worth $100,000 and you owe $40,000, that $60,000 in equity serves as a substantial "down payment" toward the construction project, often eliminating the need for further cash out of pocket.
Common Pitfalls for First-Time Land Buyers
- Underestimating Clearing Costs: Removing trees, grading a slope, and building a 200-foot driveway can cost tens of thousands of dollars. These "soft costs" are often not fully covered by land loans.
- Ignoring CC&Rs: Even if land is in a rural area, it may be part of a Homeowners Association (HOA) or have Covenants, Conditions, and Restrictions (CC&Rs). These might dictate the minimum square footage of your home or prohibit you from living in an RV while you build.
- Assuming Mobile Home Eligibility: Not all land is zoned for manufactured or mobile homes. Some municipalities have strict "stick-built only" ordinances.
Frequently Asked Questions
Can I get a land loan with a 580 credit score?
It is extremely difficult to secure a land loan with a 580 credit score in 2026. Because land is considered a high-risk asset, most lenders require a minimum of 680 to 700. Buyers with lower scores may need to look into seller financing or wait until they can improve their credit profile to meet traditional lending standards.
How much down payment do I really need?
For improved land, you should expect to put down at least 20%. For raw land, be prepared for 35% to 50%. While some government programs like the USDA offer lower down payments, they have strict geographic and income eligibility requirements that not all buyers will meet.
Is interest on a land loan tax-deductible?
Generally, interest on a loan for vacant land is not deductible as mortgage interest unless the land is being used for investment purposes (where it may be a business expense) or if you begin construction on a qualified residence within a specific timeframe. Tax laws in 2026 are complex, so it is essential to consult a tax professional regarding your specific situation.
Can I live in a trailer on the land while I pay off the loan?
This depends entirely on local zoning laws and the terms of your loan. Many lenders and local ordinances prohibit "camping" or living in temporary structures on the land before a permanent residence is established. Always check with the county planning department before assuming you can live on-site during the payoff period.
What is a "Balloon Payment" in land financing?
A balloon payment is a large, lump-sum payment due at the end of a loan term. Many land loans are structured with a 5- or 10-year term but are amortized over 20 years. This keeps monthly payments low, but you must pay the remaining balance in full at the end of the term. First-time buyers must have a plan to refinance or pay off the balloon when it comes due.
Practical Next Steps for Buyers
If you are ready to pursue a land loan, your first action should be to secure a "pre-qualification" from a local community bank or credit union that specializes in agricultural or land lending. Unlike a home pre-approval, this will be a conversation about your liquid assets and your specific plans for the property.
Simultaneously, build your "land team," which should include a real estate agent experienced in vacant land (not just residential houses) and a local surveyor. Research the zoning of your target area using the county's online GIS (Geographic Information System) maps to ensure your vision for the property is legally permissible. By focusing on improved land and leveraging local lending relationships, first-time buyers can successfully navigate the hurdles of land ownership in 2026.
Image Gallery
Select an image to open it in a new tab.
Lars Thomsen
Global Labor Markets and Economic Strategy Editor
