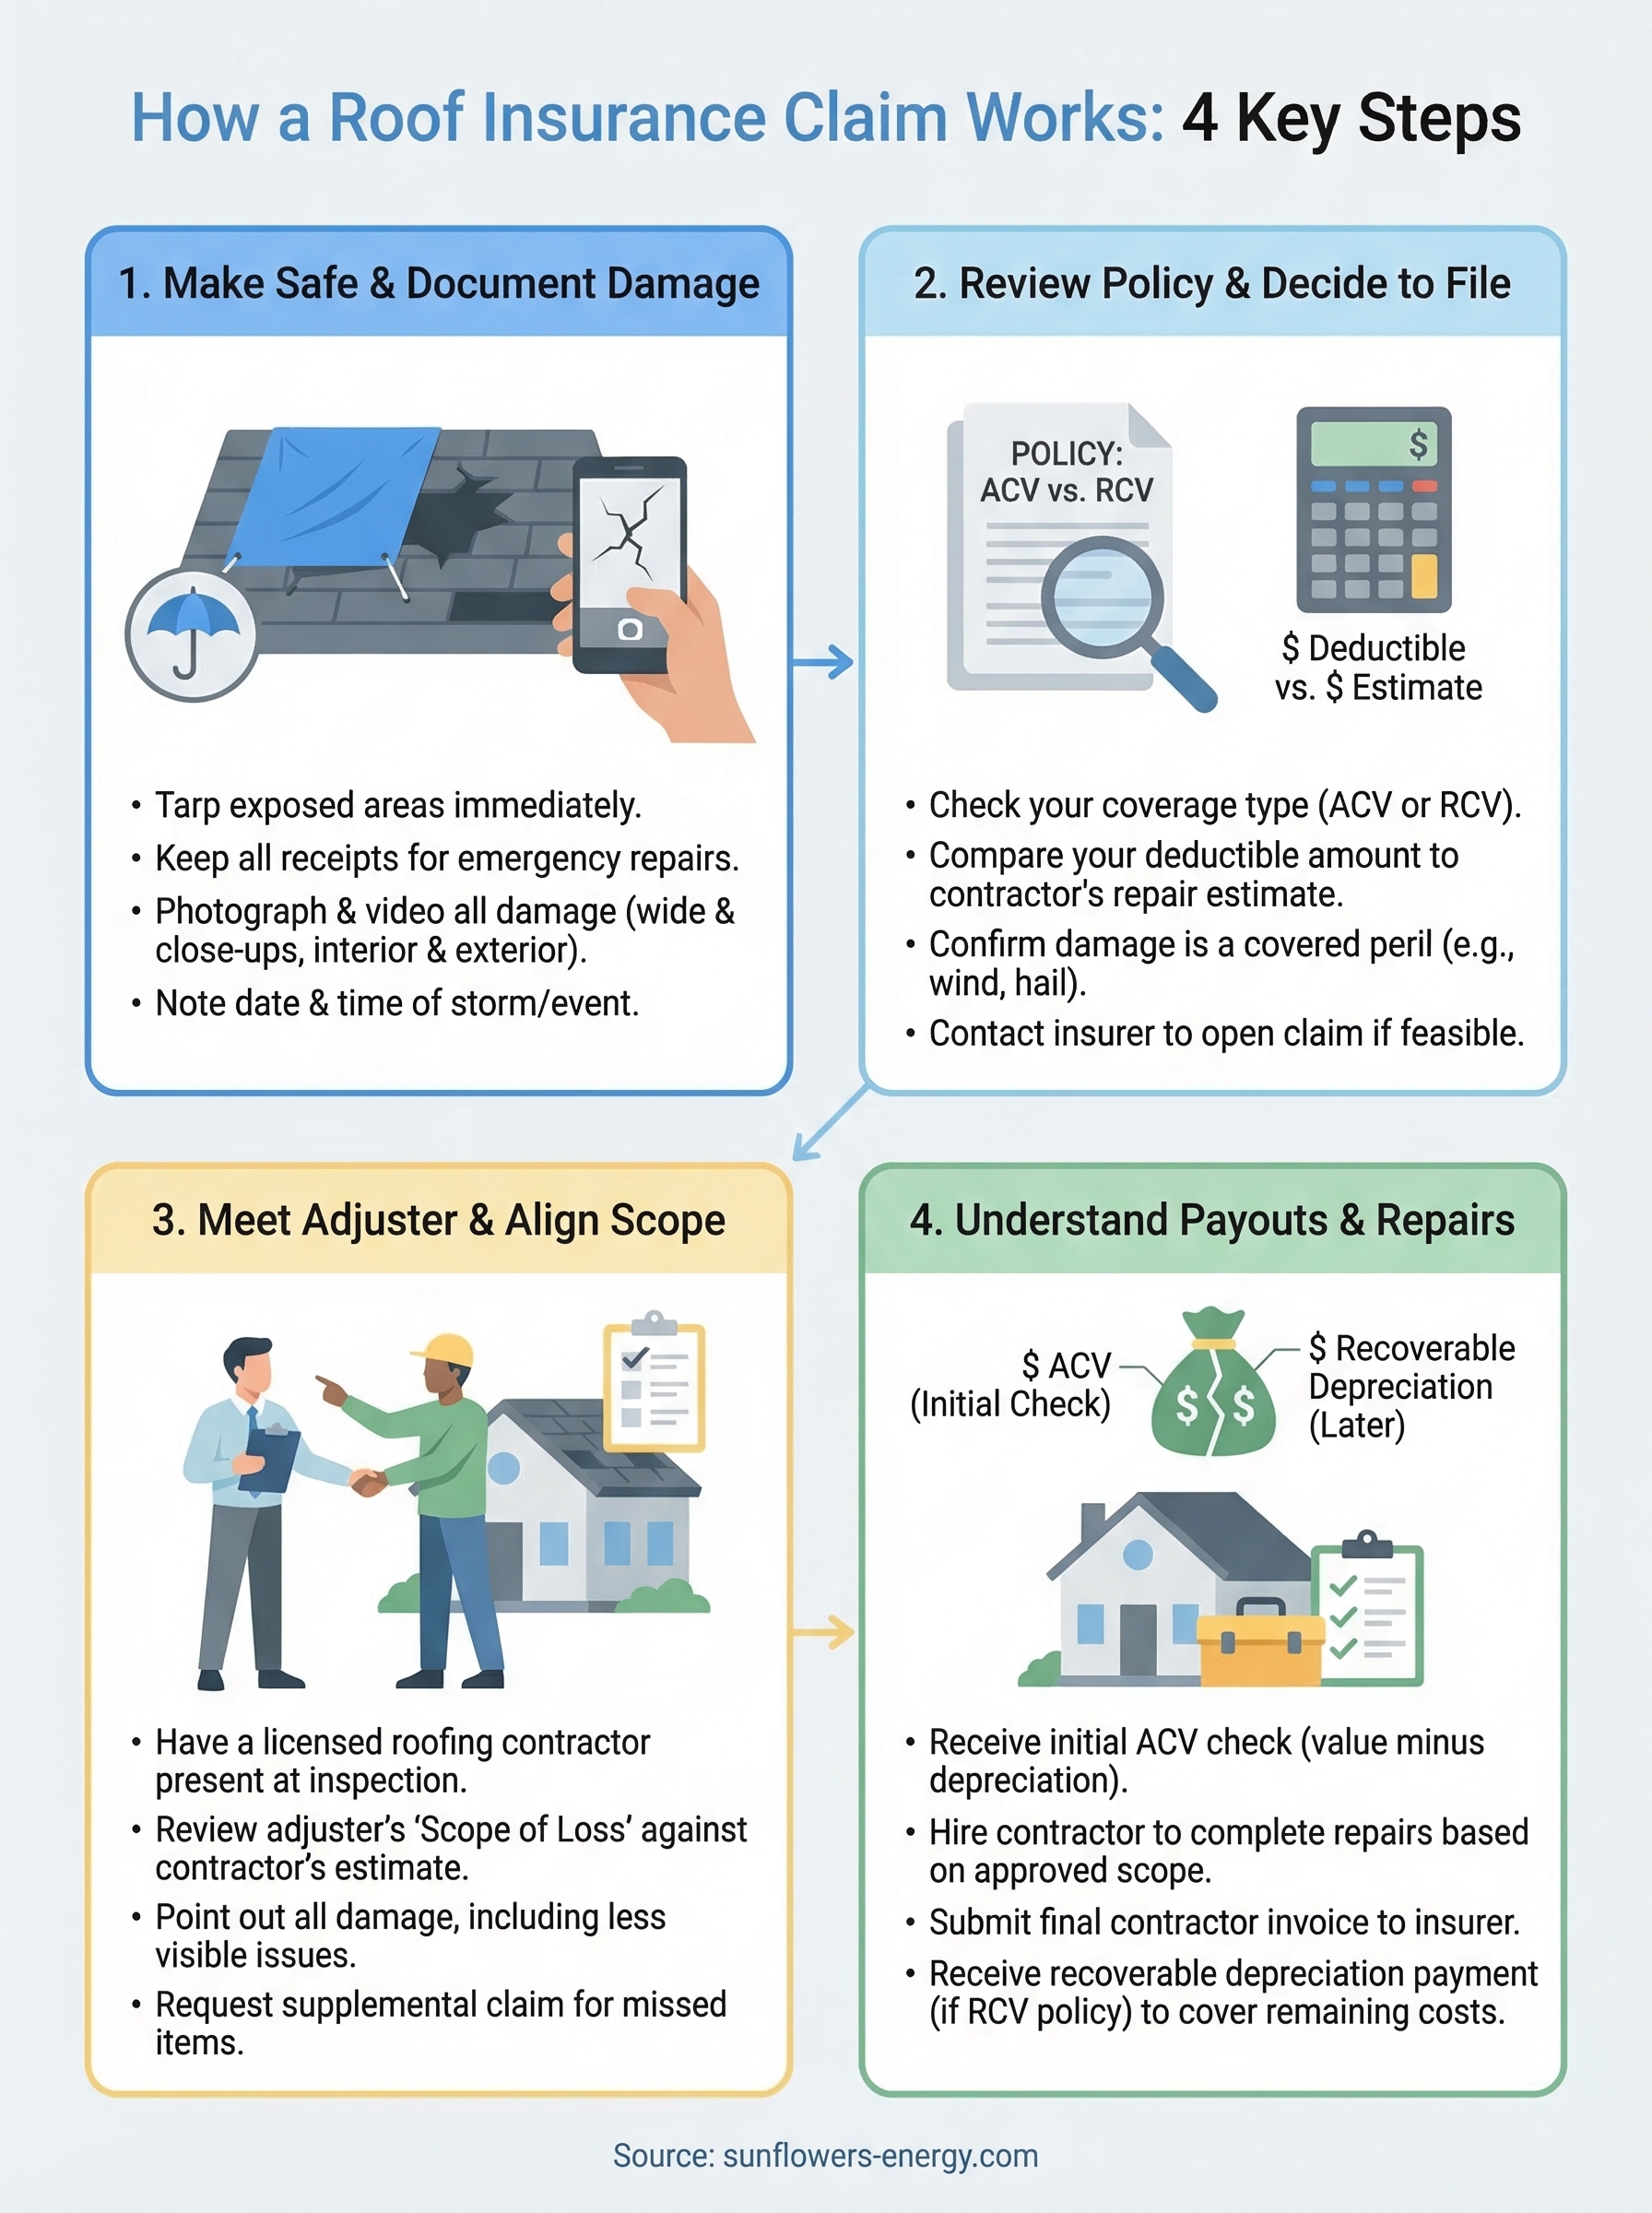
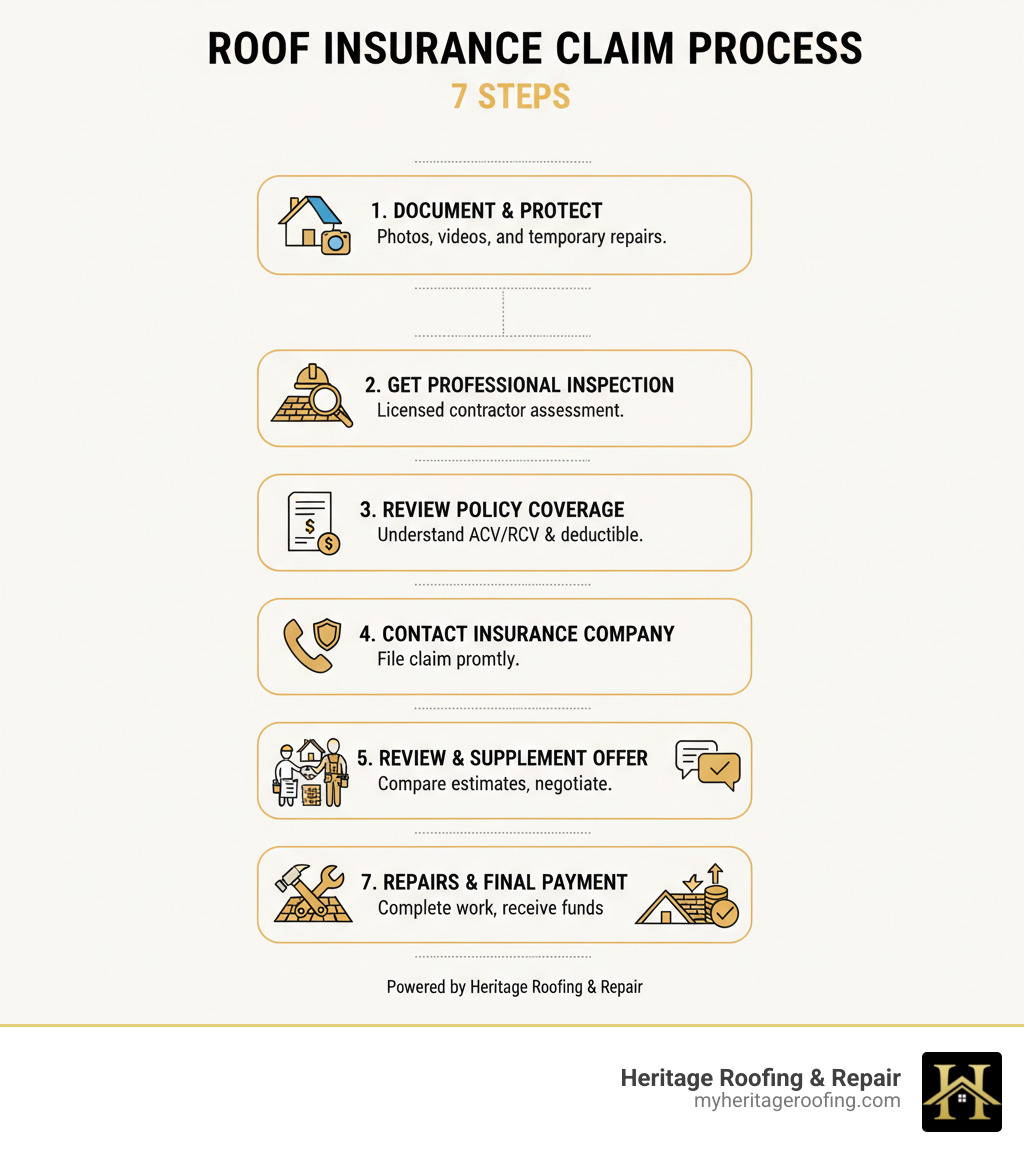
Filing a roof insurance claim involves documenting storm or accidental damage, reviewing your policy’s specific coverage limits—such as Replacement Cost Value (RCV) versus Actual Cash Value (ACV)—and submitting a formal request to your provider. By obtaining a professional contractor's assessment before the adjuster arrives, you ensure all structural issues are accurately identified for a fair settlement.
Navigating the complexities of property insurance can be daunting, especially following a significant weather event. As of 2026, the cost of roofing materials and skilled labor has reached new plateaus, making the financial stakes of a successful claim higher than ever. Whether you are dealing with hail impact, wind-driven rain, or fallen debris, understanding the systematic approach to filing a claim is essential for protecting your home’s value and your personal finances. This guide provides an exhaustive roadmap for homeowners, from initial damage detection to the final inspection of the completed repair.
Understanding Your Insurance Policy Coverage
Before picking up the phone to call your insurance agent, you must understand the contractual language of your homeowners' insurance policy. Not all roof damage is treated equally, and the type of coverage you have will dictate your out-of-pocket expenses.
Replacement Cost Value (RCV) vs. Actual Cash Value (ACV)
The most critical distinction in a roofing claim is the method of valuation. Most modern policies are either RCV or ACV.
- Replacement Cost Value (RCV): This is the more comprehensive option. If your roof is damaged, the insurance company pays the "replacement cost" to install a new roof of similar quality at current market prices. You are only responsible for your deductible. The insurer usually pays in two installments: an initial check for the depreciated value and a second "recoverable depreciation" check once the work is completed and invoiced.
- Actual Cash Value (ACV): Under an ACV policy, the insurer pays only what the roof is worth at the time of the loss. This means they subtract depreciation based on the age and condition of the roof. If you have a 20-year-old roof with a 25-year lifespan, the payout may only cover a small fraction of a new roof’s cost, leaving you to fund the remainder.
Covered Perils vs. Exclusions
Insurance is designed to cover "sudden and accidental" damage. Common covered perils include:
- Hail: Impact damage that bruises the shingle mat or knocks off protective granules.
- Wind: High-velocity winds that lift, crease, or blow shingles off the roof.
- Falling Objects: Trees or branches falling during a storm.
Conversely, "wear and tear" is almost never covered. If your roof is leaking simply because it is 30 years old and the shingles have reached the end of their natural life, the claim will likely be denied. Neglect, such as failing to clear gutters or ignoring minor leaks that lead to structural rot, can also disqualify a claim.
Immediate Steps Following Roof Damage
Timing is essential. Most insurance policies have a "statute of limitations" for filing a claim, often ranging from 365 days to two years from the date of the loss. However, acting immediately prevents secondary damage, such as mold or interior ceiling collapse, which the insurer might refuse to cover if you were negligent in mitigating the loss.
1. Document the Date and Type of Event
Note the exact date and time the damage occurred. If it was a hail storm, search for local weather reports or use apps that track hail swaths. This "date of loss" is the anchor for your entire claim.
2. Visual Inspection and Photo Documentation
From the ground, use a ladder or binoculars to look for visible signs of damage. Do not walk on a damaged roof yourself, as this is a safety hazard and can inadvertently cause more damage. Look for:
- Missing or torn shingles.
- Dented gutters, downspouts, or soft metal vents (signs of hail).
- Water spots on interior ceilings or in the attic.
- Granules accumulating at the base of downspouts.
3. Emergency Mitigation
Insurance policies require homeowners to take reasonable steps to prevent further damage. If there is a gaping hole in the roof, you are expected to have it professionally tarped. Keep the receipts for these emergency repairs; they are typically reimbursable as part of the claim.

The Role of a Professional Roofing Contractor
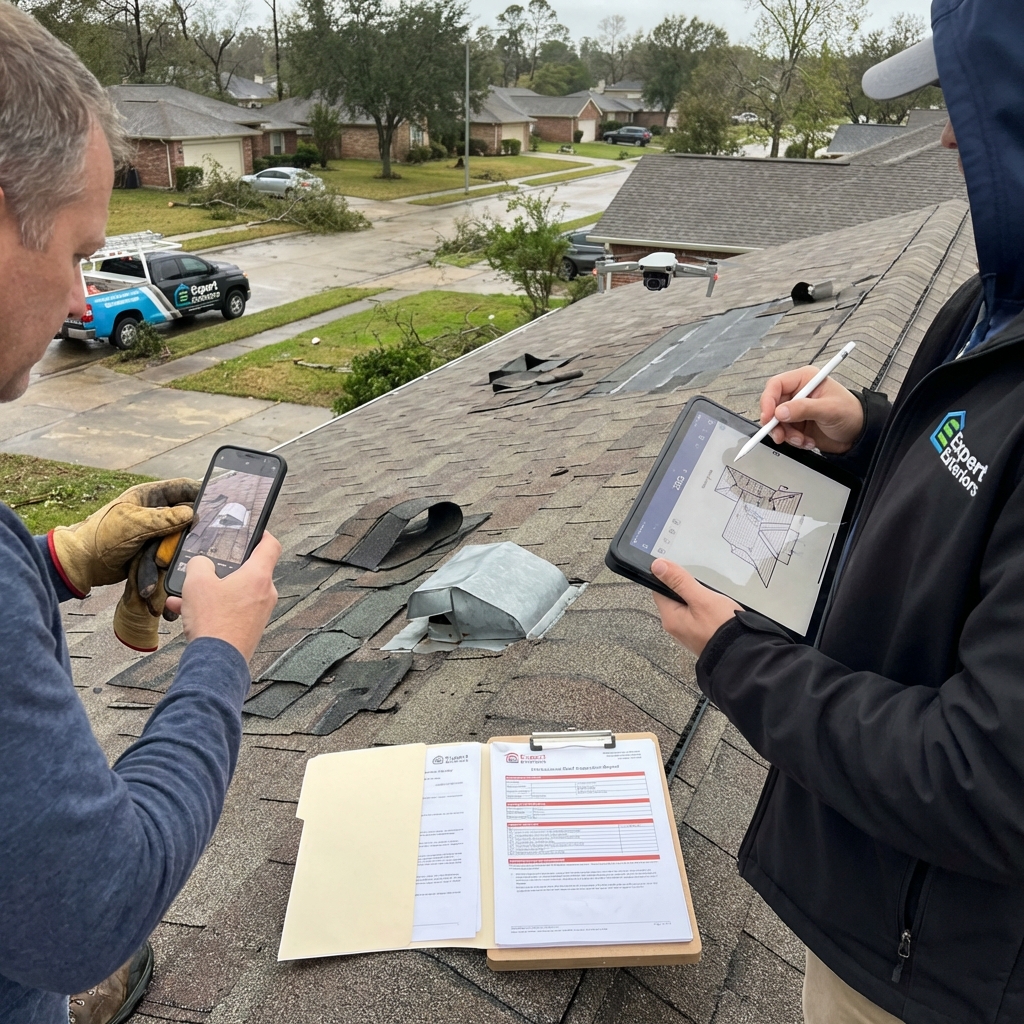
While you can file a claim yourself, involving a reputable roofing contractor early in the process is highly recommended. A contractor who specializes in "insurance restoration" understands the technical language adjusters use and can provide a more detailed estimate than a general home inspector.
Why the Contractor Should Visit Before the Adjuster
A contractor acts as your advocate. They will perform a "test square" (a 10' x 10' area) to count the number of hail strikes or wind-damaged shingles. Having a detailed, line-itemed estimate (often using industry-standard software like Xactimate) allows you to compare the insurer’s offer against real-world labor and material costs.
Vetting Your Contractor
In 2026, "storm chasers"—unlicensed contractors who follow weather patterns to find work—remain a significant risk. Ensure your contractor:
- Is locally licensed and bonded.
- Carries workers' compensation and general liability insurance.
- Can provide references from the past 12 months.
- Does not pressure you to sign a "contingency agreement" before you have even seen your policy or spoken to an adjuster.
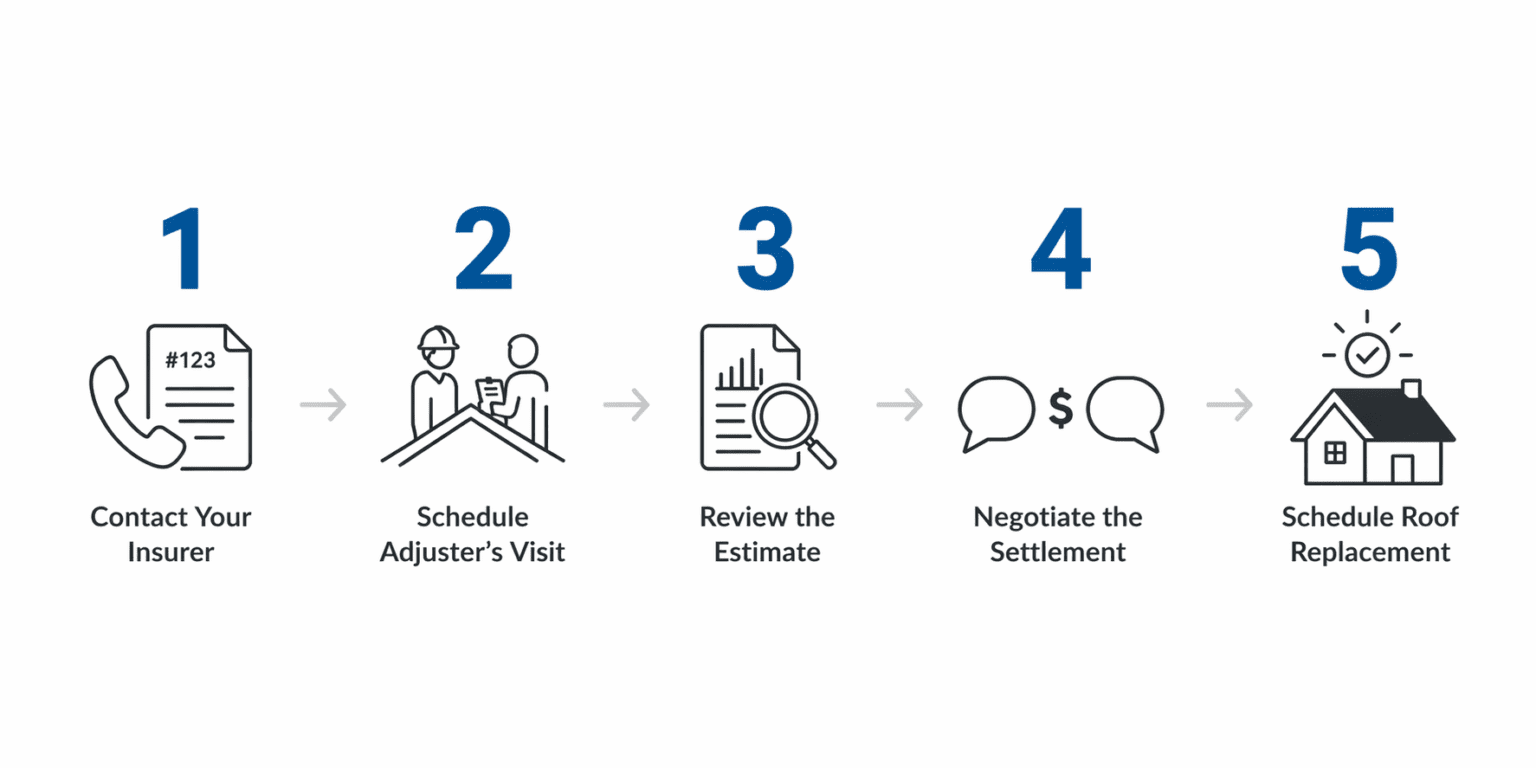
The Step-by-Step Filing Process
Once you have confirmed there is significant damage and you have your documentation ready, follow these steps to initiate the formal claim.
Step 1: Contact Your Insurance Company
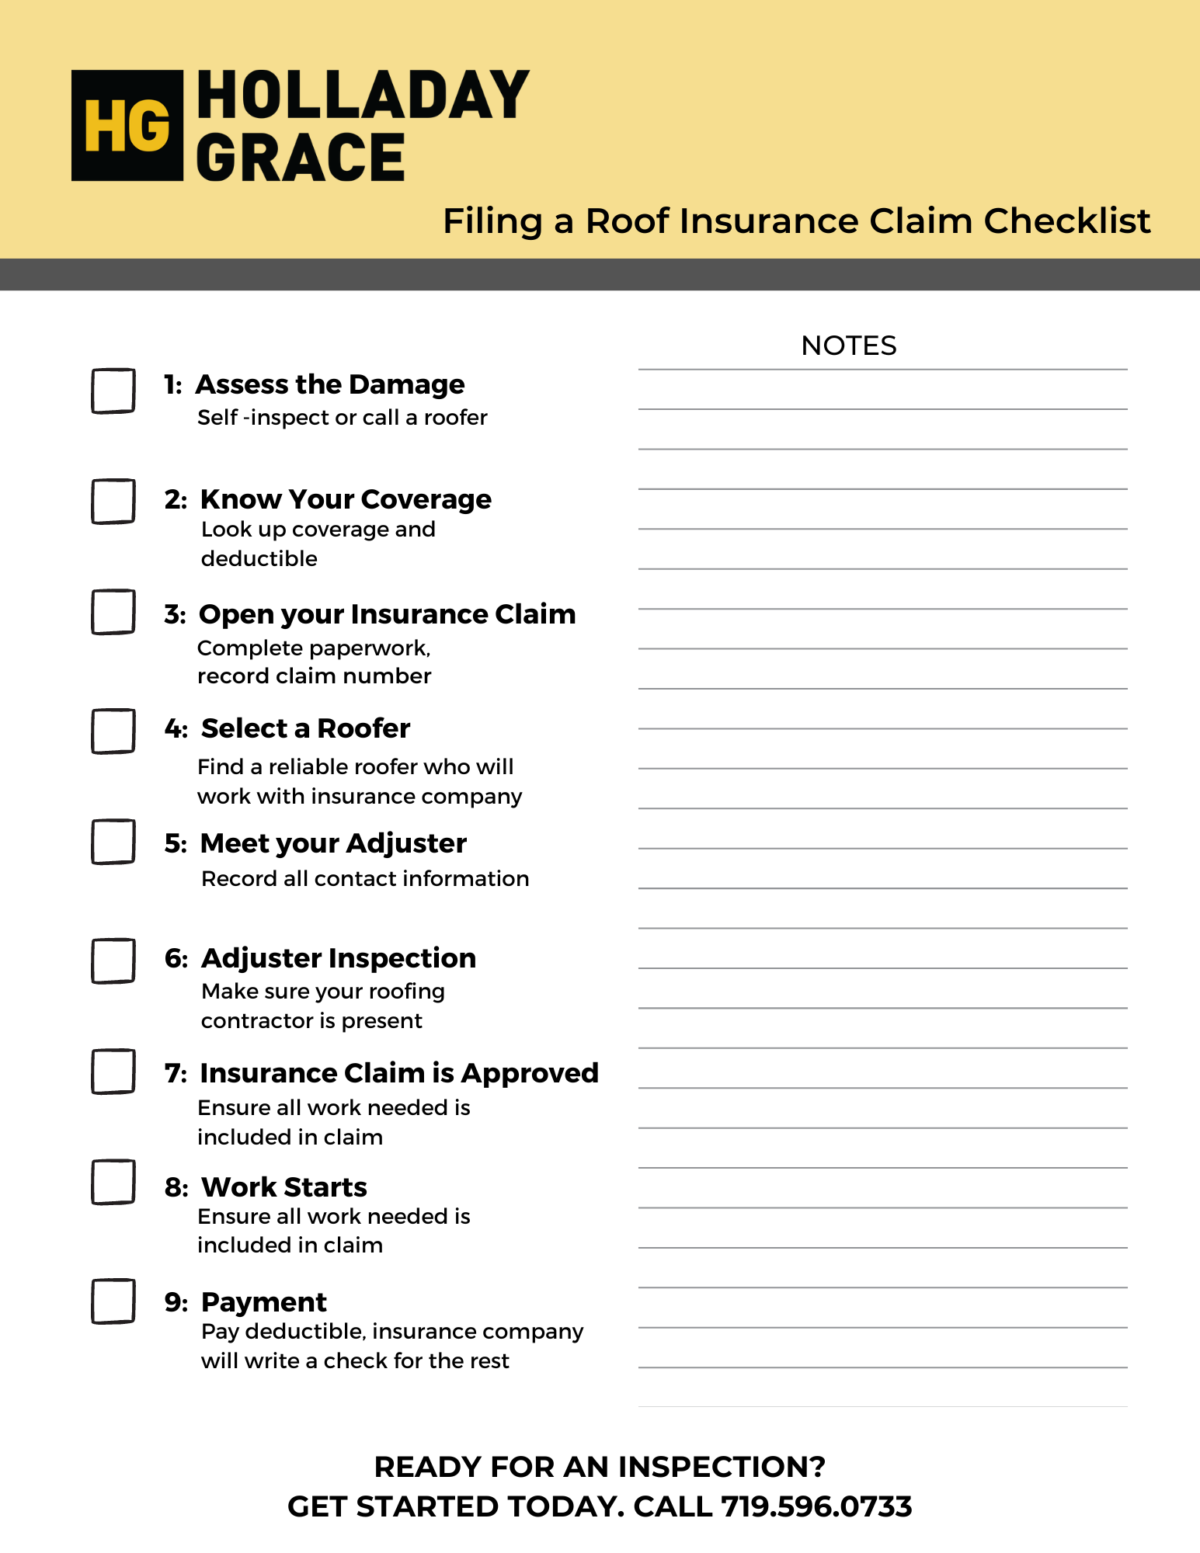
Call the claims department or use the company’s mobile app. You will need your policy number and the date of loss. Briefly describe the damage. You will be assigned a claim number; keep this in a dedicated folder (physical or digital) along with all subsequent correspondence.
Step 2: The Insurance Adjuster Meeting
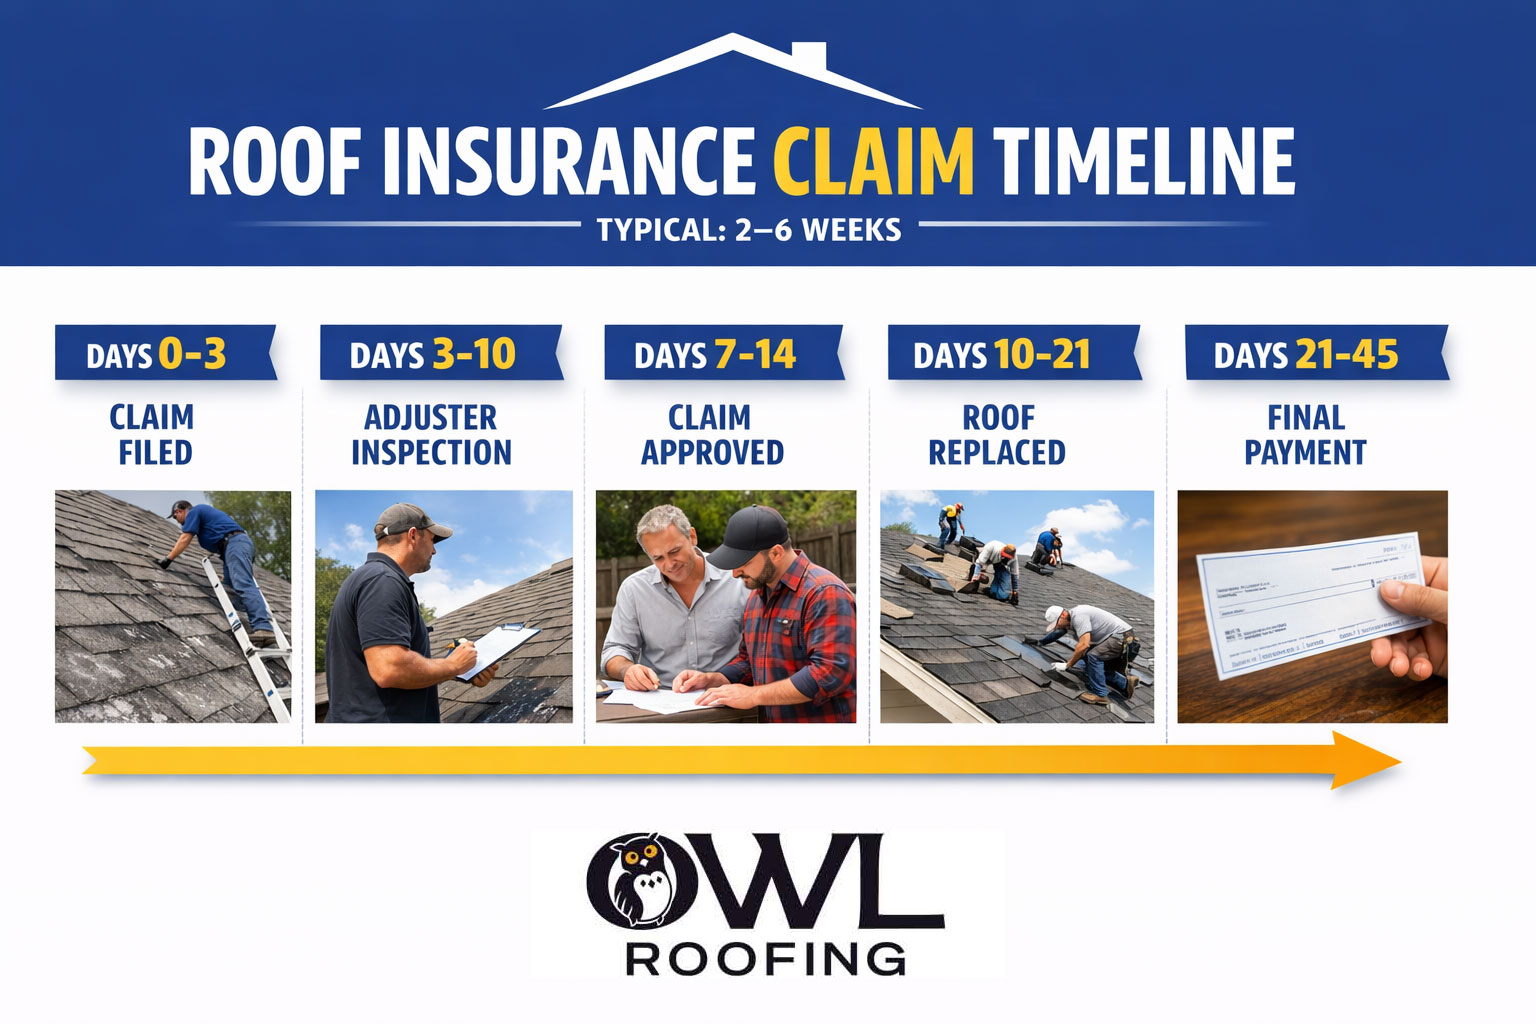
The insurance company will send an adjuster to inspect the property. This typically happens within 48 to 72 hours for major catastrophes, though it may take longer during widespread regional storms. Invite your roofing contractor to be present during this inspection. The contractor can point out subtle damage the adjuster might overlook, such as damaged flashing or chimney crickets.
Step 3: Reviewing the Claim Summary (Estimate)
After the inspection, the adjuster will generate a report detailing what they are willing to pay for. This report includes:
- Replacement Cost Value (RCV): Total cost to repair/replace.
- Depreciation: The value lost due to age.
- Deductible: The portion you pay out of pocket.
- Actual Cash Value (ACV) Payment: The initial check you receive (RCV minus Depreciation and Deductible).
Step 4: The Supplemental Claim Process
It is very common for the initial insurance estimate to be lower than the contractor’s estimate. This is often because the adjuster missed a code-required item (like ice and water shield) or used outdated material pricing. Your contractor can submit a "supplement" to the insurance company—a request for additional funds backed by photos and local building codes.
| Claim Component | Description | Responsibility |
|---|---|---|
| Deductible | The initial amount the homeowner must pay. | Homeowner |
| First Check (ACV) | Initial payment for the "current value" of the damaged area. | Insurer |
| Depreciation | The value held back until the work is completed. | Insurer (if RCV policy) |
| Supplements | Extra funds for unforeseen damage or code upgrades. | Insurer |
| Final Check | The "Recoverable Depreciation" paid after completion. | Insurer |
Financial Management: Handling the Checks
Managing the finances of a roof claim requires care, especially if you have a mortgage. In most cases, the insurance check will be made out to both you and your mortgage company.
The Mortgage Company’s Involvement
Because the home is collateral for the loan, the mortgage company has a vested interest in ensuring the repairs are actually made. You will need to send the check to their loss draft department for endorsement. They may release the funds in stages: a portion to start the job, and the remainder after they have inspected the finished roof.
The "Deductible" Warning
In some jurisdictions, it is illegal for a contractor to "waive" or "absorb" your insurance deductible. This is considered insurance fraud. As the homeowner, you are legally and contractually obligated to pay your deductible to the contractor. If a contractor offers to cover your deductible, it is a significant red flag that they may be cutting corners on materials or labor.
Common Reasons for Claim Denial
Not every claim results in a new roof. Understanding the reasons for denial can help you prepare for a potential appeal.
- Partial Repair vs. Full Replacement: If only 5% of your shingles are damaged, the insurer may only pay for a "patch" rather than a full replacement. However, if the shingles are no longer manufactured and cannot be matched, many states have "matching laws" that may force a full replacement.
- Pre-existing Damage: If a previous inspection noted damage that was never repaired, the insurer will likely deny a new claim for the same area.
- Manufacturing Defects: If your shingles are failing because of a factory defect rather than a storm, the insurer will direct you to file a warranty claim with the shingle manufacturer (e.g., GAF, Owens Corning).
- Improper Installation: If the roof leaked because it wasn't installed to code initially, the insurance company might argue that the failure was not caused by a covered peril.
When to Hire a Public Adjuster or Legal Counsel
If you feel your claim has been unfairly denied or significantly underpaid, and your contractor has exhausted the supplemental process, you have other options.
- Public Adjusters: These are independent professionals you hire to represent your interests. They charge a percentage of the final settlement (typically 10-15%). They are often more aggressive in negotiating with the insurance company than a contractor can be.
- Appraisal Clause: Most policies contain an appraisal clause. If you and the insurer disagree on the amount of the loss, both parties hire an independent appraiser. These two appraisers then choose an "umpire." A decision by any two of the three is binding.
- Insurance Attorneys: If the dispute is about coverage (whether the damage is covered at all) rather than the amount, you may need a lawyer specializing in first-party property claims.
Summary Checklist for Homeowners
To ensure a smooth process in 2026, follow this abbreviated checklist:
- Verify Coverage: Confirm if you have RCV or ACV coverage.
- Identify Date of Loss: Check weather logs for confirmed storm activity.
- Mitigate Damage: Tarp leaks and keep all receipts.
- Get a Professional Opinion: Have a contractor inspect the roof before the insurance company.
- File Promptly: Contact the claims department immediately.
- Organize Paperwork: Store your claim number, adjuster's contact info, and photos in one place.
- Manage Funds: Coordinate with your mortgage company for check endorsements.
Frequently Asked Questions
Will my insurance premiums go up if I file a roof claim?
Generally, insurance companies cannot raise your individual rates solely because of an "Act of God" claim, such as hail or wind. However, if your entire geographic area is hit by a major storm, the insurance company may raise rates for the entire zip code or region to reflect the increased risk profile.
How long does the entire roofing claim process take?
The timeline varies depending on the severity of the storm and the responsiveness of your insurer. Typically, the process takes between 30 and 90 days. The actual roof installation usually takes only 1–2 days, but the administrative tasks—adjuster meetings, mortgage endorsements, and supplemental approvals—make up the bulk of the duration.
Can I choose my own roofing contractor?
Yes. You are not required to use a "preferred vendor" suggested by your insurance company. You have the right to hire any licensed contractor you trust. In fact, many homeowners prefer independent contractors because they work for the homeowner, not the insurance company.
What if my roof is old but has storm damage?
If you have an RCV policy, the age of the roof usually doesn't prevent a full replacement, provided there is clear storm damage. However, if the roof is in extremely poor condition, the adjuster may argue that the leaks were caused by "deterioration" rather than the storm. This is where having a contractor's pre-inspection report is vital.
Can I file a claim for a roof that isn't leaking yet?
Yes. Hail damage, for example, often does not cause immediate leaks. Instead, it knocks off the protective granules, exposing the asphalt layer to UV rays. This causes the shingles to degrade rapidly, leading to leaks months or even years later. It is better to file when the damage is fresh and the storm event is easily verifiable.
What happens if the insurance company only approves a partial repair?
If the shingles are "brittle" (meaning they crack when lifted for repair), your contractor should perform a "brittleness test" and document it with video. If the roof cannot be repaired without causing further damage, most insurers will move toward a full replacement. Additionally, check your state's matching regulations regarding "uniformity and appearance."
Next Steps: Practical Recommendation
Your immediate next action should be to review your "Declarations Page" from your insurance policy. Locate the "Deductible" section and the "Loss Settlement" section. Knowing exactly how much you must pay out of pocket and whether you have RCV or ACV coverage will dictate your strategy. Once you have this information, contact a local, high-rated roofing contractor to perform a free damage assessment before officially opening a claim with your carrier.
Image Gallery
Select an image to open it in a new tab.

Celine Dubois
Contemporary Living and Global Arts Columnist
