
Evaluating financial progress relative to peers requires reliable data sources, and the DQYDJ (Don't Quit Your Day Job) net worth by age datasets offer some of the most frequently cited public benchmarks for household wealth in the United States. Derived primarily from the Federal Reserve’s Survey of Consumer Finances (SCF), these figures provide median, average, and percentile breakdowns that help individuals contextualize their financial standing across different life stages.
Introduction to DQYDJ and Wealth Benchmarking
Personal finance enthusiasts and researchers often look for ways to measure financial success beyond subjective impressions. Don't Quit Your Day Job (DQYDJ) is a financial blog and data analysis platform created by software engineer and analyst Peerhove and economist Jon. The site is widely recognized for processing complex economic datasets—most notably the Federal Reserve’s triennial Survey of Consumer Finances—into accessible calculators, charts, and articles.
The primary utility of looking at net worth by age through DQYDJ's analysis lies in moving away from abstract financial targets. Instead of relying on generalized rules of thumb, such as saving a specific multiple of your salary by age thirty, readers can review empirical percentiles. These percentiles illustrate what real American households own minus what they owe at various stages of their lives.
However, evaluating these benchmarks requires careful interpretation. Net worth distribution in the United States is heavily skewed. Mean (average) figures are routinely pulled upward by high-net-worth households, making median (middle-point) numbers a far more accurate reflection of the typical household experience. Understanding how these metrics are calculated, what assets are included, and how demographic variables influence the results is essential for anyone attempting a realistic financial comparison.
The Core Data Source: The Federal Reserve Survey of Consumer Finances
To understand DQYDJ net worth figures, one must first understand the foundation upon which they are built: the Survey of Consumer Finances (SCF). Conducted every three years by the Federal Reserve Board in cooperation with the Department of the Treasury, the SCF is considered the gold standard for measuring American household wealth, debt, and demographic characteristics.
Scope and Methodology of the SCF
The SCF captures detailed information on household finances, including primary residences, financial securities, business equity, retirement accounts, and all forms of consumer and mortgage debt. Unlike tax data, which misses non-taxable assets or non-filers, or Forbes-style lists that focus exclusively on the ultra-wealthy, the SCF surveys thousands of diverse American families to create a statistically representative sample of the entire population.
DQYDJ takes these massive public datasets and runs customized statistical analyses to produce net worth by age brackets. They isolate specific age cohorts—such as under 35, 35 to 44, and so on—and calculate various statistical markers:
- The Median: The exact midpoint of the data set. Fifty percent of households in the age bracket have a higher net worth, and fifty percent have a lower net worth.
- The Mean (Average): The sum of all household net worths in an age bracket divided by the total number of households.
- Percentiles: Specific markers (such as the 25th, 75th, 90th, or 99th percentiles) that show precisely where a household stands relative to others in the same age group.
Assets and Liabilities Included
When reviewing these net worth figures, it is vital to remember what constitutes net worth in these calculations. Net worth is strictly defined as total assets minus total liabilities.
- Included Assets: Cash, checking and savings accounts, certificates of deposit, mutual funds, stocks, bonds, retirement accounts (401(k), IRA, pension values), primary real estate equity, secondary properties, business equity, and valuable personal property (vehicles, jewelry, art).
- Included Liabilities: Mortgages on primary and secondary properties, home equity lines of credit (HELOCs), student loans, credit card balances, auto loans, and other personal or business debts for which the household is personally liable.
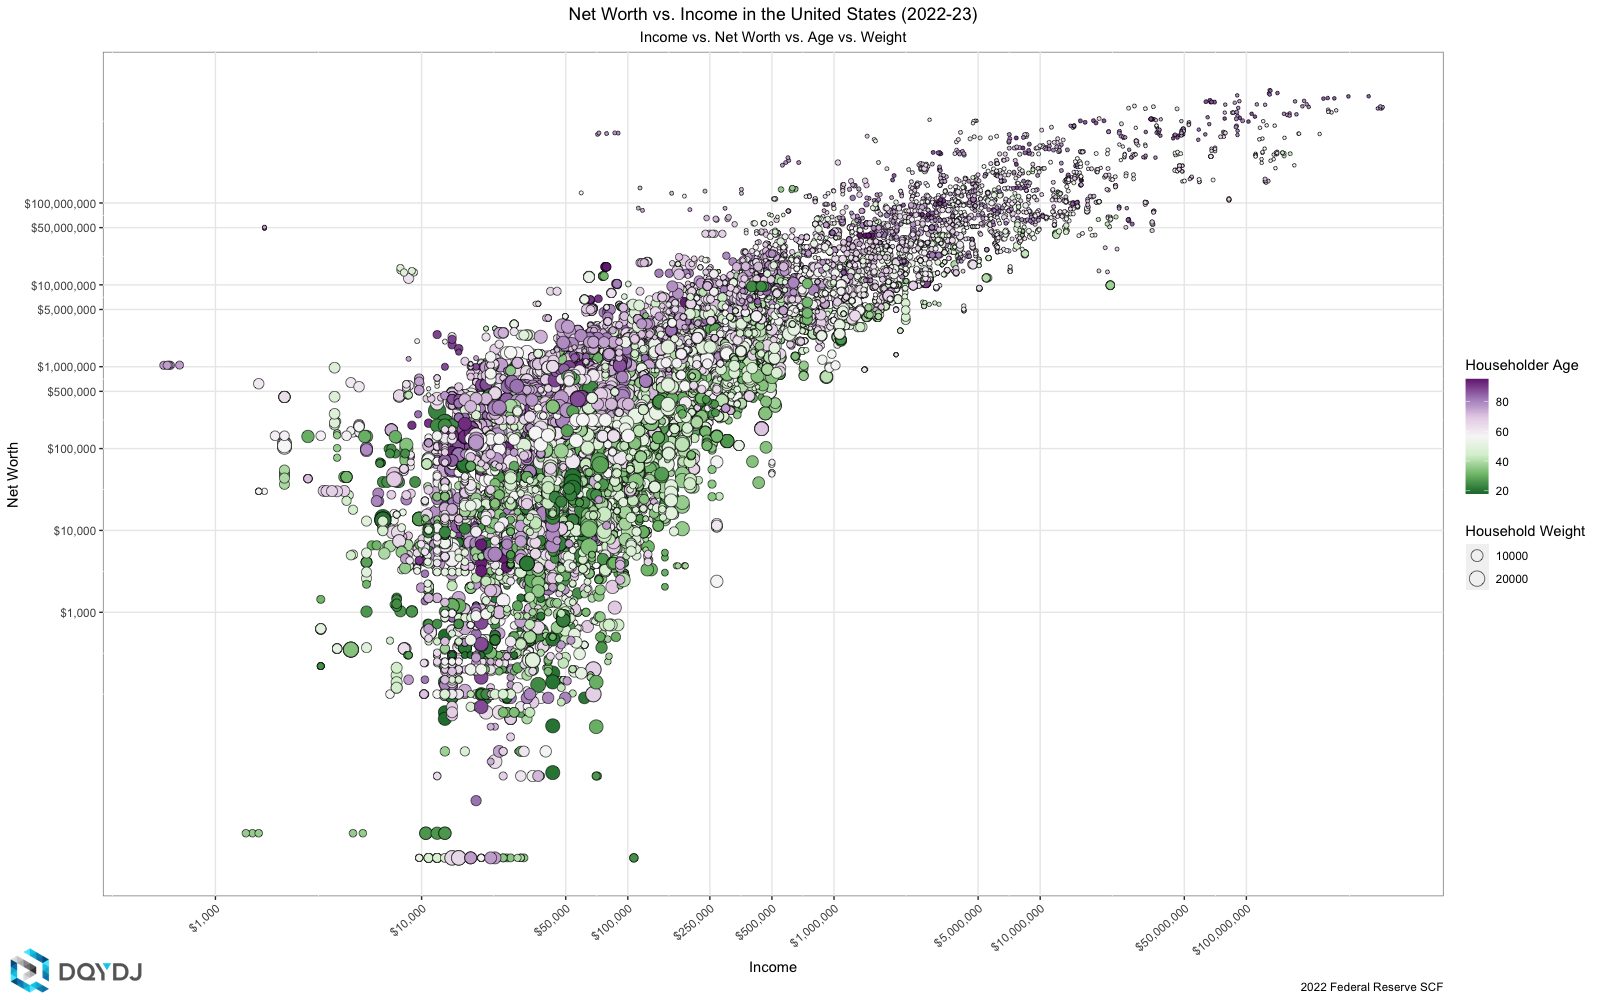
Net Worth Breakdown by Age Cohorts
Financial accumulation is inherently tied to the timeline of human life. Young adults typically start with negative or low net worth due to education debt and early-career earnings, while middle-aged and older adults accumulate assets through homeownership, disciplined investing, and career progression.
The following breakdown examines how net worth scales across primary age brackets, highlighting the divergence between median and mean figures.
Under 35 Years Old
For individuals under 35, net worth is often characterized by volatility and high debt loads relative to accumulated assets. This cohort includes recent college graduates, individuals completing professional or medical training, and young families entering the housing market for the first time.
- The Reality of Student Debt: Many households in this bracket carry significant student loan burdens. While these loans are liabilities, the education they financed often acts as an investment in future human capital, which is not directly captured as an asset on a balance sheet.
- Early Asset Accumulation: Assets for this group typically consist of starter vehicles, modest balances in employer-sponsored retirement plans like 401(k)s, and early savings accounts.
- Statistical Spread: The median net worth for households under 35 is generally modest—often in the low tens of thousands of dollars. However, the mean is noticeably higher due to a small subset of young entrepreneurs, high earners in tech or finance, or those who received substantial family inheritances.
35 to 44 Years Old
As individuals transition into their late thirties and early forties, the financial profile begins to shift. Peak earning years are approaching, and foundational wealth-building mechanisms take root.
- Real Estate Equity: Many households in this bracket purchase their first homes or upgrade from starter homes. As they make monthly mortgage payments, a portion of each payment builds home equity, adding a significant non-liquid asset to their net worth.
- Compound Growth in Retirement Accounts: With a decade or more of consistent contributions to retirement accounts, compound interest begins to exert a noticeable influence on portfolio balances.
- Peak Debt Years: This age group also tends to hold the highest levels of total debt, driven by large mortgages and often the costs associated with raising and educating young children. Despite this debt, asset growth generally outpaces liabilities, causing the median net worth to rise substantially compared to the under-35 cohort.
45 to 54 Years Old
Entering middle age, households frequently experience their peak earning years. Financial stability, career seniority, and strategic asset allocation become primary drivers of wealth accumulation.
- Accelerated Savings: With children potentially nearing independence or college age—and mortgages being paid down steadily—disposable income often increases, allowing for higher savings and investment rates.
- Business and Investment Maturity: Small business owners who started ventures in their thirties often see those businesses reach maturity and profitability by this decade. Investment portfolios are larger, meaning market gains translate into greater absolute dollar increases in net worth.
55 to 64 Years Old
The decade leading up to traditional retirement age is a critical consolidation phase. Wealth preservation and catch-up contributions take center stage for those who feel behind on their retirement goals.
- Asset Peak and Consolidation: Net worth levels typically peak in the 55-to-64 or 65-to-74 age brackets. Primary mortgages may be nearing completion or fully paid off, significantly reducing monthly overhead and increasing the net value of real estate holdings.
- Retirement Readiness: Employer pensions, traditional IRAs, Roth accounts, and taxable brokerage accounts represent the bulk of net worth during this period. The gap between median and mean households often widens significantly here, as high-earning professionals maximize senior executive compensation and long-term investments.
65 Years and Older
For retirees and older demographics, net worth reflects the cumulative results of a lifetime of earning, saving, spending, and investing.
- Decumulation Phase: In retirement, households generally transition from asset accumulation to asset decumulation, drawing down retirement accounts, utilizing Social Security, and potentially tapping home equity through downsizing or reverse mortgages.
- Sustained Net Worth: Despite drawing down accounts, median net worth for older cohorts often remains robust because reduced debt loads (such as paid-off homes) offset the lack of ongoing earned income. However, the variance within this group is extreme, heavily dependent on lifetime earnings, health care costs, and defined-benefit pension availability.
| Age Cohort | Typical Median Net Worth Range (Approximate Historical SCF Trends) | Primary Wealth Drivers | Common Financial Vulnerabilities |
|---|---|---|---|
| Under 35 | $10,000 – $20,000 | Early career savings, initial vehicle and home equity, 401(k) matching | Student loans, credit card debt, low initial savings |
| 35 to 44 | $60,000 – $90,000 | Real estate appreciation, retirement account compounding, career progression | Large mortgages, child care costs, lifestyle inflation |
| 45 to 54 | $130,000 – $180,000 | Peak earning years, business equity, mature investment portfolios | College funding, peak debt loads, eldercare responsibilities |
| 55 to 64 | $200,000 – $260,000 | Paid-off mortgages, maximum retirement contributions, investment gains | Healthcare costs, market downturns near retirement |
| 65+ | $250,000 – $300,000+ | Cumulative lifetime savings, Social Security, home equity | Fixed income risks, long-term care expenses |
Interpreting Percentiles: Where Do You Stand?
When people review DQYDJ net worth calculators, their primary goal is usually to find their specific percentile ranking. Understanding what these percentiles mean prevents unnecessary financial anxiety while offering realistic targets for improvement.
The Significance of Percentiles
A percentile indicates the percentage of households that fall below a specific net worth threshold. For example, if a 40-year-old household has a net worth that places them in the 75th percentile, it means their household net worth is higher than 75% of all households in the same age bracket, while 25% have a higher net worth.
- The 50th Percentile (Median): Represents the exact middle. Achieving the median means you are keeping pace with the typical American household in your age group.
- The 75th Percentile: Indicates upper-middle wealth accumulation, often achieved by dual-income professional households practicing consistent saving and investing habits over a decade or more.
- The 90th and 99th Percentiles: Represent high-net-worth and very-high-net-worth brackets. These tiers are frequently dominated by business owners, senior corporate executives, successful real estate investors, or individuals with significant inherited wealth.
Why Averages Can Be Misleading
A common pitfall when analyzing wealth data is confusing the average (mean) with the median. Because wealth distribution in market economies follows a Pareto-like distribution (where a small percentage of the population holds a disproportionately large share of total wealth), the mean is pulled drastically higher by multi-millionaires and billionaires.
If an average net worth for a 35-year-old cohort appears to be several hundred thousand dollars, but the median is under $50,000, it tells a very different story. Relying on the median provides a much more accurate benchmark for what a typical working household has achieved.
Limitations of Net Worth Benchmarks
While DQYDJ net worth by age calculators provide valuable macro-level insights, they come with notable limitations that users must keep in mind when evaluating their personal finances.
Geographic Cost of Living Discrepancies
Net worth figures aggregated at the national level do not account for regional economic differences. A home purchased for $800,000 in San Francisco, California, generates substantial paper net worth through home equity compared to an identical-sized home purchased for $200,000 in a rural Midwestern town. However, the ongoing cost of living, state tax burdens, and localized expenses differ vastly between these regions. Comparing a household in a high-cost-of-living coastal city directly against a national median can distort expectations.
Household Composition and Inheritance
The SCF data aggregates households, which can mask individual achievements. Dual-income-no-kids (DINKS) households often accumulate wealth significantly faster than single-income households with dependents. Furthermore, national datasets capture generational wealth transfers. Individuals who receive substantial inheritances or family financial support early in life will skew higher in younger percentiles through no distinct operational effort of their own.
Omission of Human Capital
As noted earlier, a young doctor or lawyer may have a negative net worth due to hundreds of thousands of dollars in professional school debt. However, their future earning potential (human capital) is immense. Standard net worth calculations treat this debt strictly as a negative liability while failing to value the future cash flows those professional degrees will generate.
Practical Steps to Improve Your Net Worth Standing
Reviewing net worth benchmarks should serve as a diagnostic tool rather than a source of discouragement. If your current standing falls below your desired percentile, several proven financial principles can accelerate wealth accumulation over time.
- Focus on the Savings Rate Over Absolute Income: While earning a high income helps, the percentage of income saved and invested is the primary driver of net worth growth. Automating transfers into retirement accounts ensures that wealth-building happens before discretionary spending occurs.
- Minimize High-Interest Consumer Debt: Carrying high-interest credit card balances acts as a severe drag on net worth growth, requiring exorbitant returns on investments just to break even. Prioritizing the elimination of unsecured debt frees up cash flow for productive assets.
- Optimize Housing Costs: Housing is typically both a household's largest expense and its largest asset. Ensuring that housing costs remain well within sustainable percentages of take-home pay prevents lifestyle inflation from devouring capital that could otherwise be invested in broad-market index funds or real estate equity.
- Take Advantage of Tax-Advantaged Accounts: Utilizing employer-sponsored plans (like 401(k)s or 403(b)s) and individual retirement accounts (IRAs) reduces current tax liabilities while allowing investments to compound tax-deferred or tax-free over decades.
Disclaimer: This article is for informational and educational purposes only and does not constitute professional financial, legal, or tax advice. Individual financial circumstances vary widely, and readers should consult with a qualified, licensed financial advisor before making major financial decisions.
Frequently Asked Questions
What is the difference between mean and median net worth in DQYDJ calculators?
The median net worth represents the exact midpoint of all surveyed households, meaning half have more and half have less, making it an accurate reflection of the typical household. The mean net worth is the mathematical average, which is heavily skewed upward by a small percentage of ultra-high-net-worth households.
Why is net worth often negative for individuals under 35?
Young adults frequently carry substantial student loan debt, auto loans, and credit card balances while having had very little time to accumulate tangible assets or home equity. This combination of early liabilities and minimal asset accumulation frequently results in a negative net worth during early adulthood.
Does primary home equity count toward net worth?
Yes. Net worth is calculated as total assets minus total liabilities. Primary residence home equity is determined by taking the current market value of the home and subtracting the remaining balance of all mortgages and home equity loans secured against the property.
How often are the underlying DQYDJ net worth datasets updated?
DQYDJ updates its net worth calculators and articles to align with the release of the Federal Reserve’s Survey of Consumer Finances, which is published every three years. Users should check the publication date of specific data analyses to ensure they are referencing the most recent Federal Reserve cycle.
Is it normal to have a lower net worth than the median for my age?
Yes. National net worth figures combine households across all geographic regions, career paths, and family structures. Factors such as regional cost of living, career choice, single-income versus dual-income households, and unexpected life events can cause significant variance, meaning many financially secure individuals fall below median benchmarks.
Image Gallery
Select an image to open it in a new tab.

Lars Thomsen
Global Labor Markets and Economic Strategy Editor
