
Navigating auto insurance in Memphis, TN, requires a balance of meeting Tennessee’s legal minimums and protecting yourself against local risks like high uninsured motorist rates and vehicle theft. Drivers must carry liability limits of at least 25/50/25, though significant regional traffic and crime statistics often necessitate comprehensive and uninsured motorist coverage for full protection in 2026.
Auto insurance is not merely a legal checkbox; it is a critical financial safeguard in a city known for its complex transit corridors and unique urban challenges. Memphis, often referred to as the "Distribution Center of America," sees a high volume of commercial and passenger traffic daily. This density, combined with Tennessee’s specific insurance laws, makes understanding your policy essential for every resident of the Bluff City.
Tennessee’s Mandatory Auto Insurance Requirements
In 2026, Tennessee continues to operate under a "tort" or "at-fault" system. This means the person found responsible for a car accident is liable for the damages. To ensure drivers can cover these costs, the state mandates specific minimum levels of liability insurance under the Tennessee Financial Responsibility Law.
Minimum Liability Limits (25/50/25)
The state-mandated minimums are often expressed as 25/50/25. Here is a breakdown of what those numbers actually cover:
- $25,000 for Bodily Injury per person: This is the maximum amount your insurance will pay for the medical expenses of a single person injured in an accident where you are at fault.
- $50,000 for Bodily Injury per accident: This is the total cap your insurance will pay for all injuries sustained by multiple people in a single accident.
- $25,000 for Property Damage: This covers repairs to the other driver's vehicle or any property (fences, light poles, buildings) damaged in the collision.
While these are the legal minimums, they are often insufficient for major accidents. For instance, if you are involved in a multi-car pileup on I-240, $25,000 in property damage may not even cover the cost of one modern SUV. Many Memphis insurance agents recommend increasing these limits to at least 100/300/100 to avoid personal financial ruin in the event of a lawsuit.
The Tennessee Electronic Insurance Verification System (EIVS)
The Tennessee Department of Revenue utilizes the Electronic Insurance Verification System to cross-reference vehicle registrations with insurance policy databases. If your policy lapses, the system automatically flags your registration. Failure to maintain coverage can result in fines, the suspension of your vehicle registration, and a $25 or $300 reinstatement fee depending on the duration of the lapse.
Why Memphis Rates Differ from Other Tennessee Cities
If you move from Nashville or Knoxville to Memphis, you will likely notice a change in your premium. Several localized factors contribute to the cost of auto insurance in the 901 area code.
High Rates of Uninsured Drivers
Tennessee consistently ranks among the top states for uninsured motorists. In the Memphis metropolitan area, the percentage of drivers operating without insurance is historically higher than the national average. This increases the risk for insured drivers, as a collision with an uninsured motorist leaves the victim with few options for recovery unless they have specific "Uninsured Motorist" (UM) coverage. Consequently, insurance companies raise premiums in this region to offset the higher likelihood of UM claims.
Traffic Congestion and Logistics Hub Risks
Memphis is a primary hub for FedEx and various trucking logistics firms. This means the city’s highways—particularly the I-40/I-240 loop and the I-55 bridge—are constantly filled with heavy commercial vehicles. The mixture of heavy freight and high-speed commuter traffic leads to more frequent and more severe collisions. Carriers analyze these "crash frequencies" by zip code to determine the likelihood of a claim.
Vehicle Theft and Vandalism Statistics
Memphis has faced challenges with vehicle-related crimes, including "smash-and-grabs" and auto theft. If you live in high-density urban areas like Downtown or Midtown, or even growing suburbs like Cordova, your "Comprehensive" coverage rates—which protect against theft and vandalism—may be higher than in more rural parts of Shelby County.

Essential Coverage Add-ons for Memphis Drivers
Given the local environment, the state minimum coverage is rarely enough. To ensure full protection, Memphis drivers should consider several optional but highly recommended policy additions.
Uninsured/Underinsured Motorist Coverage (UM/UIM)
As mentioned, the high number of uninsured drivers in Memphis makes this coverage vital. UM coverage pays for your medical bills and property damage if you are hit by someone who has no insurance. UIM coverage kicks in if the other driver has insurance, but their limits are too low to cover your total damages. In Tennessee, you must specifically reject this coverage in writing if you do not want it; otherwise, it is typically added to your policy.
Comprehensive and Collision Coverage
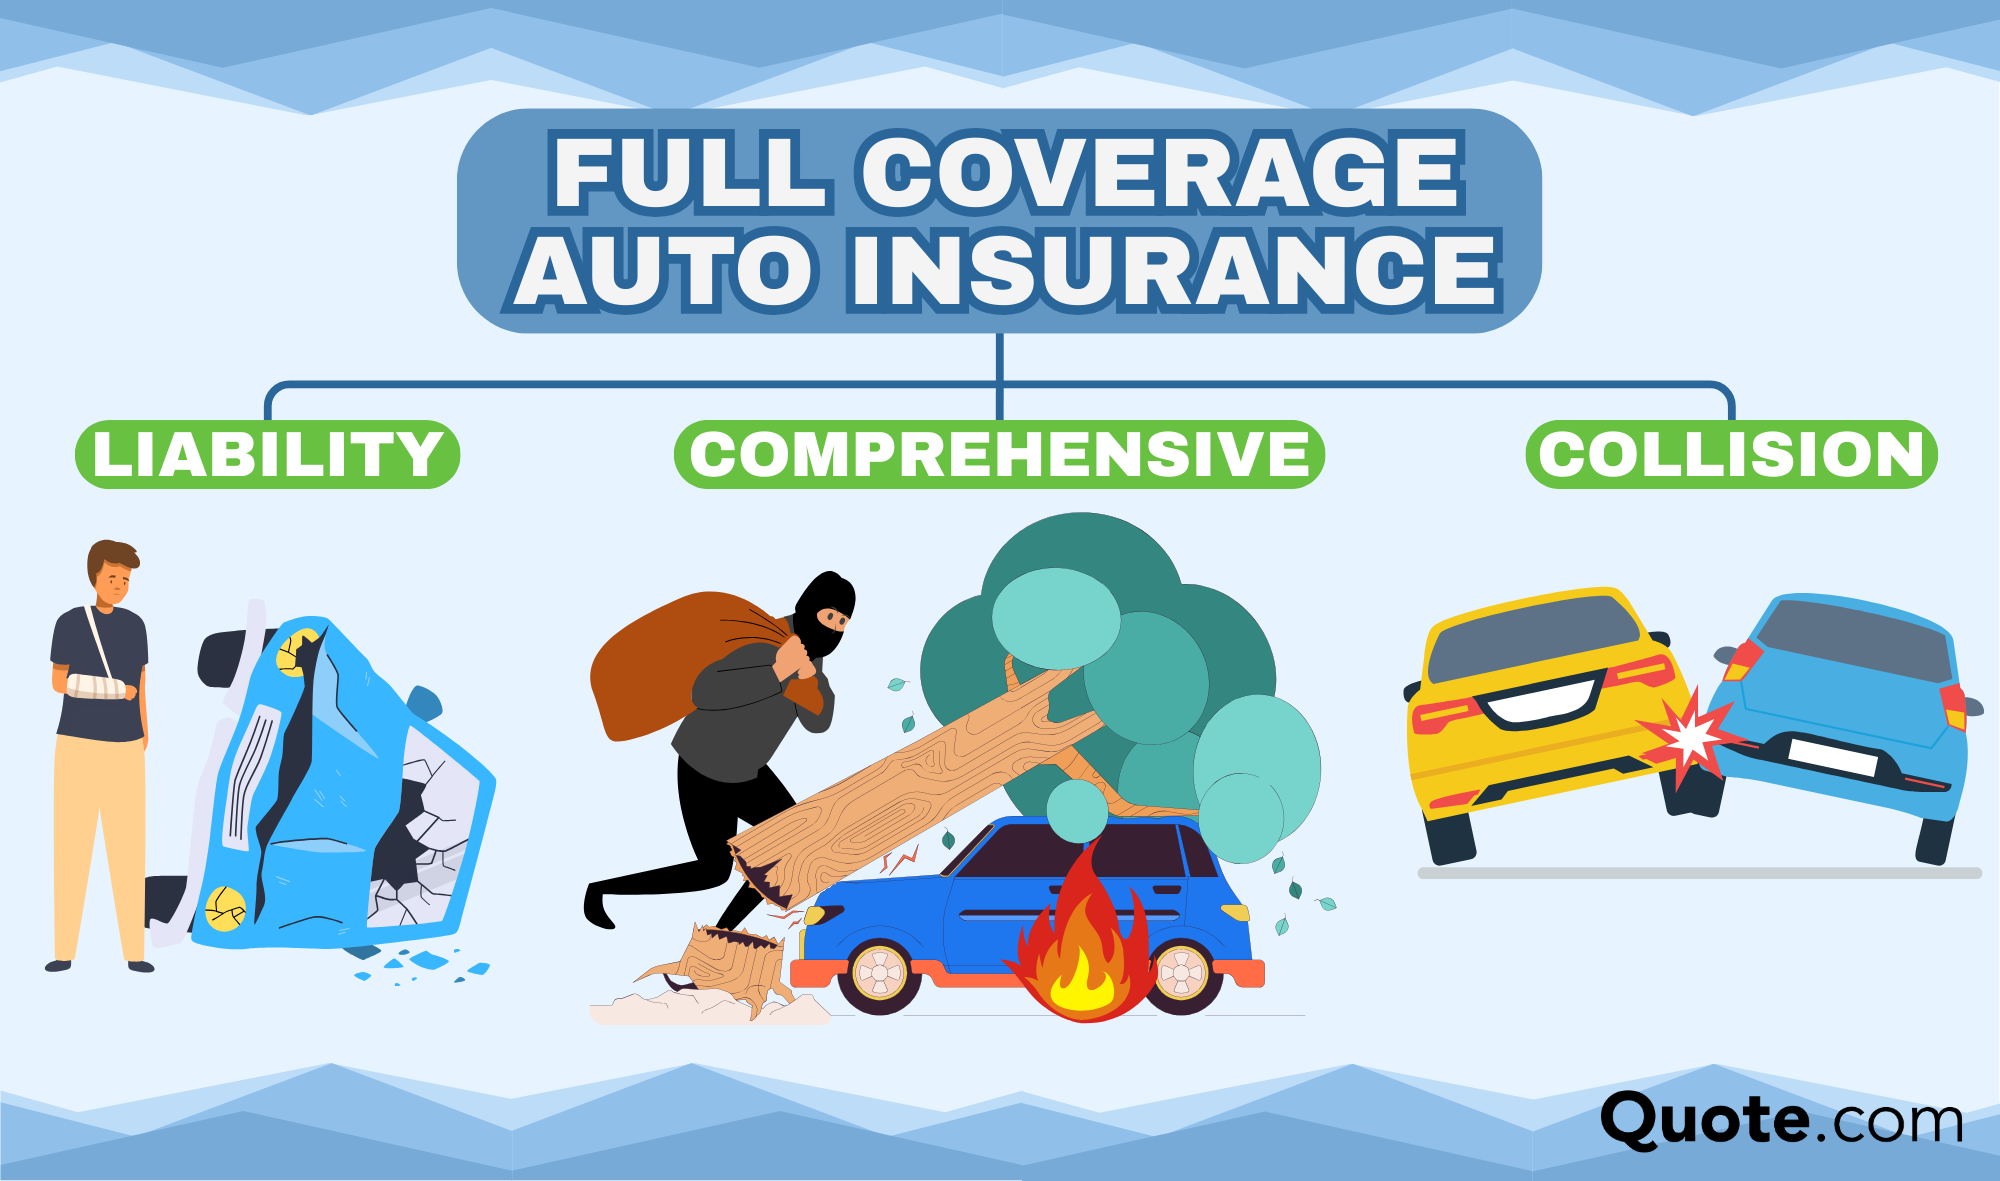
While liability covers the other person, these two cover your vehicle:
- Collision: Pays for repairs to your car regardless of who is at fault in an accident.
- Comprehensive: Covers non-collision events such as theft, fire, hail (common in Tennessee spring storms), and vandalism. If your car is stolen in a Memphis neighborhood, only Comprehensive coverage will reimburse you for the vehicle’s value.
Gap Insurance
With the rising cost of vehicles in 2026, many drivers find themselves "underwater" on their car loans, meaning they owe more than the car is worth. If your vehicle is totaled in a crash, standard insurance only pays the current market value. Gap insurance covers the "gap" between that payout and what you still owe the lender.
2026 Estimated Cost Comparison for Memphis Drivers
The following table provides an estimate of annual premiums in Memphis based on different driver profiles and coverage levels. Note that these are averages and individual rates will vary based on credit score, specific zip code, and vehicle type.
| Driver Profile | Minimum Liability Only (Annual) | Full Coverage (Annual) | Primary Factor Influencing Rate |
|---|---|---|---|
| Young Driver (18-24) | $1,200 - $1,800 | $3,500 - $5,000 | Lack of experience/high risk |
| Clean Record (30-55) | $600 - $900 | $1,800 - $2,400 | Proven safety record |
| Driver with 1 At-Fault Accident | $950 - $1,400 | $2,600 - $3,500 | Recent claims history |
| High Risk (DUI or SR-22) | $1,500 - $2,500 | $4,500 - $6,500 | Legal and safety requirements |
Factors That Influence Your Premium in Memphis
Insurance companies use complex algorithms to determine your risk level. In Tennessee, several specific variables are legally permitted for use in rate-setting.
Credit-Based Insurance Scores
Tennessee is one of the states that allow insurance companies to use your credit history as a factor in your premium. In the eyes of an actuary, a driver with a higher credit score is statistically less likely to file a claim. Improving your credit score can be one of the most effective ways to lower your insurance costs in Memphis.
Zip Code Variations
Rates can vary significantly even within Shelby County. For example, a resident in the 38103 (Downtown) zip code may pay more due to higher theft risks and street parking, whereas someone in 38017 (Collierville) might see lower rates due to lower crime statistics and more garage-parked vehicles.
Driving Record and Telematics
Your history of speeding tickets, accidents, and moving violations remains the most significant factor. Many carriers in 2026 offer "Telematics" programs—apps or plug-in devices that track your braking, speed, and nighttime driving. For Memphians who commute safely on Germantown Parkway or Poplar Avenue, these programs can offer discounts of up to 30%.
Navigating the SR-22 Requirement in Tennessee
If you have had your license suspended due to a DUI, reckless driving, or driving without insurance, the state may require you to file an SR-22.
An SR-22 is not insurance; it is a certificate of financial responsibility filed by your insurance company with the Tennessee Department of Safety and Homeland Security. It proves that you carry the state-mandated minimum coverage.
In Memphis, finding a carrier that will file an SR-22 can be difficult, as many "standard" companies may drop you for being high-risk. You may need to look for "non-standard" insurers who specialize in high-risk policies. Be prepared for significantly higher premiums and the requirement to maintain the SR-22 for three consecutive years without any lapses.
How to Save on Auto Insurance in Memphis
Despite the challenges of the Memphis market, there are several ways to reduce your monthly premium without sacrificing essential coverage.
- Bundle Policies: Combining your auto insurance with homeowners or renters insurance is the most common way to get a "multi-policy" discount.
- Increase Deductibles: If you can afford a $1,000 out-of-pocket expense in the event of an accident, increasing your deductible from $500 can lower your monthly premium by 15-20%.
- Defensive Driving Courses: Many Tennessee insurers offer discounts to drivers who complete a state-approved defensive driving course. This is particularly beneficial for seniors and teenagers.
- Student Discounts: If you have a student on your policy attending the University of Memphis or Rhodes College, ensure they maintain a "B" average or higher to qualify for a good student discount.
- Shop Around Annually: The insurance market in Memphis is competitive. Use 2026 as a year to re-evaluate your policy, as new carriers often enter the Tennessee market with aggressive introductory rates.
Choosing the Right Agent: Local vs. Direct
When seeking "all about auto insurance Memphis TN," you must decide between a direct online provider and a local independent agent.
- Direct Providers (e.g., Geico, Progressive, State Farm): These offer convenience and robust mobile apps. They are often faster for simple policies but may lack the "boots on the ground" knowledge of Memphis-specific issues.
- Local Independent Agents: These professionals represent multiple companies. They understand the nuance of Memphis neighborhoods and can often find niche carriers that direct providers won't show you. If you have a unique situation, such as an older home in Cooper-Young or a high-performance vehicle, a local agent can provide personalized advice.
Frequently Asked Questions
What happens if I am caught driving without insurance in Memphis?
Driving without insurance in Memphis is a Class C misdemeanor. You can face fines of up to $300, the towing and impoundment of your vehicle, and the suspension of your driver’s license. Furthermore, if you are in an accident while uninsured, you can be held personally liable for all damages, and your "No Pay, No Play" status in Tennessee might limit your ability to sue for non-economic damages even if the other driver was at fault.
Does Memphis have "No-Fault" insurance?
No. Tennessee is an "At-Fault" state. This means the person who caused the accident is responsible for the damages. Their insurance pays for your injuries and car repairs. If their insurance is insufficient, you may need to rely on your own Uninsured Motorist coverage or file a civil lawsuit.
How do Memphis storms affect my car insurance?
Memphis frequently experiences severe thunderstorms, wind, and occasional hail. Damage from these weather events is covered under "Comprehensive" insurance. If you only have "Liability" insurance, you will have to pay for storm damage (like a fallen tree limb on your windshield) entirely out of pocket.
Is my car covered if someone else drives it?
In Tennessee, insurance typically follows the vehicle, not the driver. If you give someone "permissive use" of your car and they get into an accident, your insurance will generally be the primary coverage. However, if that person lives in your household and is not listed on your policy, the claim could be denied.
Why did my Memphis insurance rate go up when I didn't have an accident?
Insurance rates are "pooled." If there is a spike in auto thefts or major accidents across Memphis, the insurance company may raise rates for the entire area to maintain their ability to pay claims. Inflation in 2026 also plays a role, as the cost of car parts and medical care continues to rise.
Final Recommendation for Memphis Drivers
For most drivers in the Memphis area, the smartest path forward in 2026 is a policy that includes 100/300/100 liability limits, Uninsured Motorist coverage, and a Comprehensive deductible that fits your emergency savings. Given the city's unique traffic patterns and high rate of uninsured motorists, relying on the state minimum is a high-stakes gamble. Before renewing your policy, compare at least three quotes and specifically ask about "telematics" discounts if you have a safe, predictable commute.
Image Gallery
Select an image to open it in a new tab.

Vivian Cho
Executive IT and Emerging Technologies Reporter
