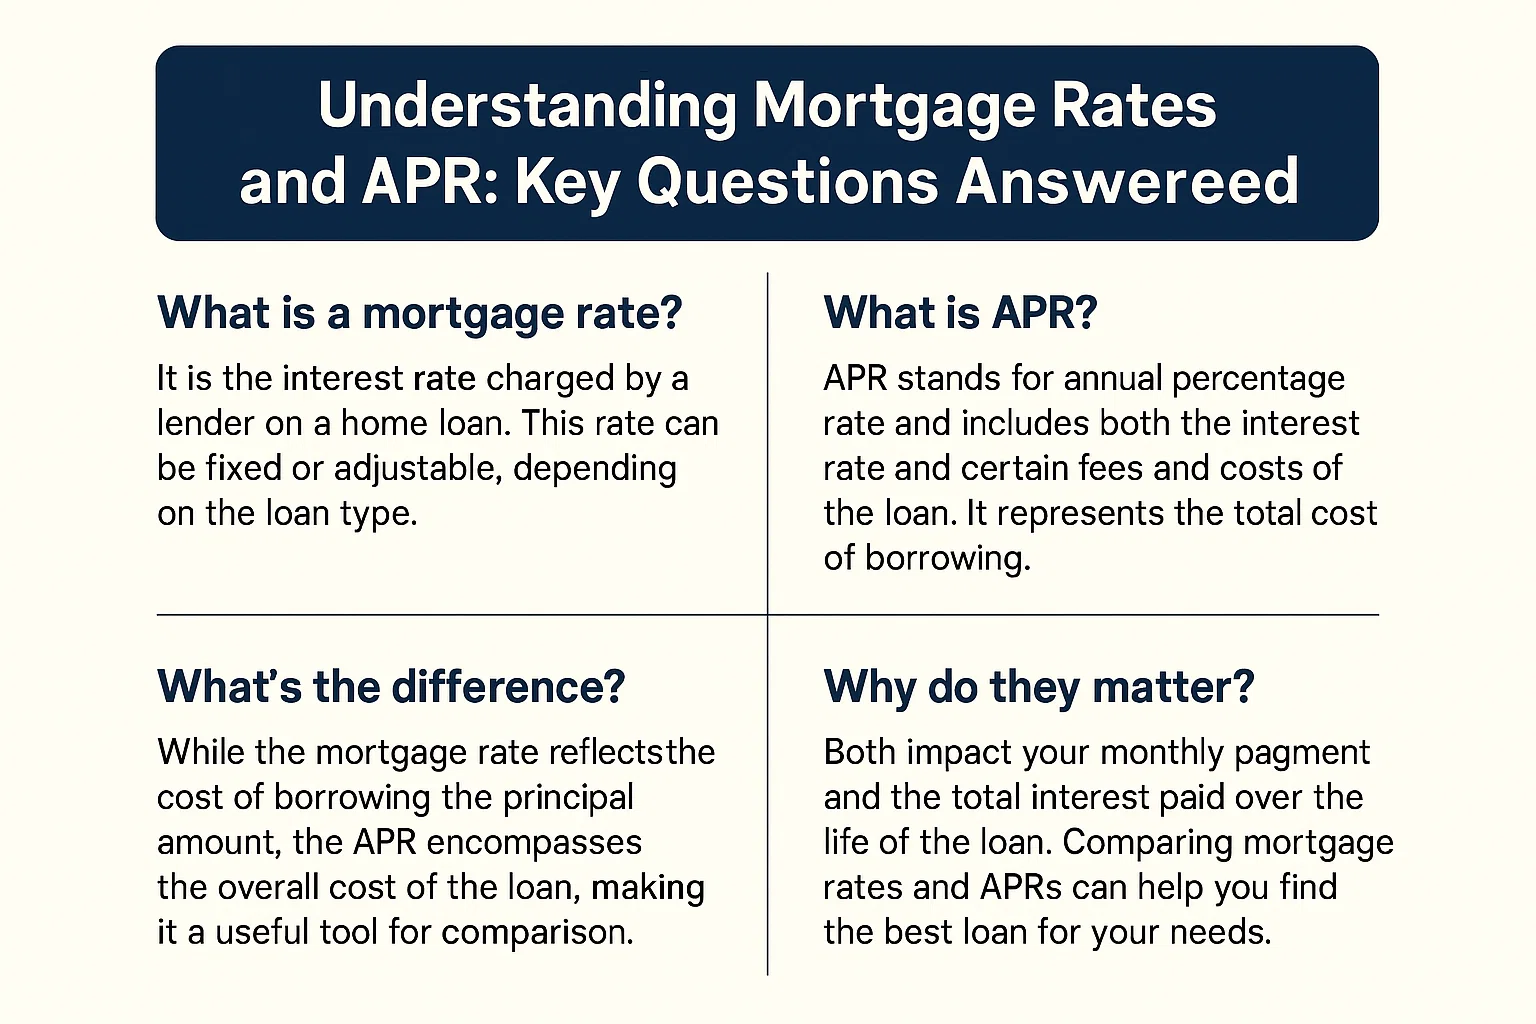
Understanding a mortgage broker rate requires distinguishing between the interest rate you pay to a lender and the compensation a broker receives for facilitating the transaction. When you work with a mortgage broker, you are engaging an intermediary who acts as a liaison between you and various financial institutions. The "rate" often discussed is the Annual Percentage Rate (APR), which encompasses both the interest charged on your loan and the fees associated with originating that mortgage, including the broker’s commission.
The Role of the Mortgage Broker in Your Loan Process
A mortgage broker acts as a professional negotiator and matchmaker in the real estate finance market. Unlike a bank loan officer, who is limited to the products and interest rates of a single institution, a broker has access to a wide array of wholesale lenders. This reach allows them to compare products from credit unions, private lenders, and major national banks simultaneously.
When you sit down to discuss a mortgage broker rate, it is essential to understand that the broker is not typically the entity funding your loan. They are the facilitator. Your broker gathers your financial documentation—such as tax returns, bank statements, and credit reports—and packages this information to submit to lenders that best suit your specific financial profile. Because they maintain relationships with these lenders, they can often navigate complex underwriting requirements more efficiently than a retail borrower might be able to do alone.
Dissecting the Components of the Mortgage Rate
The rate you see on your loan estimate is rarely just the raw interest rate. It is broken down into two primary components: the note rate and the lender fees, which combine to form the APR.
The Note Rate
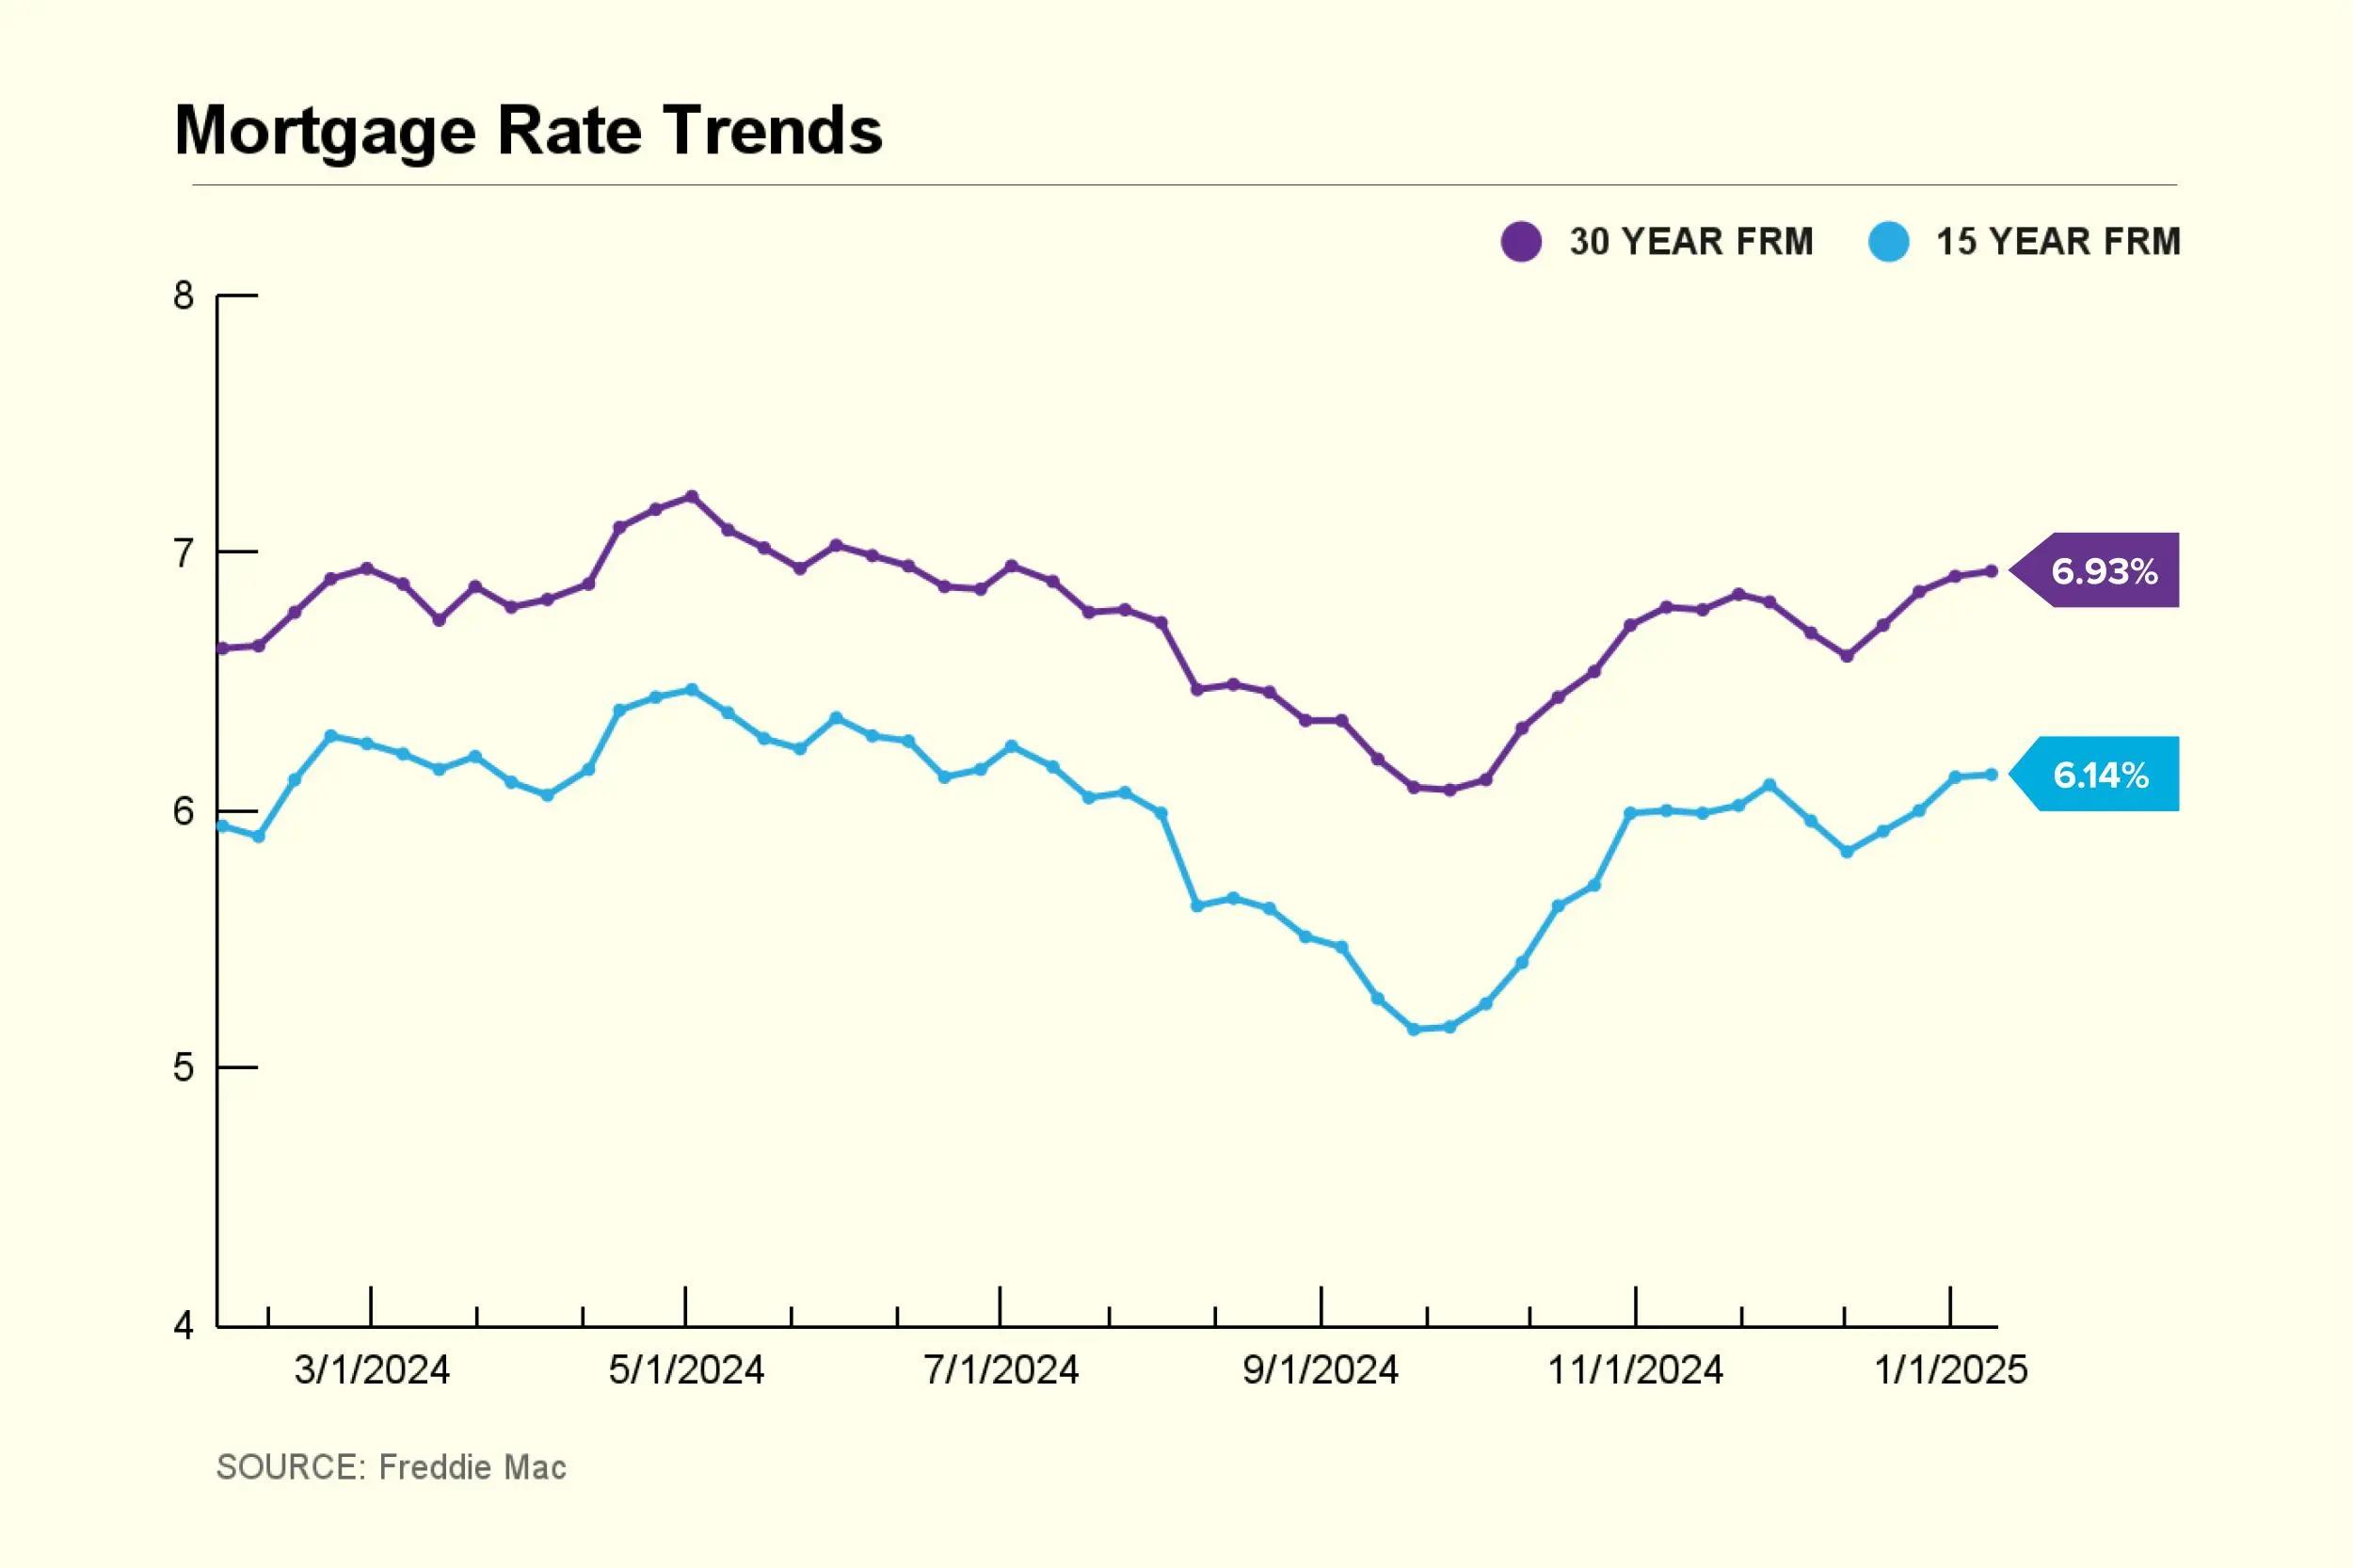
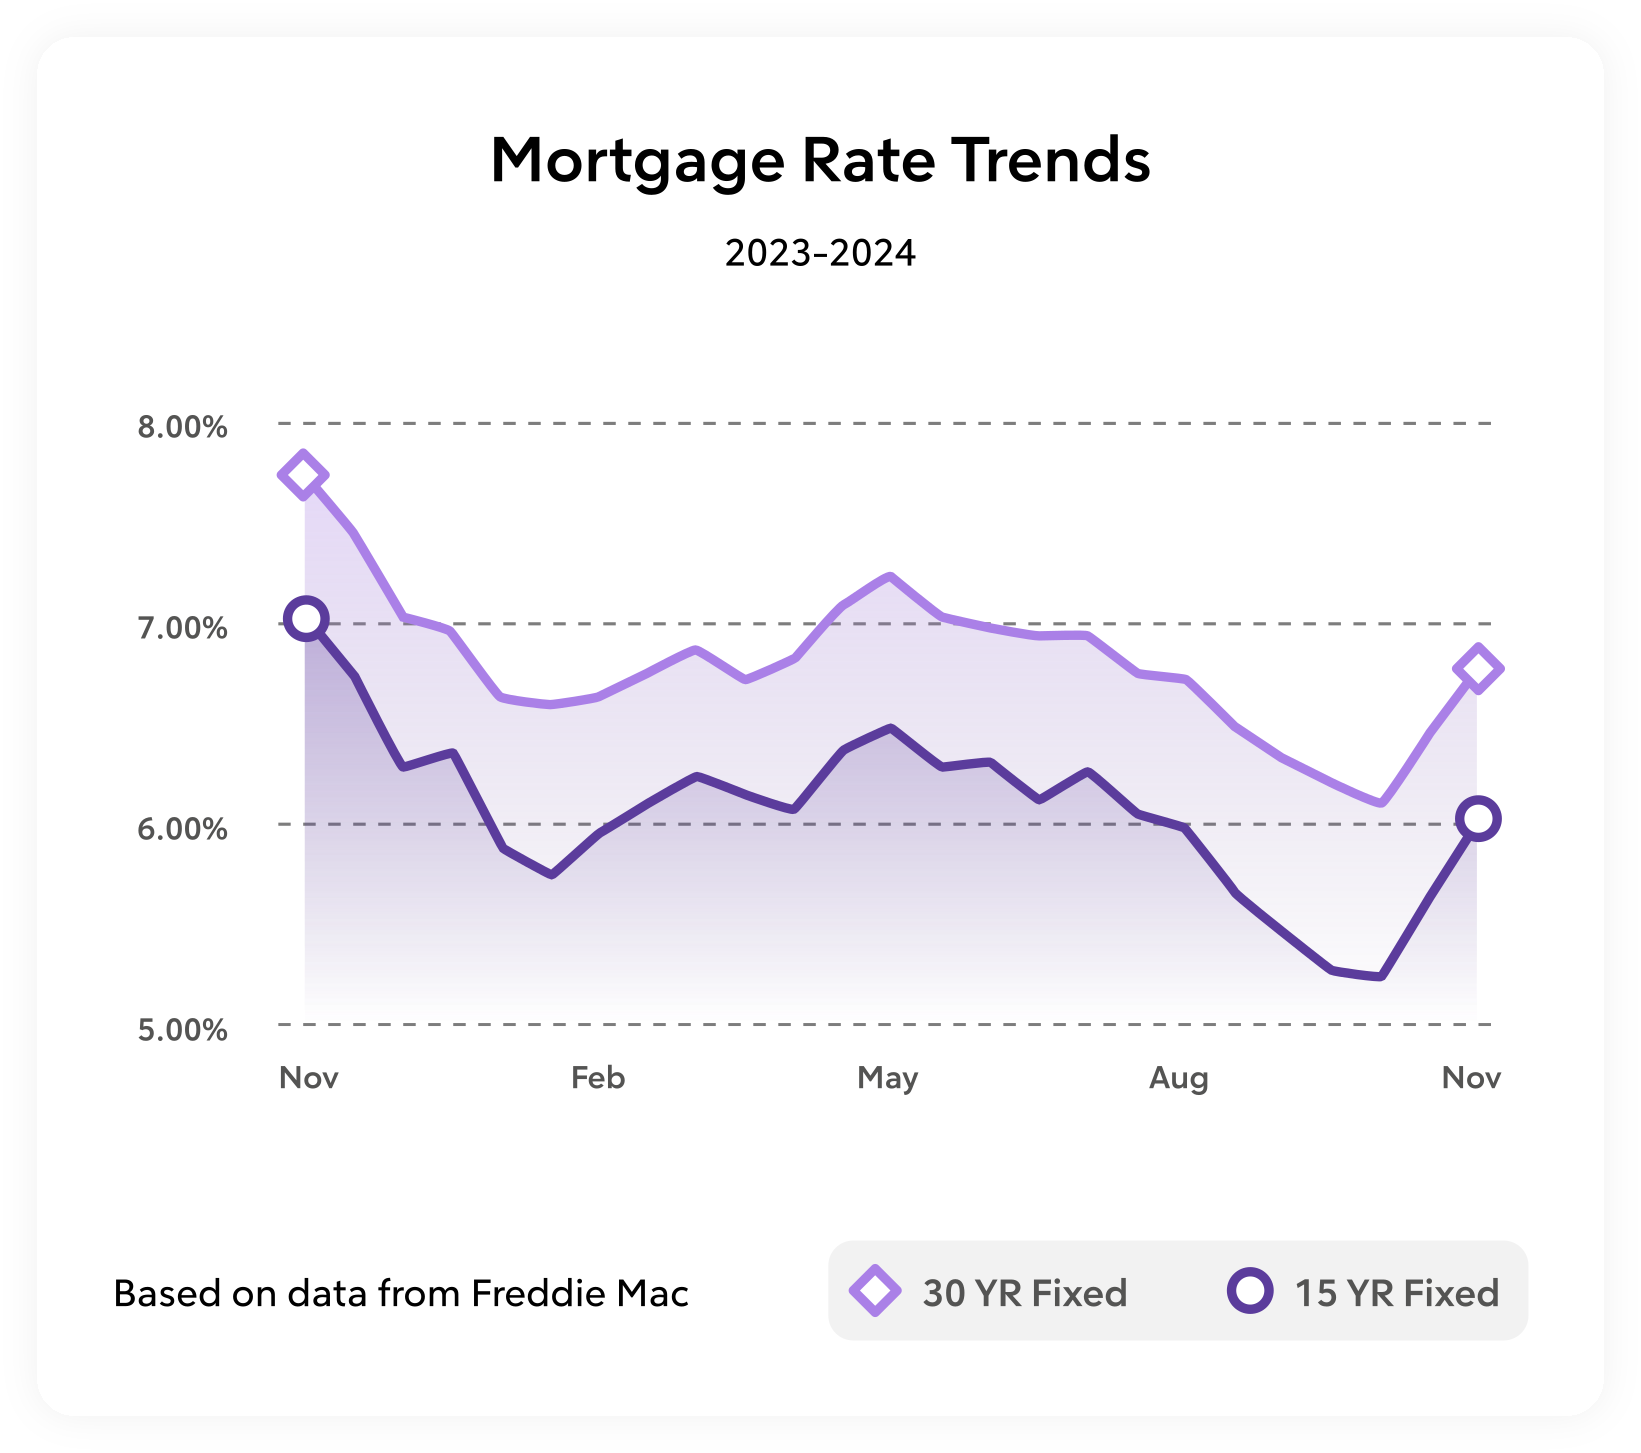
The note rate is the interest percentage charged on the principal balance of your mortgage. This figure dictates your monthly principal and interest payment. This rate is influenced by the Federal Reserve’s federal funds rate, the yield on 10-year Treasury bonds, and the overall state of the national economy. However, your specific note rate is heavily dependent on your individual risk profile—specifically your credit score, loan-to-value (LTV) ratio, and debt-to-income (DTI) ratio.
Broker Compensation and Closing Costs
The broker’s "rate" can also refer to their fee structure. Broker compensation is generally paid in one of two ways:
- Lender-Paid Compensation: The lender pays the broker a commission, which is often baked into your interest rate in the form of "yield spread premium." In this scenario, you might have a slightly higher interest rate, but you pay lower out-of-pocket costs at the closing table.
- Borrower-Paid Compensation: You pay the broker a direct fee. This is often disclosed as an origination fee on your Loan Estimate. By paying this upfront, you may be able to secure a lower note rate, which reduces your interest payments over the life of the loan.

How to Compare Mortgage Broker Rates Effectively
Comparison shopping is the most effective way to ensure you are receiving a competitive deal. Because brokers work with wholesale lenders, their pricing can be very aggressive, but you must be diligent in comparing "apples to apples."
Comparing Loan Estimates
Since 2015, the Consumer Financial Protection Bureau (CFPB) has mandated a standardized form called the Loan Estimate. This document is your most powerful tool. When evaluating a broker, ask for a Loan Estimate from at least two different sources. Pay close attention to:
- The APR: Look at this number rather than just the interest rate. It provides a more accurate view of the total cost of the loan, including prepaid interest, private mortgage insurance (PMI), and broker fees.
- Origination Charges: Check Page 2 of the Loan Estimate. This section outlines exactly what you are paying in fees to the broker and the lender.
- Discount Points: Determine if the rate quoted requires you to pay "points" (prepaid interest) to buy the rate down. A low rate might look attractive, but if you have to pay a significant percentage of the loan amount upfront to achieve it, it may not be the right choice for your timeline.
| Cost Element | Description | Impact on Monthly Payment |
|---|---|---|
| Note Rate | The base interest rate applied to your loan balance. | High impact |
| Origination Fee | Fee paid to the broker for processing the application. | Zero (one-time) |
| Discount Points | Upfront payment to permanently lower the interest rate. | Moderate impact |
| Lender Credit | Credits provided by the lender to offset closing costs. | Varies (often raises rate) |
Factors That Influence Your Final Rate
The rate a broker can offer you is not arbitrary; it is constrained by several objective markers. Understanding these helps you manage your expectations before you start the application process.
Your Credit Profile
Your credit score is the single most significant factor in determining the interest rate tier for which you qualify. Higher scores indicate lower risk to the lender, resulting in more competitive pricing. If your score is below 720, a broker might have more difficulty securing the lowest "advertised" rates, as lenders apply "price adjustments" based on risk.
Loan-to-Value (LTV) Ratio
The amount of your down payment relative to the property's value (or purchase price) matters. A larger down payment reduces the LTV ratio, which in turn lowers the risk for the lender. Loans with an LTV of 80% or lower generally avoid the need for private mortgage insurance, which significantly reduces your total monthly payment.
Market Volatility
Mortgage rates fluctuate daily based on bond market activity. A rate quoted by a broker on a Tuesday morning may differ from a quote on a Wednesday afternoon. It is standard practice to "lock" your rate once you have an accepted offer on a property to protect yourself from these fluctuations until the closing date.
Common Mistakes When Working with Brokers
Avoiding common pitfalls will streamline your experience and help you secure a better financial outcome.
- Focusing Solely on the Interest Rate: Many borrowers ignore closing costs. If a broker offers a rate that is 0.25% lower but charges $5,000 more in fees, you may need several years to "break even" on that investment.
- Failing to Ask About Disclosures: Always ask the broker to explain their compensation model. Are they getting paid by the lender, or are you paying them directly? Transparency is a legal requirement under the Truth in Lending Act (TILA), and a reputable broker will be happy to explain these details.
- Not Providing Full Financial Documentation: Withholding information about debts or recent changes in employment will lead to delays or "denied" statuses later in the process. Brokers need the complete picture to accurately price your loan and ensure you qualify for the program they have proposed.
Regulatory Protections and Professional Standards
In the United States, mortgage brokers are subject to rigorous oversight. The Secure and Fair Enforcement for Mortgage Licensing Act (SAFE Act) requires brokers to be state-licensed and to undergo ongoing education and background checks. Furthermore, federal laws like the Real Estate Settlement Procedures Act (RESPA) prohibit "kickbacks" and ensure that fees are clearly disclosed to the borrower.
Because of these protections, you have a right to ask your broker for a detailed breakdown of all charges. If a figure seems high or unfamiliar, do not hesitate to ask for clarification. A transparent broker will view this as part of their fiduciary duty to ensure you are informed and comfortable with the transaction.
Navigating the Application Process: A Step-by-Step Guide
- Initial Consultation: Discuss your financial goals, time horizon for staying in the home, and credit history with the broker.
- Pre-Approval: The broker will pull your credit and verify your income to issue a pre-approval letter, which is essential for making an offer in a competitive market.
- Loan Comparison: Once you find a property, the broker should present a few loan options (e.g., 30-year fixed vs. 15-year fixed, or different points-to-rate trade-offs).
- Rate Lock: Decide when to lock your interest rate based on current market trends and your expected closing date.
- Underwriting: The lender reviews the file provided by the broker. You may be asked for "conditions" (additional documents). Respond to these requests as quickly as possible.
- Closing: Review the Closing Disclosure (CD) three days before signing. The CD is the final version of the Loan Estimate and must align with what you were previously promised.
Frequently Asked Questions
Are mortgage brokers more expensive than banks?
Not necessarily. While brokers charge a fee for their services, they often have access to wholesale pricing that a retail bank cannot match. Because they operate with lower overhead than major retail banks, their total cost—inclusive of fees and interest—can often be lower.
Does a broker control the interest rate?
No. The broker acts as an intermediary. The interest rate is ultimately set by the lender based on the specific loan program, your credit profile, and market conditions. The broker negotiates to find the best available pricing from their panel of lenders for your specific situation.
Can I negotiate the broker's commission?
In many cases, yes. While some lenders have fixed compensation plans for the brokers they work with, other parts of the closing costs, such as administrative fees, are often negotiable. Always ask what items are flexible on your initial Loan Estimate.
Why does my interest rate change during the process?
Rates are tied to the bond market. If you have not "locked" your rate with a written agreement, your rate can fluctuate based on daily market movements. Once the rate is locked, it remains stable unless your financial situation changes—such as a dip in your credit score or a change in your loan amount.
What should I do if I am unhappy with the rate offered?
Ask for an explanation of why that rate is being offered. It may be due to your specific credit profile or the property type. If you still feel the rate is uncompetitive, do not hesitate to contact another broker or lender to compare, provided you are still within the appropriate timeframe before closing.
Final Recommendations for Your Search
When selecting a mortgage broker, prioritize those who are willing to educate you on the "why" behind the numbers rather than just pushing a specific product. Start by interviewing at least two brokers, request a Loan Estimate from both, and compare the APR and total closing costs. Ensure your documentation is ready and your credit is monitored before beginning the process to ensure you are positioned to receive the best possible rate. By taking an active role in understanding your mortgage broker rate, you protect your financial health for the duration of your homeownership.
Image Gallery
Select an image to open it in a new tab.


Akira Tanaka
International Academic Trends Correspondent
