Understanding Auto Insurance Stacked vs. Unstacked: The Dave Ramsey Perspective
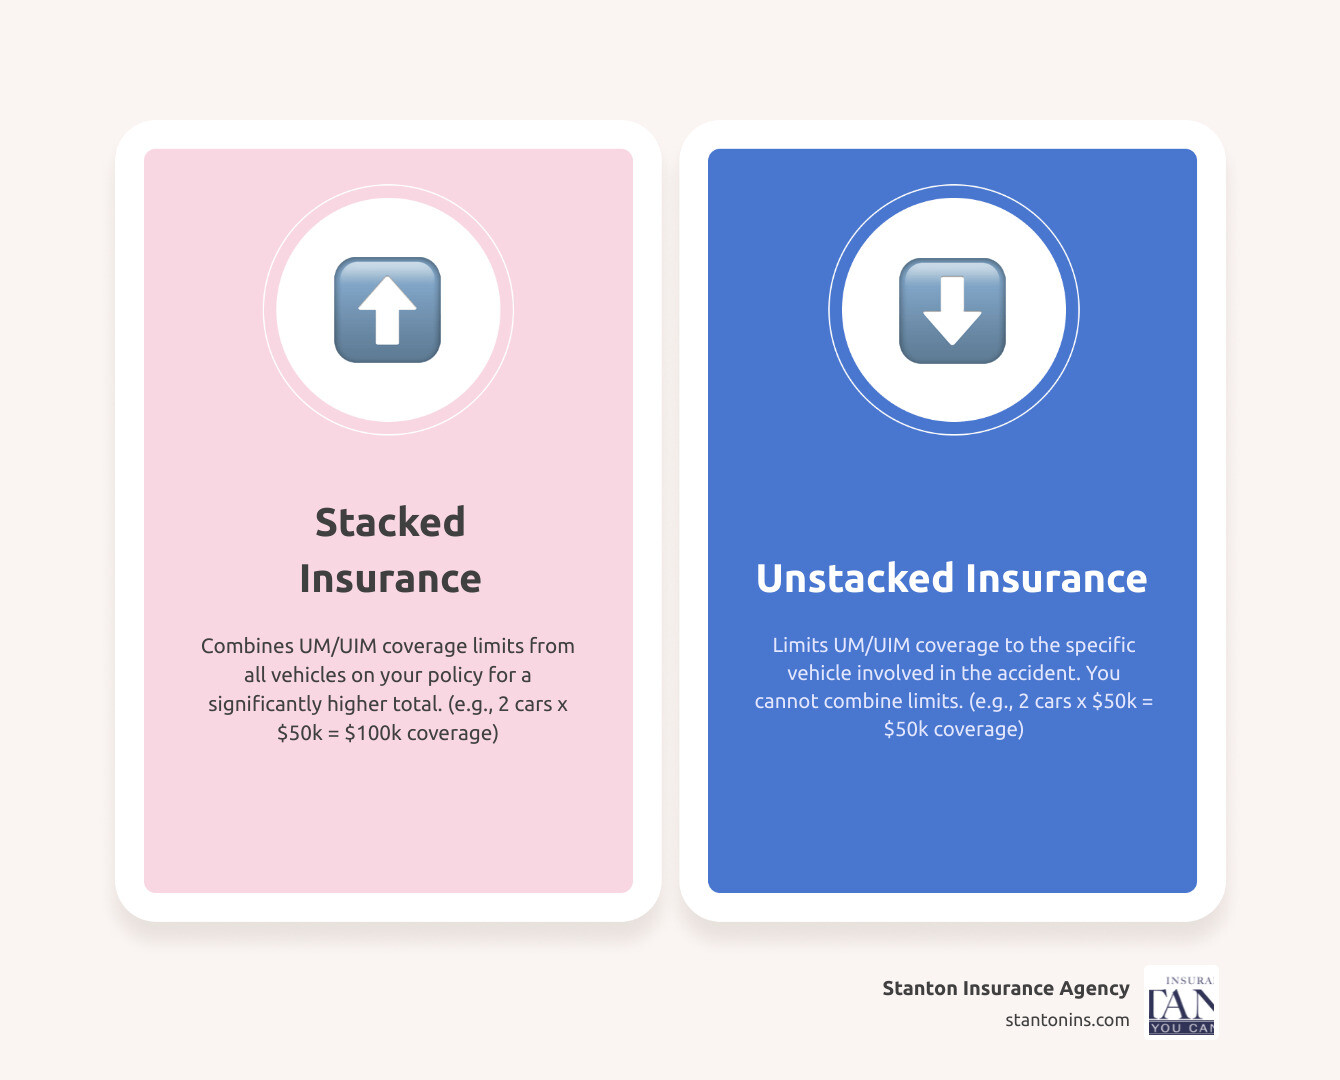
Stacked auto insurance allows you to combine uninsured and underinsured motorist (UM/UIM) coverage limits across multiple vehicles or policies to increase your total protection. Unstacked insurance keeps those limits separate for each vehicle. Following Dave Ramsey’s financial principles, the goal is to secure maximum protection against catastrophic loss through high liability limits and umbrella policies while minimizing unnecessary premiums.
Understanding the difference between stacked and unstacked insurance is a critical component of risk management, particularly for those following a disciplined financial plan. While insurance often feels like a "grudge purchase," it is the primary tool used to transfer risk that you cannot afford to carry yourself. In the context of the Ramsey Baby Steps, insurance serves as the defensive wall that prevents a single car accident from wiping out your emergency fund or derailing your journey toward wealth.
The Fundamentals of UM/UIM Coverage
To understand stacking, one must first understand what is being stacked. Stacking almost exclusively applies to Uninsured Motorist (UM) and Underinsured Motorist (UIM) coverage.
Uninsured Motorist coverage protects you, your passengers, and your vehicle if you are hit by a driver who has no insurance. Underinsured Motorist coverage kicks in when the at-fault driver has insurance, but their liability limits are too low to cover the full extent of your medical bills or property damage.
Dave Ramsey frequently emphasizes the necessity of these coverages because you cannot control the financial responsibility of other drivers. Even in 2026, despite stricter regulations, a significant percentage of drivers remain underinsured relative to the rising costs of medical care and vehicle technology. Without UM/UIM, a major collision could result in hundreds of thousands of dollars in medical debt, even if the accident wasn't your fault.
What is Stacked Auto Insurance?
Stacked insurance is a feature offered in approximately 30 states that allows a policyholder to add together the limits of their UM/UIM coverage. This can occur in two primary ways:
1. Intra-Policy Stacking (Vertical Stacking)
This occurs when you have multiple vehicles listed on a single insurance policy. If you have three cars on one policy and each has $50,000 in UM/UIM coverage, stacking allows you to "stack" those limits to a total of $150,000 of protection for a single accident, regardless of which of the three cars you were driving.
2. Inter-Policy Stacking (Horizontal Stacking)
This occurs when you have vehicles on different policies, perhaps because they are owned by different members of the same household. If you have your own policy and are also covered under a spouse's or parent's policy in the same house, you may be able to stack the limits of both policies to cover your losses.
From a technical standpoint, stacking provides a safety net that scales with the number of vehicles you own. However, this increased protection comes at a cost, as insurance companies charge a higher premium for the privilege of combined limits.
What is Unstacked Auto Insurance?
Unstacked insurance treats each vehicle as an independent entity. If you have three cars with $50,000 in UM/UIM coverage each, and you are involved in an accident while driving Car A, your maximum payout for UM/UIM is limited to that $50,000. You cannot "borrow" the limits from Car B or Car C.
Unstacked coverage is the default in many states and is generally 10% to 15% cheaper than stacked coverage. For those focused on the Ramsey principle of "living on less than you make," the savings from unstacked insurance are often tempting. However, the decision to go unstacked should only be made if your base limits are already high enough to cover a worst-case scenario.
Dave Ramsey’s Financial Philosophy on Insurance
Dave Ramsey’s approach to insurance is rooted in the concept of "Risk Transfer." He teaches that you should insure against the things that would cause a financial catastrophe but "self-insure" (through an emergency fund) against minor inconveniences.
The Role of the Umbrella Policy
One of the most important aspects of the Ramsey perspective is the recommendation for an Umbrella Policy. Once you have a positive net worth or have reached Baby Step 4 (investing 15% for retirement), Ramsey suggests carrying a $1 million umbrella policy.
An umbrella policy sits on top of your auto and homeowners insurance. However, there is a catch: most umbrella policies only provide additional liability coverage (protecting others if you hit them). They do not always provide additional UM/UIM coverage (protecting you if they hit you).
This is where the stacked vs. unstacked debate becomes critical. If your umbrella policy does not include UM/UIM, your primary auto policy's UM/UIM limits are all you have. In that case, stacking becomes a very attractive way to bolster your personal protection without needing a separate high-limit endorsement.
Cost-Benefit Analysis
Ramsey’s team often advises working with an independent insurance provider (sometimes referred to as RamseyTrusted providers) who can shop across multiple carriers. The goal is to find the "sweet spot" where you are fully protected but not "insurance poor." If stacking costs an extra $200 a year but triples your coverage from $100,000 to $300,000, a Ramsey-style analysis would likely favor the stacked option, as the risk-to-reward ratio is high.
Comparing Stacked and Unstacked Insurance
The following table outlines the key differences you will encounter when reviewing your policy options in 2026.
| Feature | Stacked Insurance | Unstacked Insurance |
|---|---|---|
| Limit Calculation | Limits multiplied by number of vehicles. | Limits per individual vehicle only. |
| Premium Cost | Higher (typically 10-20% more for UM/UIM portion). | Lower (baseline rate). |
| Best For | Families with multiple vehicles and low base limits. | Individuals with one car or very high base limits. |
| Availability | Only available in specific "stacking" states. | Available in all states. |
| Household Coverage | Can often cover you in someone else's car. | Limited strictly to the vehicle on the policy. |
| Complexity | More complex legal and policy language. | Straightforward, per-vehicle limits. |
Legal and Jurisdictional Limits
It is vital to note that insurance laws vary significantly by state. In 2026, states like Pennsylvania and Florida remain "stacking-friendly," meaning insurers must offer stacked coverage unless the policyholder explicitly signs a waiver to reject it (choosing unstacked). Other states, like California, do not permit stacking at all.
When you are following the Dave Ramsey plan, you must ensure you are following the specific statutes of your state. If you live in a non-stacking state, your focus should shift toward simply increasing your individual UM/UIM limits to at least $250,000/$500,000 to ensure you have adequate protection.
When Should You Choose Stacked Coverage?
While Dave Ramsey emphasizes saving money, he never emphasizes it at the expense of safety. You should consider opting for stacked coverage in the following scenarios:
- Multiple Vehicles, Low Individual Limits: If your insurance company limits the amount of coverage you can buy per car (e.g., they won't let you go above $100k), stacking three cars allows you to reach a $300k limit effectively.
- You Frequently Ride in Other People's Cars: Stacked coverage often follows the "person" rather than the "car." This means if you are a passenger in a friend’s uninsured vehicle and get into an accident, your stacked UM/UIM from your home policy can provide higher levels of medical coverage.
- High-Risk Driving Environments: If you live in an area with a high percentage of uninsured motorists, the extra premium for stacking is a small price to pay for the peace of mind that you won't be left with a $200,000 hospital bill.
When Should You Choose Unstacked Coverage?
Unstacked coverage isn't necessarily "bad" insurance; it is simply a more focused form of coverage. It may be the right choice if:
- You Only Own One Vehicle: You cannot stack limits if there is only one car on the policy and no other policies in the household. In this case, you are paying for a feature you cannot use.
- You Have Extremely High Base Limits: If your policy already provides $500,000 in UM/UIM coverage and you have a robust umbrella policy that includes UM/UIM, stacking may be redundant.
- Budgetary Constraints in Early Baby Steps: If you are in Baby Step 2 (paying off debt) and every dollar counts, choosing unstacked coverage while maintaining "good enough" limits (like $100k/$300k) might be a temporary way to find extra cash for the debt snowball. However, this is a calculated risk.
Common Mistakes and Misconceptions
One of the biggest mistakes consumers make is assuming that "Full Coverage" includes everything. "Full coverage" is a marketing term, not a legal definition. It usually just means you have liability, collision, and comprehensive insurance. It does not automatically mean you have stacked UM/UIM.
Another misconception is that stacking applies to liability insurance. It does not. If you have $100,000 in liability coverage on three cars, you do not have $300,000 in liability. Stacking is almost exclusively reserved for the protection of the policyholder (UM/UIM).
Finally, many people fail to update their stacking status when they add or remove vehicles from their household. In 2026, with the prevalence of digital-first insurance apps, it is easy to overlook the "Stacking Waiver" toggle. Always verify that your coverage reflects your current fleet size.
Practical Steps for 2026 Policy Reviews
To align your auto insurance with the Ramsey philosophy this year, follow these steps:
- Step 1: Audit your current limits. Look for "Uninsured Motorist Bodily Injury." See if it is marked as "Stacked" or "Non-Stacked."
- Step 2: Check your state laws. Confirm if stacking is even an option in your jurisdiction.
- Step 3: Get a quote for both. Ask your agent for the price difference. If the difference is less than $15 a month and you have multiple cars, stacking is usually the superior choice.
- Step 4: Evaluate your Umbrella Policy. Ensure your total protection (Auto + Umbrella) covers your net worth and potential loss of income.
- Step 5: Consult an independent agent. Avoid "captive" agents who only sell one brand. An independent agent can find carriers that offer more favorable stacking terms.
FAQ
Does Dave Ramsey explicitly recommend stacked insurance? Dave Ramsey recommends having enough insurance to transfer risk. He does not always specify "stacked" vs "unstacked," but he does advocate for high UM/UIM limits. If stacking is the most cost-effective way to get your coverage to the $250k or $500k level, it fits perfectly within his framework.
Is unstacked insurance ever a better deal? Yes, if you own only one vehicle or if the cost of stacking is disproportionately high compared to the benefit. If you can simply increase your per-vehicle limits for a lower price than stacking, that is the mathematically superior move.
Does stacking cover property damage or just medical? In most states, stacking applies to Uninsured Motorist Bodily Injury (UMBI). While some states allow for Uninsured Motorist Property Damage (UMPD) stacking, it is less common. Most stacking debates focus on the medical and pain/suffering side of a claim.
Can I stack across different insurance companies? Generally, no. Stacking usually requires the vehicles to be on the same policy or multiple policies with the same insurance company or affiliated companies within the same household.
What happens if I sign a stacking waiver? By signing a stacking waiver, you are officially choosing unstacked insurance. This usually results in a lower premium, but it legally limits your recovery to the single-vehicle limit stated on your policy.
Final Recommendation
When navigating auto insurance stacked vs. unstacked in 2026, do not make the mistake of looking only at the monthly premium. Following the Dave Ramsey methodology means being "gazelle intense" about your finances, which includes protecting your assets from the negligence of others.
If you live in a state where stacking is available and you have multiple vehicles, choose stacked coverage unless your unstacked limits are already significantly higher than your total net worth and potential medical liabilities. The goal is to ensure that no matter which car you are in, you have a massive financial shield between you and the uninsured world.
Image Gallery
Select an image to open it in a new tab.
Omar Farooq
EdTech Innovation and Virtual Pedagogy Journalist
