To swap auto insurance, you must first secure a new policy and then cancel your existing one, ensuring there is no gap in coverage. The process involves comparing quotes, purchasing a new plan with an effective date that matches or slightly precedes your old policy’s expiration, and formally notifying your previous insurer to avoid a lapse that could trigger legal penalties or higher future premiums.
Swapping auto insurance is a routine financial move that can save drivers hundreds of dollars annually, yet many policyholders remain with the same carrier for years out of a perceived fear of complexity. In 2026, the insurance landscape has become increasingly digitized, allowing for nearly instantaneous transitions. However, the fundamental principles of maintaining continuous coverage and understanding your policy's fine print remain as critical as ever. Whether you are seeking a lower premium, better customer service, or coverage that better reflects your current lifestyle, the following guide details the technical and practical steps required to navigate a successful transition.
Understanding the Difference Between Swapping and Renewing
Before initiating a swap, it is essential to distinguish between a policy renewal and a carrier switch. A renewal occurs when you stay with your current insurer but update your terms or accept a new premium for the next six- or twelve-month term. Swapping, or switching, involves terminating your relationship with Carrier A and beginning a new contract with Carrier B.
You do not need to wait until your current policy period ends to make a switch. Most insurance contracts allow for mid-term cancellation. While some companies may charge a small administrative "short-rate" fee for early cancellation, the potential savings from a new provider often outweigh these costs. In the current 2026 economic environment, where inflation and repair costs impact premiums, regularly evaluating your "swap potential" is a key component of proactive financial management.
Step 1: Evaluate Your Current Coverage and Needs
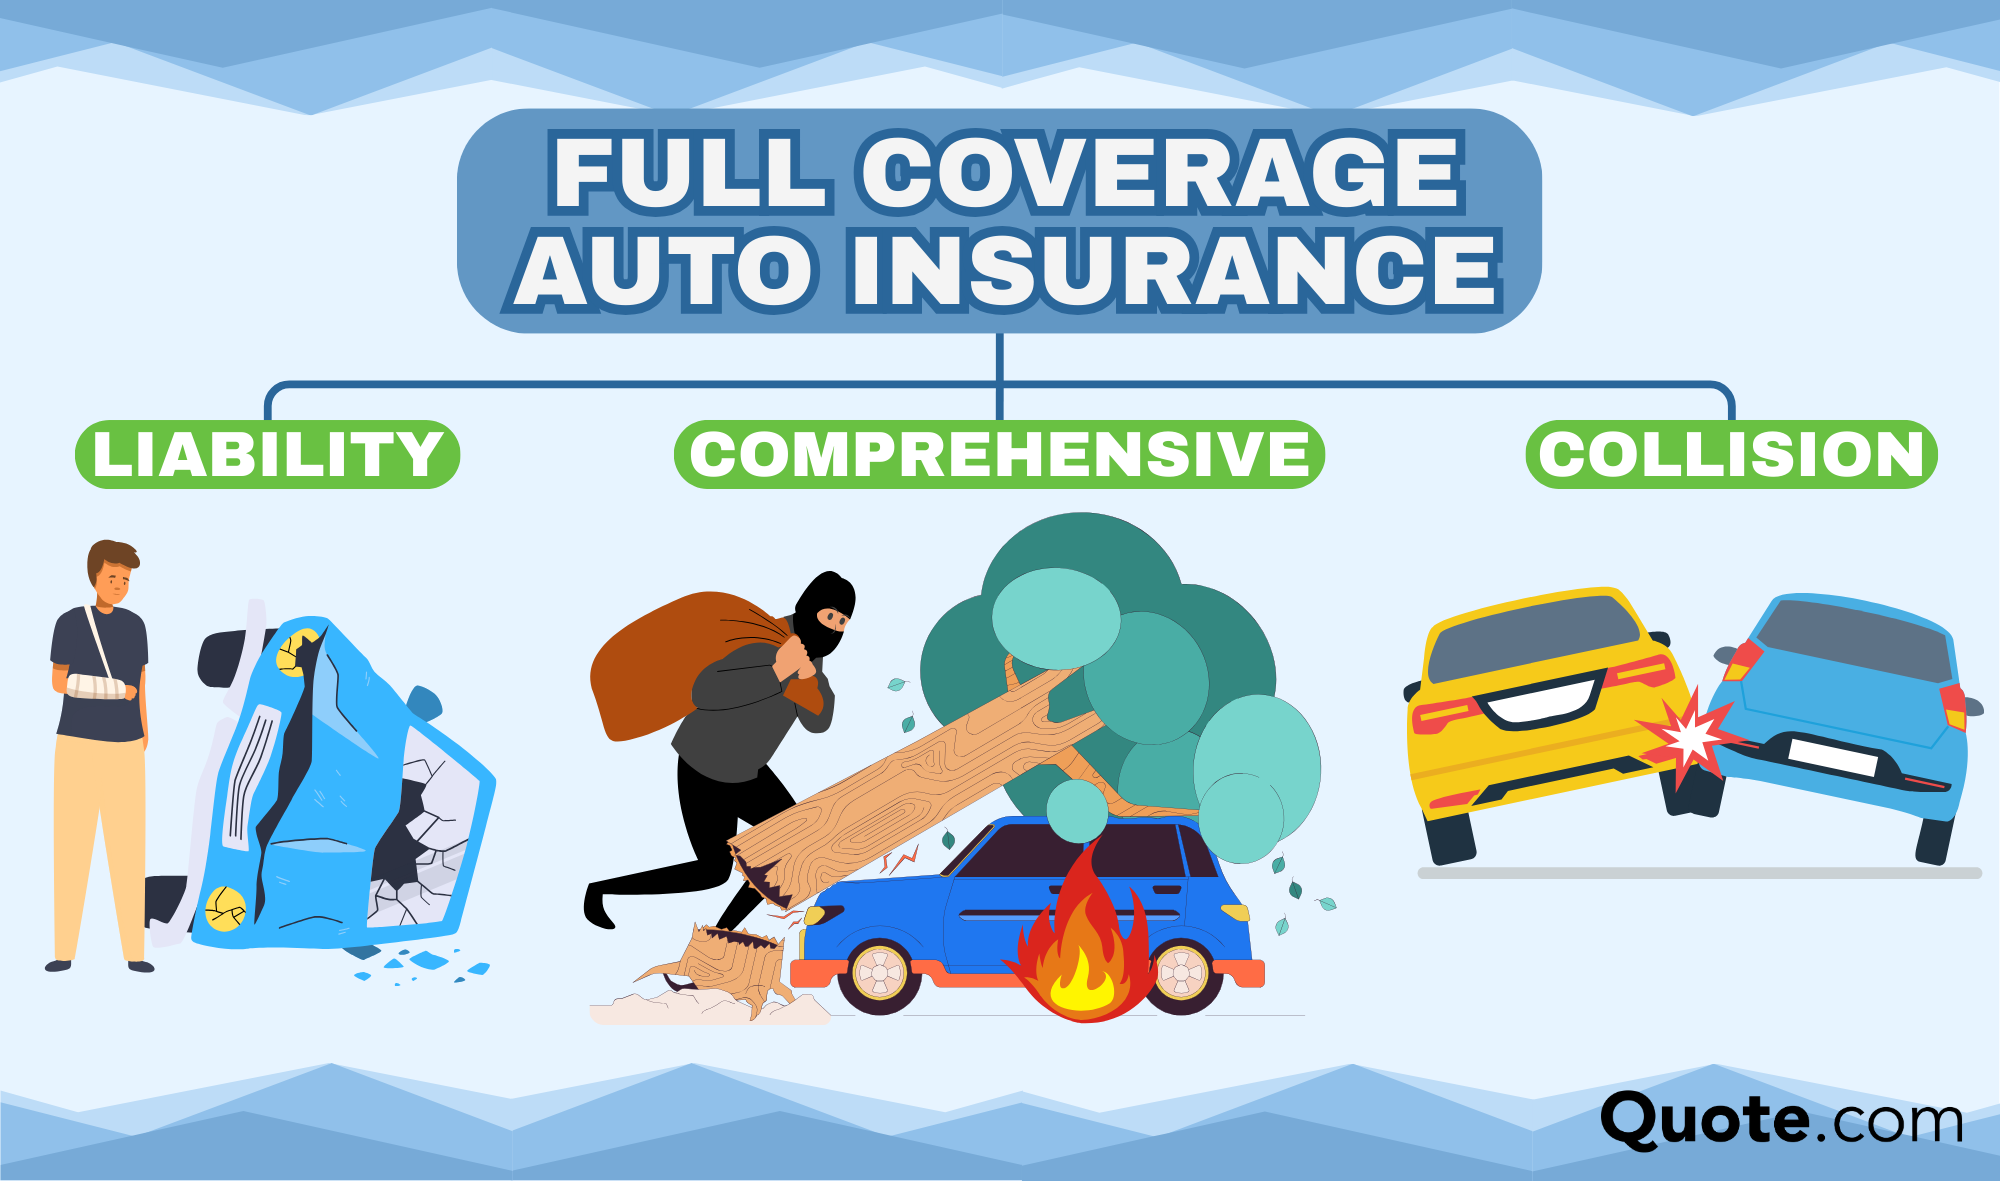
The most common mistake drivers make when swapping insurance is failing to understand exactly what they are replacing. To ensure an "apples-to-apples" comparison, you must review your current Declarations Page (often called a "Dec Page"). This document summarizes your coverage limits, deductibles, and any specific endorsements you currently carry.
Key Metrics to Review:
- Liability Limits: This includes Bodily Injury and Property Damage. In 2026, many experts recommend limits higher than state minimums (e.g., $100,000/$300,000/$100,000) due to the rising cost of medical care and vehicle replacement.
- Comprehensive and Collision Deductibles: If you are driving an older vehicle, you might consider increasing these deductibles to lower your premium, or removing them entirely if the vehicle's value is negligible.
- Uninsured/Underinsured Motorist Coverage: This protects you if you are hit by a driver with insufficient insurance—a scenario that remains prevalent in many jurisdictions.
- Add-ons: Review services like roadside assistance, rental car reimbursement, and gap insurance.
Step 2: Research and Compare New Carriers
With your current coverage as a baseline, begin gathering quotes. In 2026, the use of AI-driven comparison tools and telematics has made this process faster, but due diligence is still required.
Evaluating Financial Strength
Price should not be your only metric. A lower premium is useless if the company lacks the financial stability to pay out a major claim. Check the financial strength ratings of potential insurers through independent agencies such as A.M. Best or Moody's. A rating in the "A" category (A-, A, A+, A++) indicates an excellent ability to meet ongoing insurance obligations.
Checking Complaint Ratios
Visit the National Association of Insurance Commissioners (NAIC) to view the "Complaint Index" for any company you are considering. This index compares a company's performance against the industry average based on its market share. A score below 1.00 indicates fewer complaints than average, suggesting better customer service and claims handling.
Step 3: Purchase the New Policy Before Cancelling the Old One
This is the most critical technical step in the process. Never cancel your old policy until you have a signed, active contract with your new insurer.
A "coverage lapse"—even for a single day—can have significant consequences. State Departments of Motor Vehicles (DMVs) are often electronically notified of insurance cancellations. If they do not see a corresponding new policy on file immediately, you could face:
- Suspension of Registration: Your vehicle may be flagged as illegal to drive.
- Increased Premiums: Future insurers view a lapse as a high-risk indicator, often leading to significantly higher rates for years to come.
- Legal Penalties: Fines and the requirement to file an SR-22 (a certificate of financial responsibility) in some states.
When setting the effective date for your new policy, choose the same day your old one is set to expire, or even one day prior to ensure there is zero chance of a gap during the transition.
Step 4: Formally Cancel Your Old Policy
Once your new policy is in force and you have received your new insurance identification cards, contact your previous insurer to cancel. Do not simply stop paying your premiums. "Non-payment" is not the same as a formal cancellation. If you simply stop paying, the insurer may cancel your policy for non-payment, which negatively impacts your credit-based insurance score and makes it harder to get affordable rates in the future.
Most companies require a written or verbal "notice of cancellation." Ask for a cancellation confirmation number and inquire about a pro-rated refund. If you paid your six-month premium in full and are only two months into the term, the company is legally obligated to return the unused portion of your premium (minus any applicable early termination fees).
Step 5: Notify Relevant Third Parties
If you do not own your vehicle outright, you have additional obligations when swapping insurance.
- Lienholders and Lessors: If you have an auto loan or a lease, the financial institution is listed as a loss payee on your policy. They require specific coverage levels (usually full comprehensive and collision with a maximum deductible of $500 or $1,000). You must notify your lender of the carrier swap and provide them with the new policy number and company details. Failure to do so may result in the lender purchasing "force-placed insurance," which is significantly more expensive and provides less protection.
- State DMV: In most cases, your new insurer will handle the electronic notification to the state. However, it is prudent to check your state's online portal a week after the swap to ensure your vehicle is listed as properly insured.
Comparison of 2026 Auto Insurance Policy Models
As you swap, you may encounter different types of policy structures. Understanding these helps you choose the right model for your driving habits.
| Policy Type | Best For | How it Works | Primary Benefit |
|---|---|---|---|
| Traditional Fixed Rate | Predictable drivers | Premium is set for 6-12 months based on static risk factors (age, location, vehicle). | Consistent monthly or semi-annual budgeting. |
| Usage-Based (UBI) | Safe, low-mileage drivers | An app or plug-in device tracks braking, speed, and time of day to adjust rates. | Potential for massive discounts for safe driving habits. |
| Pay-Per-Mile | Remote workers / City dwellers | You pay a low base rate plus a few cents per mile driven each month. | You only pay for the actual "risk" time you spend on the road. |
| Bundled Policy | Homeowners / Multiple car owners | Combining auto with home, renters, or life insurance under one carrier. | Significant multi-policy discounts (often 10% to 25%). |
Common Pitfalls to Avoid During a Swap
Even experienced drivers can encounter issues when switching providers. Being aware of these technical nuances can prevent financial headaches.
1. Forgetting to Update Telematics Equipment
If your old policy relied on a physical plug-in device for a telematics discount, you must return that device to the old insurer. If you are moving to a new telematics-based policy, ensure the new app is installed and permissions (like GPS and motion sensing) are correctly configured on your smartphone immediately upon the policy's start date.
2. Overlooking Automatic Payments
If you had "Auto-Pay" set up with your old insurer, double-check that the authorization is revoked. It can take one or two billing cycles for these systems to stop, potentially leading to an unwanted withdrawal after you have already swapped.
3. Ignoring the "Step-Down" Provision
Some low-cost insurers include a "step-down" provision in their contracts. This means that if someone not listed on the policy drives your car and gets into an accident, the coverage "steps down" to the state minimum regardless of the higher limits you purchased. When swapping to a "budget" carrier, read the policy exclusions carefully to ensure you aren't losing critical protections.
4. Not Printing New ID Cards
While most states accept digital insurance cards on a smartphone in 2026, it is still a best practice to keep a physical copy in the glovebox. If your phone battery dies or you are in an area with no cellular reception during a traffic stop or accident, a physical card is your only proof of coverage.
Frequently Asked Questions
Can I swap auto insurance if I have an open claim?
Yes, you can switch insurance carriers even if you have an open claim with your current company. The company that was providing coverage at the exact time of the accident is legally responsible for handling and paying out that specific claim, regardless of whether you remain a customer. Your new insurer will not take over the old claim, but they will consider the accident when calculating your new premium.
Will swapping insurance frequently hurt my credit score?
Swapping insurance itself does not directly impact your "FICO" credit score. However, many insurers use a "credit-based insurance score" to determine your rates. Frequent switching doesn't lower this score, but failing to pay your final bill or being cancelled for non-payment can lead to collections, which will damage your credit. Some insurers also offer "loyalty discounts," which you may lose by switching too often.
Is there a "best time" of year to swap?
While you can swap anytime, the most advantageous time is typically 30 days before your current policy expires. This gives you enough time to shop around without the pressure of an immediate deadline. Additionally, many insurers offer "early bird" discounts if you sign up for a new policy at least 7 to 14 days before the effective date.
Do I get a refund if I swap in the middle of a month?
Yes. Auto insurance is a "pre-paid" service. If you cancel your policy mid-term, the insurer must refund the "unearned premium." This is the portion of the payment that covers the period after your cancellation date. Be aware that some companies may deduct a small cancellation fee, often around $25 to $50, or a "short-rate" percentage (usually 10% of the remaining premium).
What documents do I need to provide to my new insurer?
To get an accurate quote and finalize a swap in 2026, you generally need the Vehicle Identification Number (VIN) for all cars, the driver’s license numbers for all household members of driving age, your current policy's Declarations Page, and an accurate estimate of your annual mileage. The insurer will pull your Motor Vehicle Report (MVR) and claims history (Clue report) automatically.
Practical Recommendation for 2026
If you are considering a swap, start by requesting a copy of your CLUE (Comprehensive Loss Underwriting Exchange) report. This report contains a seven-year history of your auto insurance claims. Reviewing this before you shop ensures that you can provide accurate information to new carriers, preventing "rate surprises" where a quote is adjusted upward after the company runs your official background check. Once you have identified a carrier with a strong A.M. Best rating and a lower premium, purchase the policy to start on the final day of your current term, notify your lender, and then send a formal cancellation email to your old agent. This systematic approach ensures financial protection and legal compliance throughout the transition.
Image Gallery
Select an image to open it in a new tab.
Akira Tanaka
International Academic Trends Correspondent
