Why is the Real Estate Market Crashing? Understanding the 2026 Housing Correction
The real estate market is currently experiencing a significant correction driven by the cumulative impact of prolonged high interest rates, a sudden surge in housing inventory, and a critical disconnect between stagnant wages and record-high property valuations. This downturn represents a stabilization phase where overvalued markets are finally adjusting to reduced buyer demand and tightened lending standards.
For years, the narrative surrounding the housing market was one of "perpetual growth." However, as we move through 2026, the landscape has shifted dramatically. While many economists hesitate to use the word "crash" due to the lack of systemic subprime failures seen in 2008, the current price retreats in several major metropolitan areas feel like a collapse to homeowners who purchased at the 2022-2024 peak. Understanding the mechanics of this downturn requires an analysis of several interlocking economic factors, from Federal Reserve policy to shifts in demographic behavior.
The Lag Effect of Monetary Policy and Interest Rates
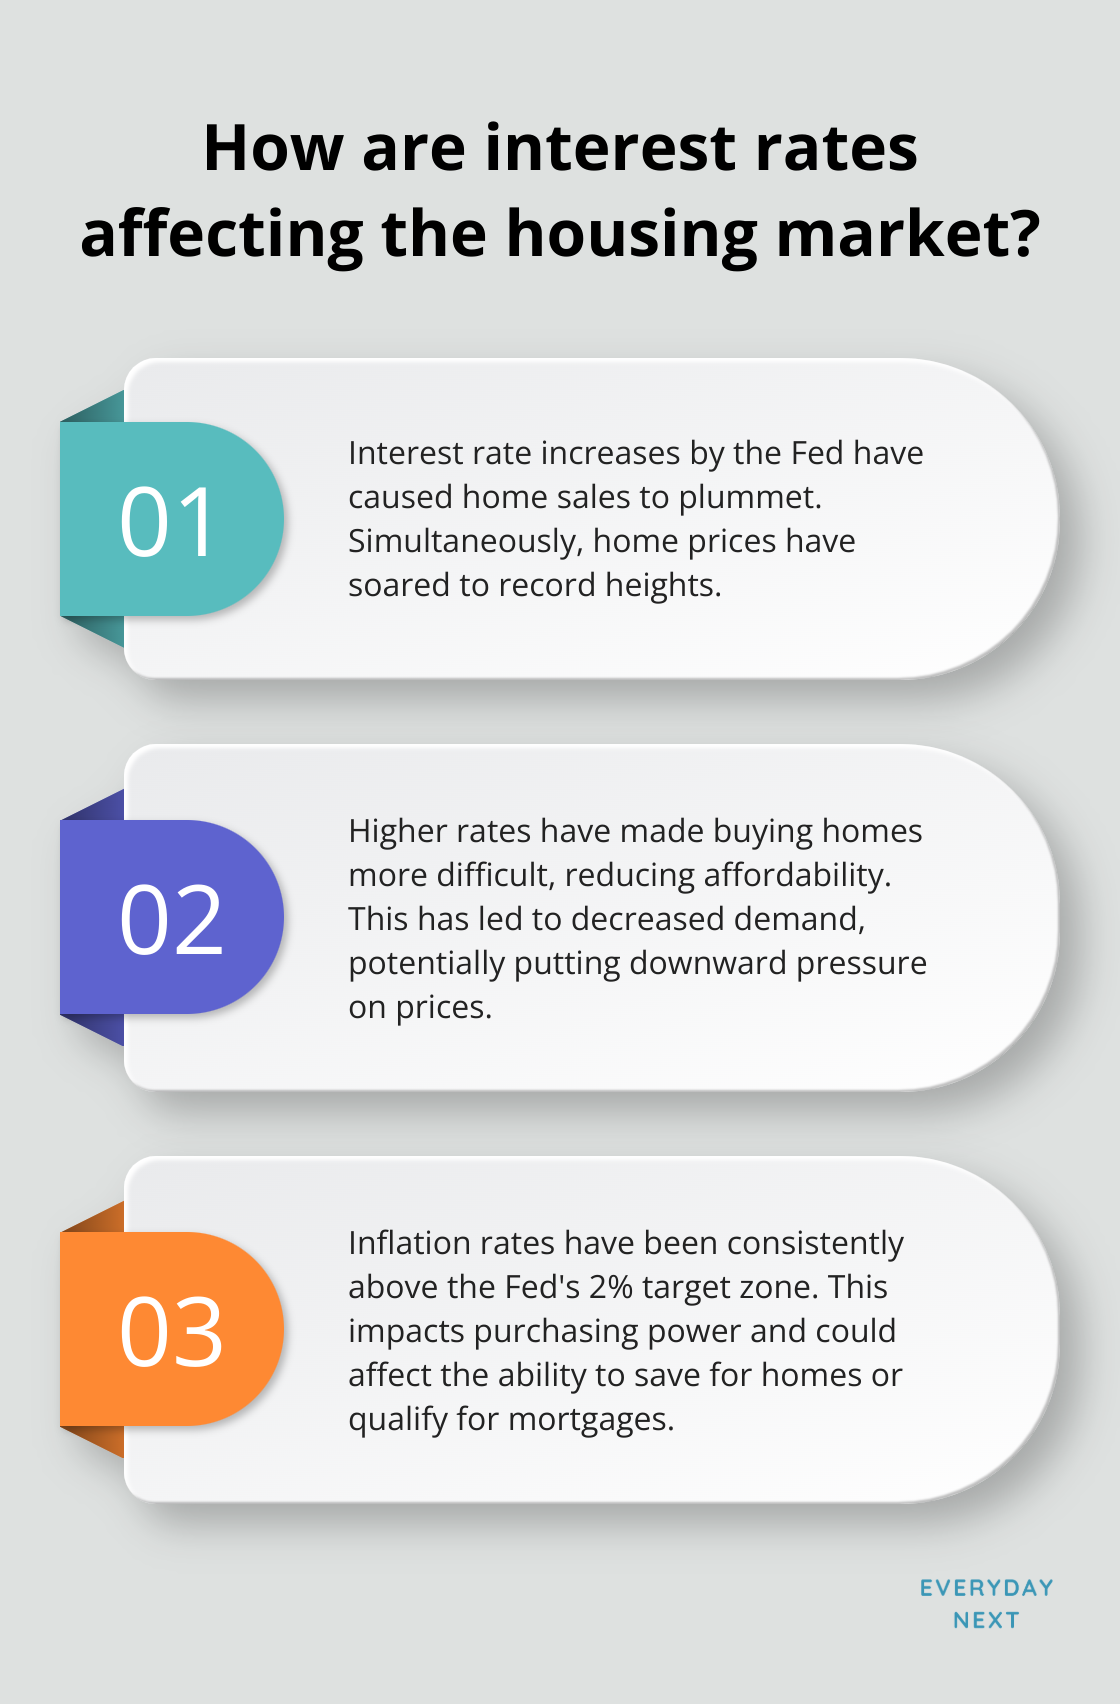
The most direct catalyst for the 2026 real estate downturn is the delayed impact of the Federal Reserve’s aggressive interest rate hikes that began years earlier. Monetary policy is often described as having "long and variable lags." The high-rate environment established to combat inflation in 2023 and 2024 eventually broke the "lock-in effect," where homeowners refused to sell because they didn't want to trade a 3% mortgage for a 7% or 8% rate.
By 2026, life events—such as job transfers, divorces, and the "Silver Tsunami" of aging retirees—have forced many of these "locked-in" homeowners to finally list their properties. This influx of supply met a buyer pool that had been decimated by high borrowing costs. According to data from the Federal Reserve Bank of St. Louis, the resulting spike in the monthly cost of homeownership has pushed the debt-to-income (DTI) ratios of prospective buyers to unsustainable levels, forcing sellers to lower prices to find qualified applicants.
Furthermore, the cost of capital has influenced more than just mortgages. Real estate developers who relied on floating-rate construction loans have seen their debt service costs double. As these projects reach completion in 2026, many developers are forced to sell units quickly—even at a discount—to satisfy their lenders and avoid foreclosure. This "forced selling" at the institutional level adds downward pressure on the entire market.
The Surge in Housing Inventory and the End of Scarcity
For nearly a decade, the primary defense against a housing crash was the "lack of inventory." In 2026, that defense has crumbled. Several factors have converged to create a surplus of available homes in regions that previously faced extreme shortages.
- Completion of Backlogged Construction: The massive wave of housing starts that began in 2024, spurred by government incentives and a temporary dip in lumber prices, has finally hit the market. These new builds are competing directly with existing homes, often offering modern amenities and builder-subsidized financing that individual sellers cannot match.
- The Short-Term Rental Sell-Off: Legislative crackdowns on short-term rentals (STRs) in major cities and popular vacation destinations have reached a boiling point. As municipalities enforced stricter zoning and tax laws, the "Airbnb gold rush" slowed. Many investors who bought properties at inflated prices found that their rental income no longer covered their high-interest mortgages, leading to a wave of "investor liquidations."
- Institutional Deleveraging: Large institutional investors and Real Estate Investment Trusts (REITs), which were responsible for a significant percentage of home purchases between 2020 and 2023, have begun rebalancing their portfolios. Faced with better returns in the bond market and high maintenance costs, some of these entities have shifted from "accumulate" to "sell" mode, dumping thousands of single-family homes back into the retail market.
The Commercial Real Estate Contagion
While the residential market is the primary concern for most individuals, the "crash" is being exacerbated by a deep crisis in the commercial real estate (CRE) sector. The 2026 fiscal year has seen a record number of commercial mortgage-backed securities (CMBS) reach maturity. With office vacancy rates remaining at historic highs due to the permanence of hybrid work, many office building owners are unable to refinance their debt.
This CRE crisis spills over into the residential market through two main channels:
- Regional Bank Instability: Regional banks hold a disproportionate amount of commercial real estate debt. As defaults rise, these banks are forced to tighten their lending standards across the board, including for residential mortgages and home equity lines of credit (HELOCs). This "credit crunch" makes it harder for even well-qualified buyers to secure a loan.
- Urban Devaluation: As downtown office corridors struggle with high vacancy and reduced foot traffic, the surrounding residential neighborhoods lose their "live-work-play" appeal. This has led to a localized but severe "crashing" of prices in luxury condo markets in cities like San Francisco, Chicago, and New York.
Comparing the 2008 Financial Crisis vs. 2026 Market Correction
It is essential to distinguish the current environment from the Great Recession. While the price drops in 2026 are significant, the underlying mechanics differ. The 2008 crash was built on a foundation of fraudulent lending and systemic risk. The 2026 correction is primarily a valuation and affordability crisis.
| Feature | 2008 Financial Crisis | 2026 Market Correction |
|---|---|---|
| Primary Driver | Subprime mortgages & predatory lending | High interest rates & affordability gap |
| Lending Standards | Extremely loose (NINJA loans) | Strict (High credit score requirements) |
| Foreclosure Type | Strategic defaults and inability to pay | Forced sales due to relocation/deleveraging |
| Inventory Source | Mass bank repossessions | New construction & investor liquidations |
| Government Response | Massive bank bailouts | Targeted rate cuts and housing subsidies |
| Impacted Sector | Entire global financial system | Regionally specific housing/commercial hubs |
As the table illustrates, the 2026 market is more "rational" in its decline. It is a market returning to its mean after a period of unsustainable exuberance. According to the National Association of Realtors (NAR), while median prices have dropped, most homeowners still possess significant equity, which prevents the "avalanche" of foreclosures seen in 2008.
The Affordability Gap and the New Economic Reality
The most fundamental reason the market is crashing is that the average American can no longer afford the average home. Between 2020 and 2025, home prices outpaced wage growth by nearly 3-to-1 in many states. Even with the recent price drops, the "entry-level" home remains a myth in much of the country.
In 2026, the "Price-to-Income Ratio" has reached levels that historically precede prolonged market stagnation or decline. When a generation of first-time buyers is priced out, the "housing ladder" stops moving. Existing homeowners cannot sell their "starter homes" to move up to "forever homes" because there are no buyers at the bottom of the chain. This gridlock eventually resolves through price concessions—the "crash" we are currently witnessing.
Furthermore, the rising cost of homeownership is not just about the mortgage. Homeowners' insurance premiums and property taxes have skyrocketed. In states like Florida and California, insurance costs have become a primary driver of home sales, as many residents can no longer afford the carrying costs of their property regardless of their mortgage rate. The Federal Housing Finance Agency (FHFA) has noted that these non-mortgage costs are increasingly factored into "crashing" valuations in high-risk zones.
Regional Variations: Where the Crash is Deepest
The 2026 real estate crash is not uniform across the United States. While some areas are seeing modest 5% corrections, others are seeing 20-25% drops from their pandemic-era peaks.
- The Sun Belt "Boomtowns": Cities like Austin, Phoenix, and Boise—which saw the highest appreciation during the 2021-2022 migration wave—are now seeing the sharpest declines. The rapid influx of remote workers has slowed, and the local economies cannot support the high home prices that transplants brought with them.
- The Florida Insurance Crisis: Florida's market is facing a unique "triple threat": high interest rates, a surplus of new condo inventory, and an insurance market in near-collapse. This has led to a significant "crash" in older condo units that require expensive structural certifications and skyrocketing insurance premiums.
- The Midwest Resilience: Conversely, markets in the Midwest (e.g., Indianapolis, Columbus, St. Louis) remain relatively stable. Because these areas never experienced the "bubble" pricing of the coasts, they have less room to fall.
Practical Recommendations for Navigating the 2026 Market
For those involved in the real estate market today, the strategy must shift from "aggressive growth" to "capital preservation."
- For Buyers: Do not attempt to "catch a falling knife." While prices are lower than they were two years ago, wait for signs of stabilization in inventory levels. Ensure your employment is secure, as a housing downturn is often accompanied by broader economic cooling.
- For Sellers: If you must sell, price your home 5-10% below the most recent comparable sale in your neighborhood. In a declining market, "chasing the market down" is a common mistake. Being the most competitively priced home on the first day of listing is the only way to attract the limited pool of qualified buyers.
- For Investors: Focus on "cash flow" rather than "appreciation." The days of buying a property and expecting a 10% value increase in 12 months are over for this cycle. If the rental income doesn't comfortably cover the PITI (Principal, Interest, Taxes, and Insurance), walk away.
- For Current Homeowners: If you have a low-interest mortgage and no immediate need to move, the best course of action is to stay put. Your home remains a functional asset (a place to live), even if its "on-paper" value has decreased.
Frequently Asked Questions
Is the 2026 real estate crash worse than 2008?
No, in terms of systemic financial risk, 2026 is less severe. In 2008, the crash was caused by a collapse of the banking system due to bad loans. In 2026, the "crash" is a correction of overvalued assets. Lending standards remain much higher today, meaning most homeowners are not "underwater" (owing more than the home is worth), though their equity has decreased significantly.
Will home prices return to 2020 levels?
It is unlikely that national median prices will return to 2020 levels in the short term. However, when adjusted for inflation, many markets are effectively seeing 2020-equivalent pricing. Some specific overbuilt markets (like parts of the Sun Belt) may see nominal prices dip close to those levels, but a broad national return to 2020 prices would require a much more severe economic depression.
How long will this housing market downturn last?
Real estate cycles move slowly. Historically, housing corrections take 3 to 5 years to find a "floor." Given that the 2026 downturn became pronounced in late 2025, we may not see a true recovery in prices until 2028 or 2029, depending on how quickly the Federal Reserve decides to ease monetary policy.
Should I wait to buy a home until 2027?
Waiting can be a viable strategy if you are in a high-priced market with rising inventory. However, "timing the market" is difficult. The best time to buy is when you are financially stable, plan to stay in the home for at least 7-10 years, and can find a property where the monthly payment is sustainable for your budget.
How do high interest rates cause a crash?
High rates decrease "purchasing power." For every 1% increase in mortgage rates, a buyer's purchasing power drops by approximately 10%. If rates go from 3% to 7%, a buyer who could afford a $500,000 home can now only afford a $350,000 home for the same monthly payment. If sellers don't lower their prices to meet this new reality, the market "crashes" as sales volume disappears.
The Path Forward: Stability Over Speculation
The "crash" of the 2026 real estate market is ultimately a painful but necessary recalibration. The era of "easy money" and double-digit annual appreciation was an anomaly, not the norm. As the market settles, the focus will return to housing as a utility—a place to live—rather than a speculative financial vehicle. For those with a long-term perspective and disciplined financial habits, this downturn provides an eventual entry point into a more balanced and sustainable housing economy.
Image Gallery
Select an image to open it in a new tab.
Lars Thomsen
Global Labor Markets and Economic Strategy Editor
