In 2026, the average cost of auto insurance in Pennsylvania is approximately $2,450 per year for full coverage and $720 per year for minimum liability coverage. These rates fluctuate based on your choice of tort rights, your specific zip code, and the individual underwriting algorithms of Pennsylvania's top-rated insurance carriers.
Pennsylvania remains a complex state for automotive insurance due to its "choice no-fault" system and the significant premium disparities between urban centers like Philadelphia and rural counties in the northern tier. Understanding these costs requires a deep dive into the state's unique legal requirements, the factors that dictate individual premiums, and the strategic choices drivers must make regarding their level of protection.
Pennsylvania’s Minimum Insurance Requirements and Costs
The baseline cost of insurance in Pennsylvania is dictated by the state's mandate for minimum coverage. Every driver must carry a policy that includes medical benefits, bodily injury liability, and property damage liability. As of 2026, these limits remain among the lowest in the nation, which often results in lower "sticker prices" for minimum policies but leaves drivers significantly exposed to financial risk.
The mandatory minimums are:
- Medical Benefits: $5,000 for you and others covered on your policy regardless of fault.
- Bodily Injury Liability: $15,000 per person and $30,000 per accident.
- Property Damage Liability: $5,000 per accident.
While a driver can secure a policy with these limits for roughly $60 per month, insurance professionals rarely recommend them. The $5,000 property damage limit is particularly concerning in 2026, as the average cost of a new vehicle exceeds $50,000. If you are found at fault in a multi-vehicle accident or hit a late-model car, you will be personally liable for any damages exceeding that $5,000 threshold.
The Choice No-Fault System: Full Tort vs. Limited Tort
The single most unique factor influencing the cost of auto insurance in Pennsylvania is the choice between Full Tort and Limited Tort. This selection is a legal requirement on every Pennsylvania insurance application and significantly impacts your premium.
Limited Tort Coverage
Choosing Limited Tort can save a driver between 15% and 40% on their liability premium. By selecting this option, you waive your right to sue for "pain and suffering" and other non-monetary damages unless your injuries meet a specific threshold of "serious injury," which typically involves permanent impairment or significant scarring. It does not limit your ability to sue for out-of-pocket medical expenses or lost wages.
Full Tort Coverage
Full Tort is the more expensive option but offers unrestricted rights to seek financial compensation for pain and suffering caused by an at-fault driver. In 2026, the premium difference for an average family policy can range from $200 to $500 per year. Drivers in high-traffic areas like Pittsburgh or Allentown often opt for Full Tort to ensure they have the broadest legal recourse in the event of a life-altering accident.

Regional Cost Disparities in Pennsylvania
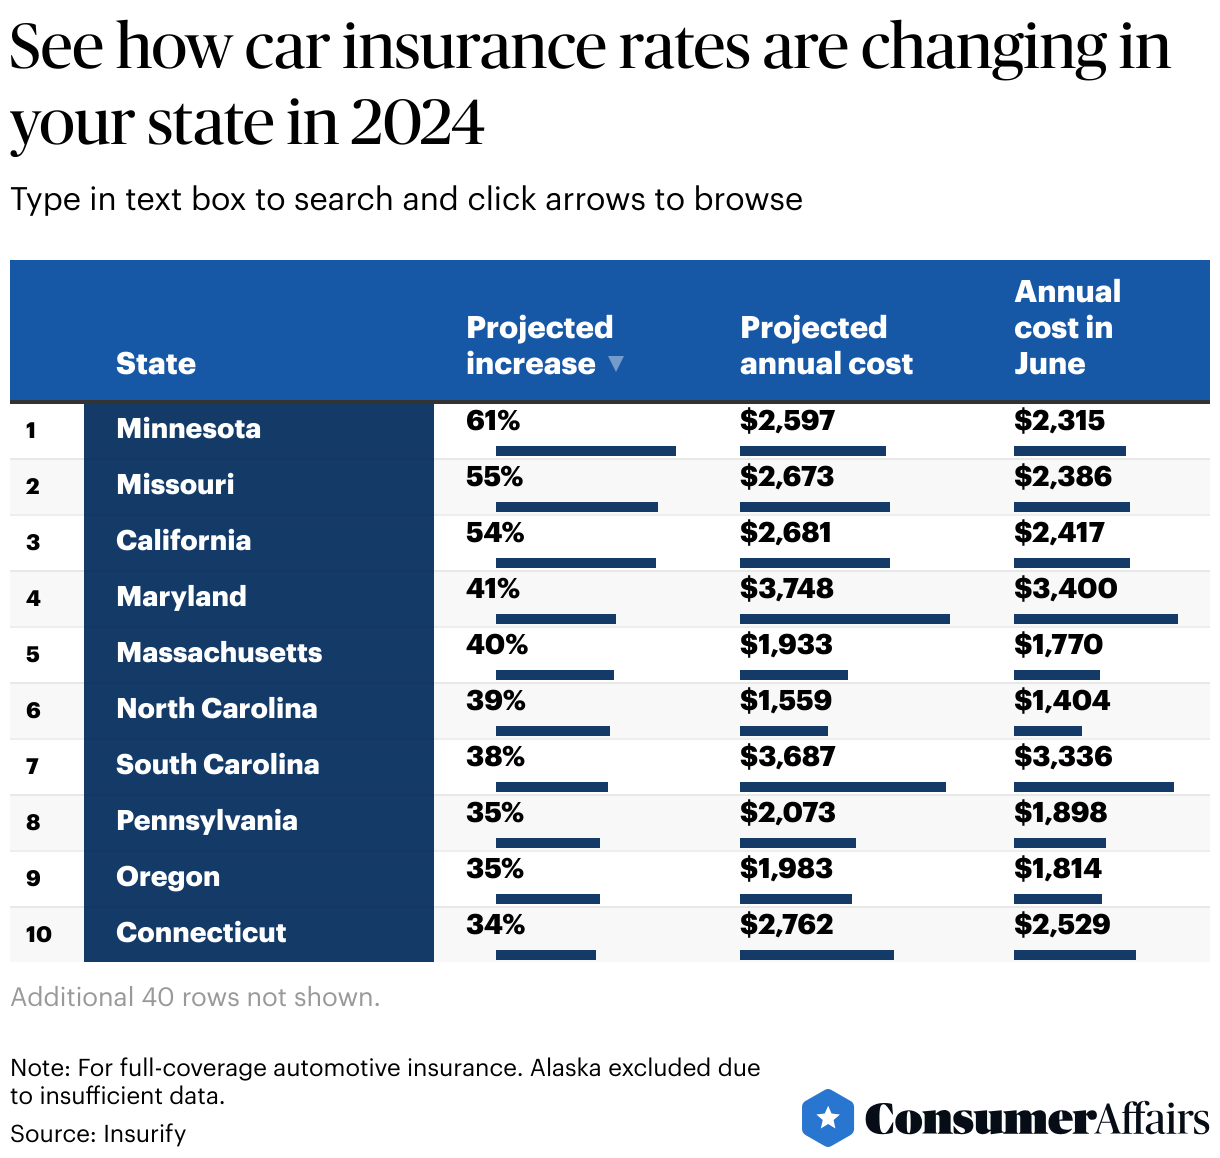
Geography is one of the most powerful variables in the Pennsylvania insurance market. The state features a massive gap between the highest and lowest-cost areas, driven primarily by population density, litigation rates, and the frequency of uninsured motorist claims.
- Philadelphia: Drivers in Philadelphia often pay 50% to 100% more than the state average. The city’s high rates of vehicle theft, dense traffic patterns, and historically high litigation costs make it one of the most expensive cities in the United States for auto insurance. In 2026, a full coverage policy in certain Philly zip codes can exceed $4,500 annually.
- Pittsburgh: Rates in the Steel City are much closer to the state average. While higher than rural areas due to commute times and winter weather accidents, Pittsburgh remains significantly more affordable than Philadelphia.
- Harrisburg and Central PA: These regions benefit from moderate traffic and lower crime rates, typically seeing annual premiums between $1,800 and $2,200 for full coverage.
- Rural Counties: In areas like Potter, Tioga, or Sullivan counties, insurance is at its most affordable. Lower accident frequency and fewer claims for vandalism or theft allow carriers to offer premiums as low as $1,400 for full coverage.
Average Annual Premiums by Major Carrier in PA (2026)
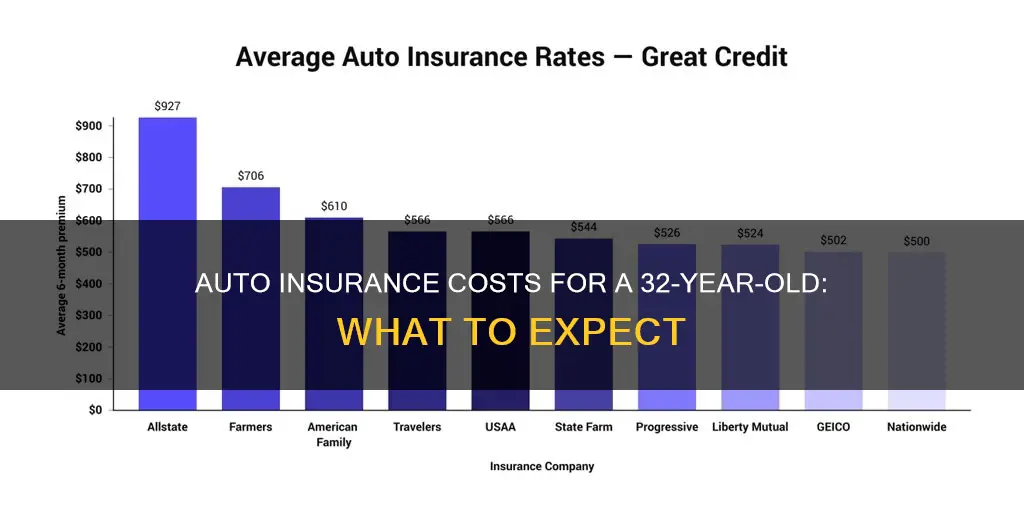
The following table reflects the estimated annual premiums for a 35-year-old driver with a clean record and a mid-sized sedan, opting for 100/300/100 coverage limits.
| Insurance Company | Average Annual Rate (Full Coverage) | Average Annual Rate (Min Coverage) |
|---|---|---|
| Erie Insurance | $1,750 | $510 |
| State Farm | $2,100 | $640 |
| Progressive | $2,420 | $780 |
| GEICO | $2,300 | $710 |
| Travelers | $2,600 | $850 |
| Allstate | $2,950 | $920 |
Note: These figures are averages. Rates for high-risk drivers or those in Philadelphia will be significantly higher.
Personal Factors That Influence Your PA Premium
Beyond state laws and geography, insurance companies in Pennsylvania utilize hundreds of data points to determine your "risk profile."
Credit-Based Insurance Scores
Pennsylvania allows insurers to use credit-based insurance scores to help determine premiums. Statistics show a high correlation between credit management and insurance claim frequency. In 2026, a driver with an "Excellent" credit score may pay $1,200 less per year than a driver with "Poor" credit, even if their driving records are identical.
Age and Experience
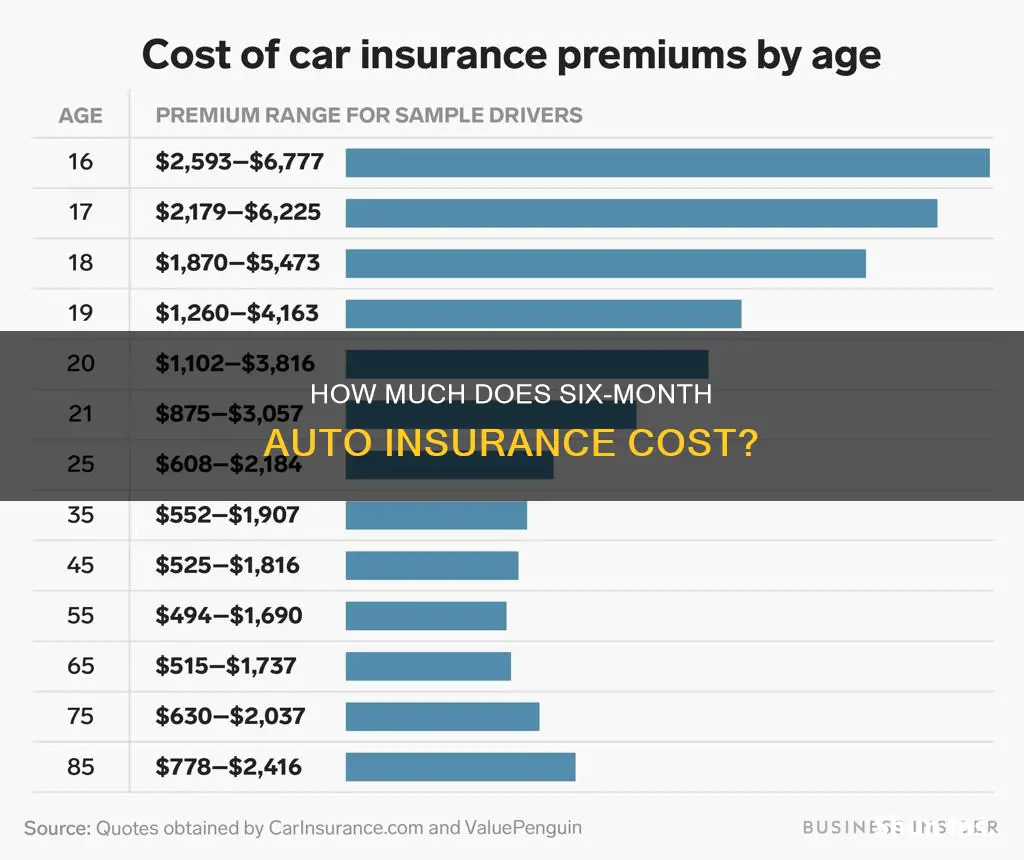
Young drivers, particularly those under 25, face the highest rates in the Commonwealth. A 16-year-old driver added to a parent's policy can increase the annual premium by $2,000 or more. Conversely, drivers in the 50–65 age bracket typically enjoy the lowest rates in Pennsylvania, provided they maintain a clean record.
Driving History
A single speeding ticket in Pennsylvania can increase your premium by 15% to 20% for three years. More serious offenses, such as a DUI (Driving Under the Influence), can cause premiums to double or lead to non-renewal. If you are non-renewed, you may be forced to seek coverage through the Pennsylvania Assigned Risk Plan (PAIP), which is significantly more expensive than the voluntary market.
The Impact of Vehicle Type on Costs
In 2026, the "what" you drive is as important as the "where." Insurance carriers analyze the cost of parts, the complexity of onboard sensors (ADAS), and the historical safety ratings of every vehicle model.
- Electric Vehicles (EVs): While gaining popularity in Pennsylvania, EVs often cost 10% to 20% more to insure due to higher repair costs for battery components and specialized labor requirements.
- Luxury Sedans: High-end brands like BMW or Mercedes-Benz command higher premiums because of their expensive aluminum frames and proprietary technology.
- Popular Trucks and SUVs: Vehicles like the Ford F-150 or Honda CR-V often have moderate insurance costs because parts are widely available and their safety ratings are high, though high theft rates for certain trucks in urban areas can offset these benefits.
How to Reduce Auto Insurance Costs in Pennsylvania
Despite the rising costs of repairs and medical care, Pennsylvania drivers have several avenues to lower their annual spend.
- Bundle Home and Auto: Most major carriers in PA offer a "multi-line" discount. Combining your homeowners or renters insurance with your auto policy can save 10% to 25% across both premiums.
- Increase Deductibles: If you have an emergency fund, raising your collision and comprehensive deductibles from $500 to $1,000 can reduce your premium by roughly 15%.
- Telematics Programs: Many PA insurers now offer "Pay-How-You-Drive" programs. By using a smartphone app or a plug-in device to monitor your braking, speed, and mileage, safe drivers can earn discounts of up to 40%.
- Affiliation Discounts: Pennsylvania has a high concentration of universities and large employers. Many insurers offer discounts for alumni of Penn State, UPenn, or Pitt, as well as employees of major healthcare systems like UPMC or Penn Medicine.
- Defensive Driving Courses: Drivers over age 55 in Pennsylvania can take a state-approved mature driver improvement course to receive a mandatory discount on their insurance for three years.
The Role of the Pennsylvania Insurance Department
The Pennsylvania Insurance Department regulates the industry and ensures that rate increases are justified and not discriminatory. If you believe your rates have been increased unfairly, or if you are having trouble with a claim, the Department provides resources for consumer complaints and market conduct investigations.
The Department also oversees the PA Post-Classroom Driver Education standards, which can lead to further discounts for younger drivers who complete certified training programs. Staying informed through official state channels can help you navigate the shifts in the 2026 insurance landscape.
Frequently Asked Questions
Is Pennsylvania a no-fault state?
Pennsylvania is a "choice no-fault" state. This means that regardless of who caused the accident, your own insurance pays for your medical bills (up to your First Party Benefit limit). However, the "choice" refers to your ability to choose between Limited Tort and Full Tort, which dictates your right to sue for non-monetary damages.
Can I drive in PA with only the $5,000 property damage minimum?
Legally, yes. However, it is highly discouraged. If you hit a modern vehicle or damage property (like a storefront or a utility pole), the costs will likely exceed $5,000. You would be personally responsible for the balance, which could lead to wage garnishment or the loss of assets.
How does a DUI affect my insurance in Pennsylvania?
A DUI conviction in Pennsylvania is a major violation. You can expect your rates to increase by 80% to 120% or more. Many standard carriers will refuse to renew your policy, forcing you into the high-risk market for at least three to five years. You may also be required to file an SR-22 certificate to prove financial responsibility.
Does Pennsylvania require Uninsured/Underinsured Motorist coverage?
Pennsylvania law requires insurers to offer Uninsured Motorist (UM) and Underinsured Motorist (UIM) coverage, but you have the right to reject it in writing. Given that a significant percentage of drivers in urban areas like Philadelphia may be uninsured, most experts recommend carrying UM/UIM limits that match your Bodily Injury limits.
Why is Erie Insurance often cheaper in Pennsylvania?
Erie Insurance is headquartered in Erie, Pennsylvania, and has a massive regional presence. Because they focus heavily on the mid-Atlantic region and have a robust network of local independent agents, they often have a more nuanced understanding of Pennsylvania’s risk pools, allowing them to price more competitively than some national giants.
Final Recommendation
To find the most competitive auto insurance rates in Pennsylvania for 2026, you should request quotes from at least three different types of carriers: a direct writer (like GEICO), a national brand with captive agents (like State Farm), and a regional carrier via an independent agent (like Erie Insurance). Ensure you are comparing identical "tort" selections and coverage limits. For most Pennsylvania residents, opting for Full Tort and increasing property damage liability to at least $50,000 provides the best balance of cost and essential protection against the state's unique legal and financial risks.
Image Gallery
Select an image to open it in a new tab.
Celine Dubois
Contemporary Living and Global Arts Columnist
