Finding cheapgood auto insurance in 2026 requires balancing minimum state requirements with essential protections like collision and comprehensive coverage. By leveraging telematics, bundling discounts, and maintaining a high credit-based insurance score, drivers can secure premium protection from top-tier carriers without paying the "luxury" price point often associated with generic comprehensive plans.
The term "cheapgood" represents the ultimate consumer goal: high-value protection at a below-market price. In the insurance industry, this is often referred to as the "Value Ratio." It is not merely about finding the lowest monthly premium, but rather about identifying the policy that provides the most robust financial shield relative to its cost. As we navigate the economic landscape of 2026, where vehicle repair costs have risen due to advanced sensor technology and specialized labor, the definition of "cheap" has shifted. A policy is only "good" if it actually prevents a total financial loss during a claim.
The Foundation of CheapGood Coverage: The Value Ratio
To secure a policy that qualifies as both cheap and good, one must understand that insurance is priced based on risk. Carriers utilize complex algorithms to determine the likelihood of a driver filing a claim. In 2026, these algorithms have become more granular, incorporating real-time data and historical trends. To get a high-quality policy at a lower price, you must present yourself as a low-risk entity to the insurer.
A "cheapgood" policy typically avoids the extremes. It avoids the "state minimum" trap, which often leaves drivers underinsured and personally liable for thousands of dollars in damages. Simultaneously, it avoids unnecessary "bells and whistles" like high-end roadside assistance or identity theft protection that can be sourced more cheaply elsewhere. The focus remains on core liability, property protection, and medical coverage.
Defining the "Good" in Auto Insurance
Quality insurance is defined by three primary pillars: financial stability of the carrier, claims processing speed, and coverage breadth. A policy from a company with an "A" rating from A.M. Best ensures that the company has the capital to pay out large claims even during economic downturns.
In 2026, "good" also refers to the digital experience. A quality insurer provides a seamless mobile interface for filing claims, uploading damage photos via augmented reality (AR) tools for faster estimates, and receiving immediate digital payments. If a policy is cheap but the claims process takes six weeks to resolve, the policy has failed the "good" criteria.
Defining the "Cheap" in Auto Insurance
Price is a relative metric. In 2026, the average cost of auto insurance has been influenced by the high cost of repairing Electric Vehicles (EVs) and vehicles equipped with Advanced Driver Assistance Systems (ADAS). A "cheap" policy is one that sits in the bottom 25th percentile of premium costs for your specific demographic and zip code, without sacrificing the essential coverage limits.
Essential Coverage Components for 2026
To build a cheapgood auto insurance policy, you must prioritize specific types of coverage while adjusting limits to match your net worth and risk tolerance.
Bodily Injury and Property Damage Liability
This is the most critical part of your policy. It pays for the injuries and property damage you cause to others. While states have low minimum requirements (e.g., $25,000 per person), these are insufficient in 2026. A single emergency room visit can easily exceed $30,000.
A high-value approach is to opt for 100/300/100 limits ($100,000 per person for bodily injury, $300,000 per accident, and $100,000 for property damage). While the premium is slightly higher than state minimums, the increase is usually marginal—often less than $10 per month—while providing four times the protection.
Uninsured and Underinsured Motorist Coverage (UM/UIM)
As insurance premiums rise, the number of uninsured drivers on the road tends to increase. UM/UIM coverage protects you if you are hit by someone who either has no insurance or has limits too low to cover your medical bills. In many jurisdictions, this is a relatively inexpensive add-on that provides massive financial security, making it a staple of any cheapgood policy.
Comprehensive and Collision Coverage
These protect your own vehicle.
- Collision covers accidents with other cars or objects.
- Comprehensive covers "acts of God," such as fire, theft, vandalism, or weather damage.
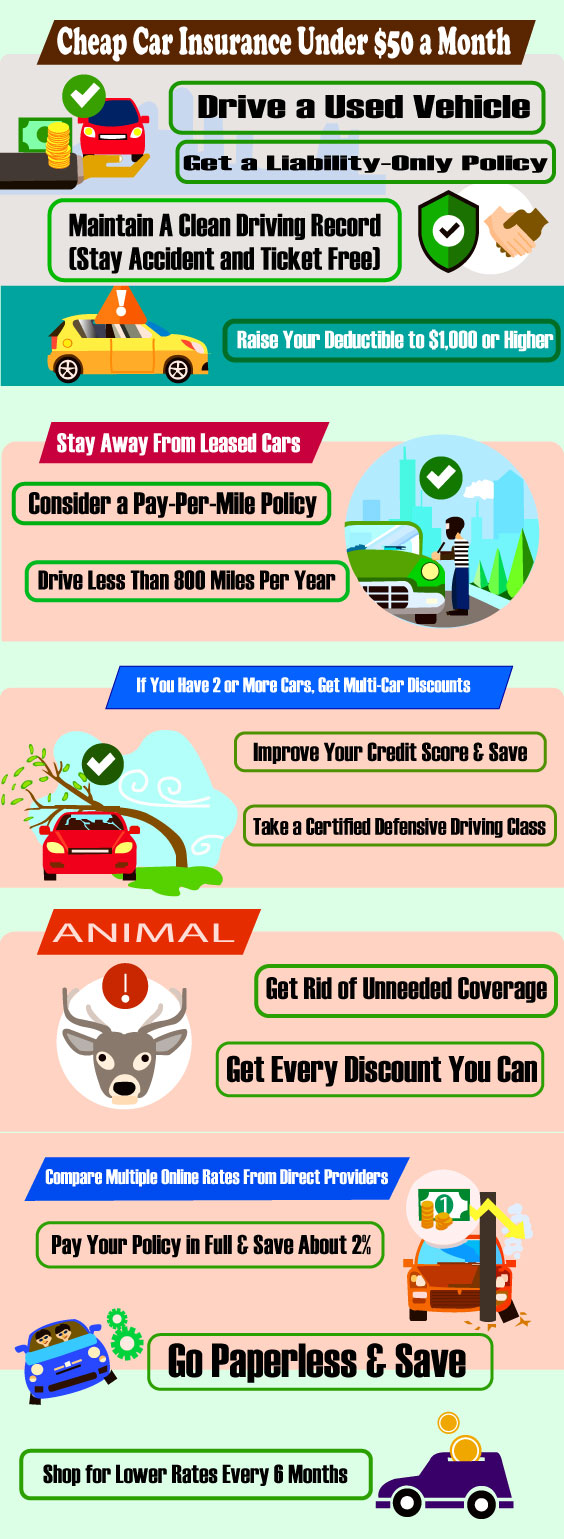
To keep these "cheap," look at the deductible. In 2026, moving from a $500 deductible to a $1,000 deductible can reduce the physical damage portion of your premium by 15% to 30%. However, you must ensure you have the $1,000 set aside in an emergency fund.
Strategies to Optimize Costs in 2026
Modern insurance pricing is highly dynamic. To achieve the best rates, drivers should employ specific strategies that align with current industry practices.
Leveraging Telematics and Usage-Based Insurance (UBI)
Telematics has become the standard for "cheapgood" insurance. By allowing an insurer to monitor your driving habits via a smartphone app or a plug-in device, you can receive discounts based on your actual performance rather than just your demographic data.
In 2026, these programs have evolved to offer "Pay-Per-Mile" options for remote workers and "Safe Driver" discounts for those who avoid hard braking and late-night driving. If you drive fewer than 8,000 miles per year, UBI is often the fastest path to a 40% reduction in premiums.
The Power of Bundling and Multi-Policy Discounts
Carriers prioritize "sticky" customers—those who have multiple lines of business with them. Bundling your auto insurance with homeowners, renters, or pet insurance remains one of the most effective ways to lower costs. In 2026, many carriers offer a "total household" discount that applies even if the policies are for different individuals living at the same address, provided they are under the same umbrella.
Credit-Based Insurance Scores
In states where it is legally permitted, your credit history significantly impacts your insurance rate. Insurers have found a high correlation between financial responsibility and driving safety. Improving your credit score by even 50 points can transition you into a different "rating tier," potentially saving hundreds of dollars annually.
Comparison of Value-Oriented Insurance Tiers (2026 Estimates)
The following table illustrates how different coverage levels affect the "Value Ratio." Prices are based on national averages for a driver with a clean record and a mid-range vehicle.
| Coverage Level | Annual Premium (Est.) | Key Features | Best For |
|---|---|---|---|
| State Minimum | $950 | Lowest legal limits; no physical damage coverage. | Drivers with low-value cars and no assets. |
| The "CheapGood" Standard | $1,400 | 100/300/100 limits; $1,000 deductible; UM/UIM included. | Most drivers looking for high value and safety. |
| Premium Comprehensive | $2,200 | 250/500/100 limits; $250 deductible; Gap insurance; Rental car. | New car owners and high-net-worth individuals. |
| Usage-Based (Low Mile) | $850 | Standard limits; base rate + cents per mile. | Remote workers and urban drivers. |
Common Mistakes That Ruin the "CheapGood" Balance
When searching for affordable insurance, it is easy to fall into traps that result in poor-quality coverage.
Selecting Excessively Low Liability Limits
Many drivers choose the lowest possible price point without realizing that they are one accident away from a wage garnishment. If you cause $50,000 in damage but only have $25,000 in coverage, the other party can sue you for the remaining $25,000. A "cheap" policy that leaves you exposed to a $25,000 judgment is not "good" insurance.
Ignoring Gap Insurance for Financed Vehicles
If you are financing a car in 2026, your vehicle likely depreciates faster than you pay off the loan. If the car is totaled, standard collision coverage only pays the "Actual Cash Value" (ACV). Without Gap Insurance, you could end up owing thousands of dollars to your lender for a car you no longer have. For a few dollars a month, Gap Insurance is a vital component of a smart, affordable policy.
Failing to Re-Shop Annually
Insurance companies often use "price optimization," a practice where they gradually increase rates for loyal customers who they believe are unlikely to switch. To maintain a cheapgood status, you should compare rates every 12 months. Even if you stay with the same carrier, a new quote might reveal updated discounts or tiers for which you now qualify.
Identifying Reliable Carriers in 2026
While specific pricing varies by geography, several national carriers consistently rank high for providing a balance of cost and quality.
- State Farm: Known for a vast network of local agents and strong bundling discounts for homeowners.
- Geico: Frequently the leader in pure price for digital-first users, though service is primarily online/app-based.
- Progressive: Excellent for drivers with a history of minor incidents and those using the "Snapshot" telematics program.
- Amica Mutual: Consistently tops JD Power surveys for customer satisfaction and claims handling, offering a "dividend" policy that returns a portion of the premium to the customer.
- USAA: Often the cheapest and highest-rated option, though it is exclusively available to military members and their families.
FAQs About CheapGood Auto Insurance
Does the color of my car affect my insurance rate?
Contrary to popular belief, the color of your vehicle—even red—has no impact on your insurance premium. Insurers care about the vehicle's make, model, safety features, engine size, and historical repair costs. In 2026, they are also highly focused on the presence of ADAS features like lane-assist and automatic emergency braking, which can lower premiums by reducing accident frequency but raise them by increasing repair costs.
Can I get "cheapgood" insurance if I have a speeding ticket?
Yes, though your options will be more limited. High-risk drivers should look for "non-standard" carriers or focus on telematics-based programs. Many insurers in 2026 will "forgive" one minor speeding ticket if you participate in a monitored driving program and maintain a clean record for six months following the incident.
Why is my insurance so expensive even though I don't drive much?
Even if you don't drive, your car is at risk for theft, vandalism, and weather damage. Furthermore, fixed costs like administrative fees and basic liability pools apply to every policy. To lower costs as a low-mileage driver, you must switch to a verified usage-based policy (UBI) that tracks your odometer, rather than a traditional flat-rate policy.
Is glass coverage included in a "cheapgood" policy?
In many states, full glass coverage is an optional endorsement. Given that 2026 windshields often contain integrated cameras and sensors that require calibration after replacement, a single windshield can cost over $1,500. Adding "Full Glass" coverage is usually inexpensive and prevents a high deductible from applying to a common type of claim, making it an excellent "value" addition.
How does my zip code affect my "CheapGood" status?
Your zip code is one of the most powerful factors in insurance pricing. It determines the likelihood of accidents, theft, and weather-related claims (like hail or flooding). If you live in an area with high crime or frequent traffic congestion, your "cheap" will be higher than someone in a rural area. The best way to mitigate this is to ensure your vehicle is parked in a garage or has an active anti-theft tracking system, which provides specific discounts.
What is the "Step-Down" provision and why should I avoid it?
Some ultra-cheap policies include "Step-Down" provisions that reduce your liability limits to the state minimum if someone not listed on your policy is driving your car. This is a hallmark of "cheap but bad" insurance. A quality policy should maintain your chosen limits for any permissive driver.
Practical Next Steps
To secure cheapgood auto insurance today, begin by gathering your current policy's "Declarations Page." This document outlines your current limits and costs. Use this as a baseline to compare against at least three other carriers. Prioritize quotes that offer telematics integration if you are a safe driver, and always opt for a $1,000 deductible if you have the savings to support it. Finally, verify the carrier's claims reputation through the National Association of Insurance Commissioners (NAIC) Complaint Index to ensure that "cheap" doesn't turn into "expensive" when you actually need to use the policy.
Image Gallery
Select an image to open it in a new tab.
Ingrid Bjornson
Global Cyber Policy and Regulation Analyst
