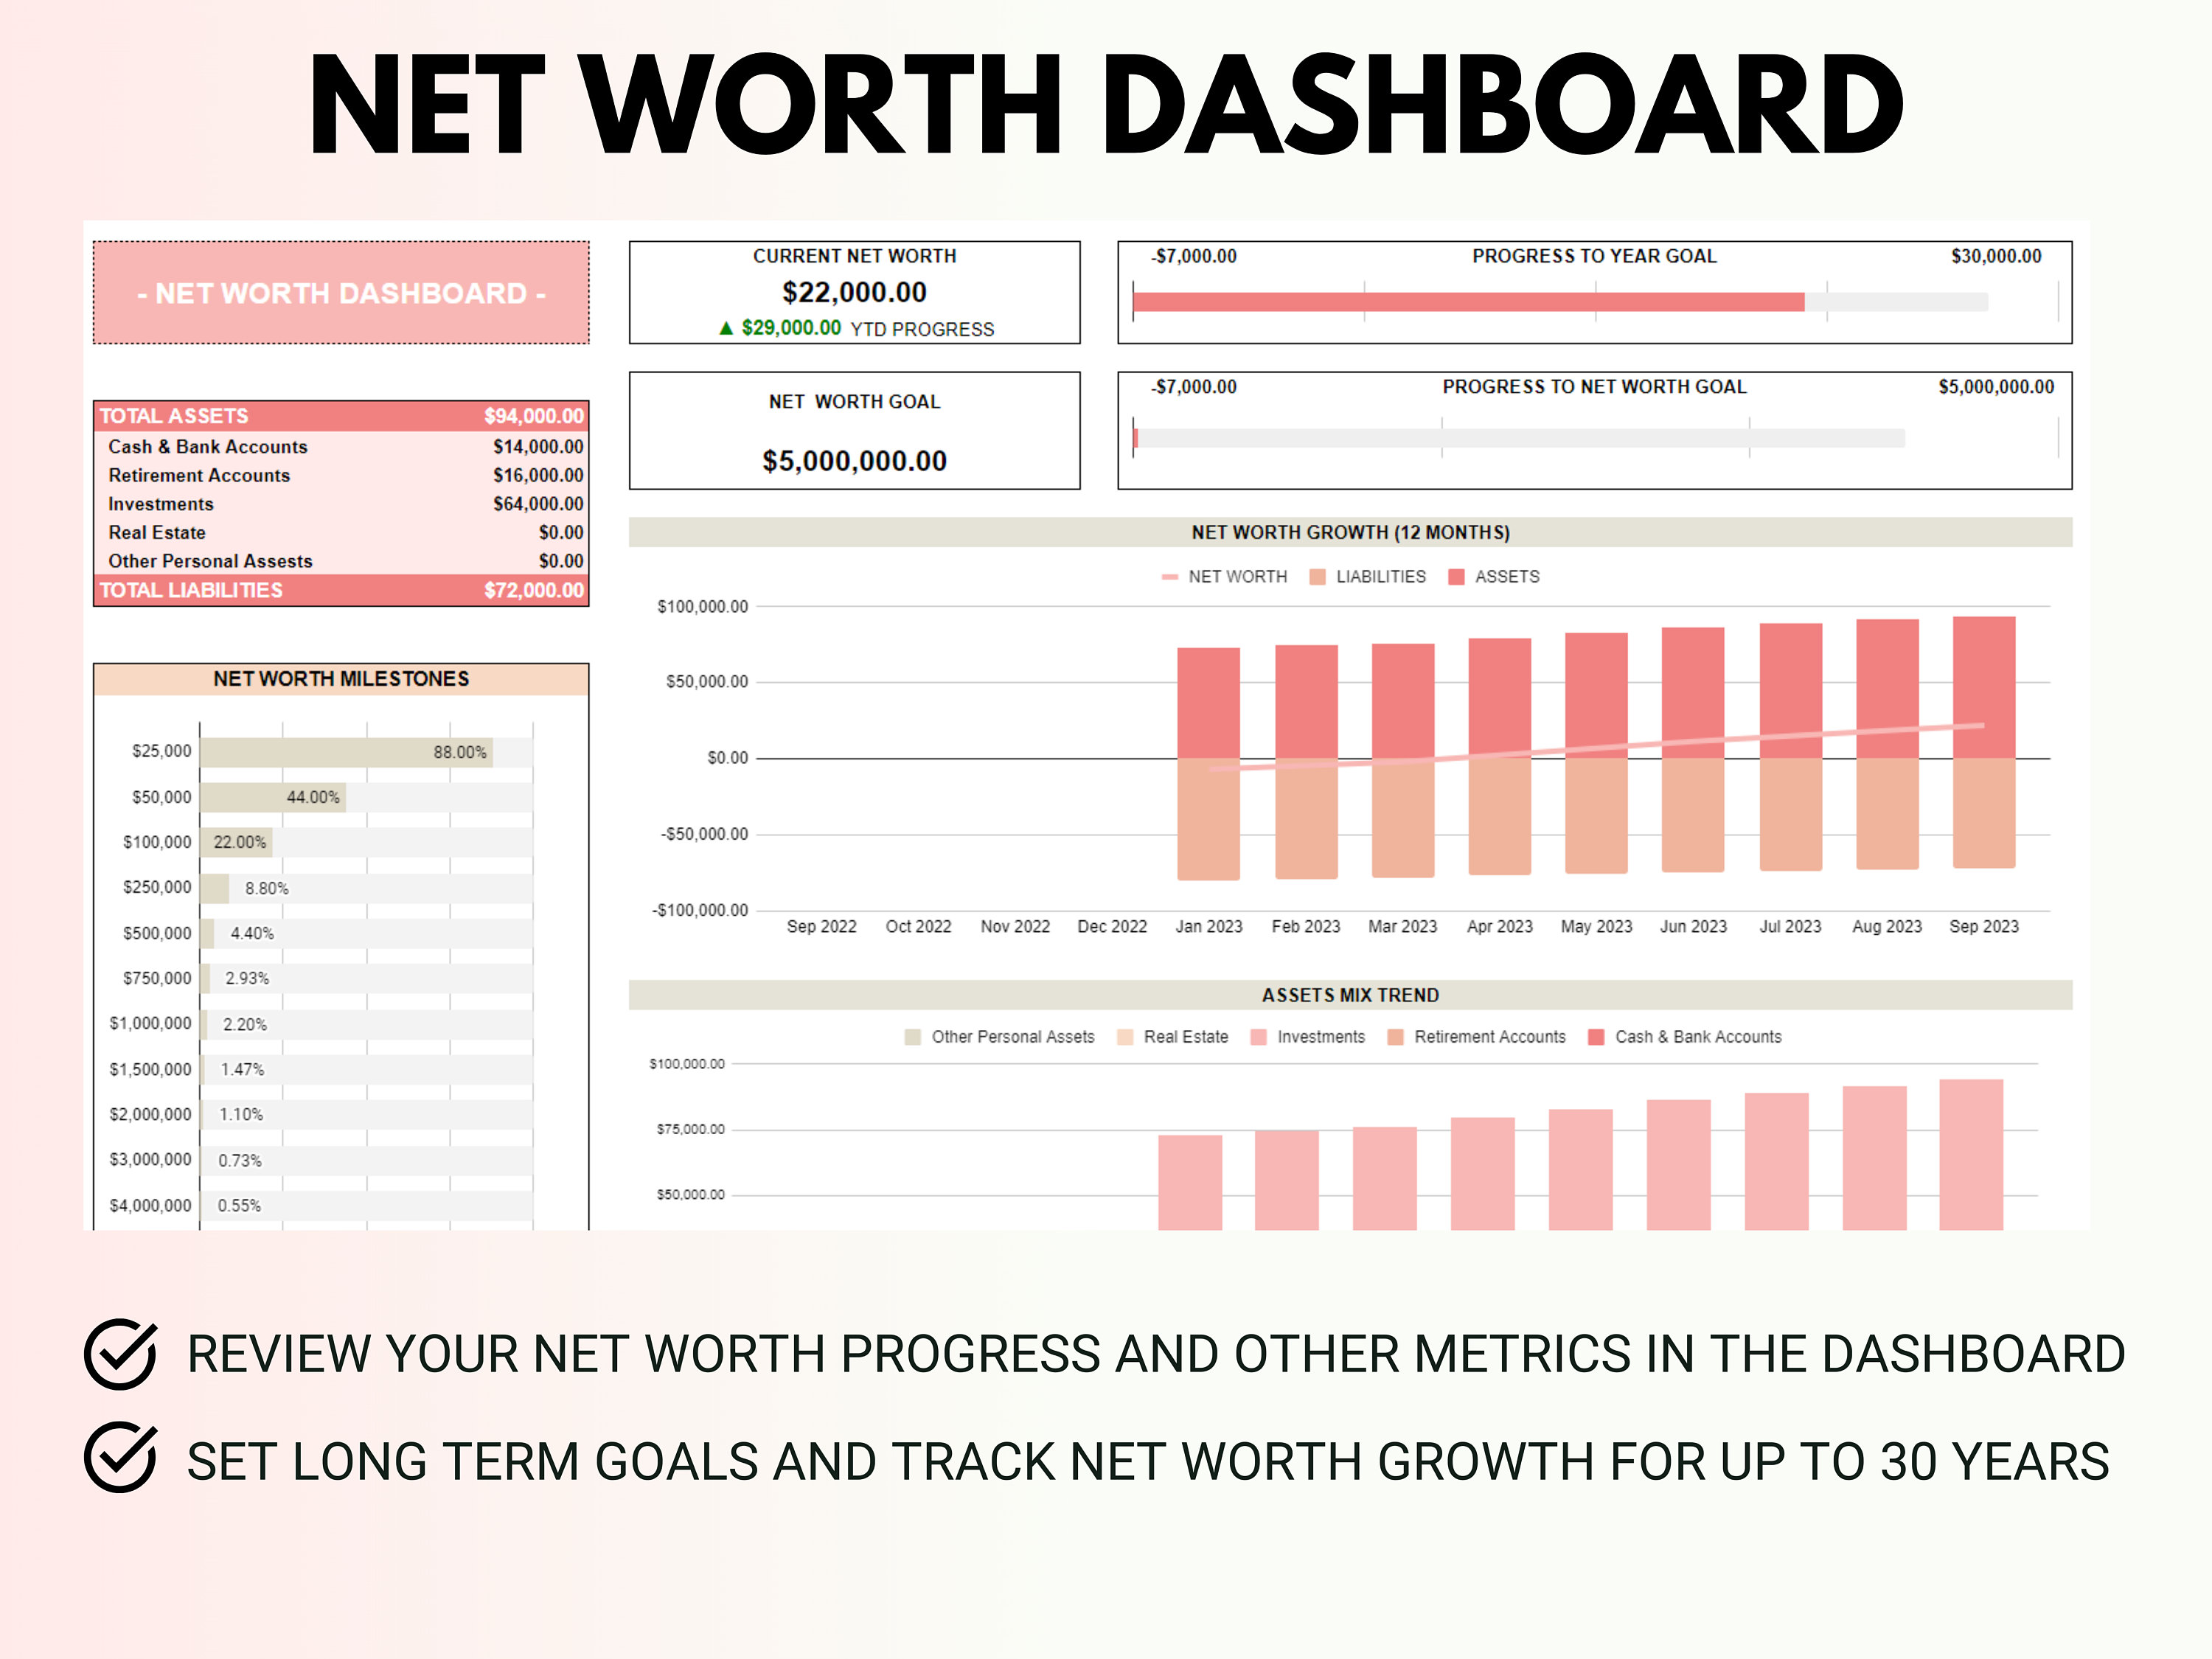
Reaching a 10 million dollar net worth represents a significant financial transition, marking the movement from wealth accumulation to wealth preservation and sophisticated lifestyle management. Celebrating this milestone involves moving beyond mere surface-level consumption toward tax-efficient planning, legacy structuring, and the integration of professional advisory services to ensure long-term asset protection.
Understanding the Significance of the 10 Million Dollar Threshold
The 10 million dollar net worth figure is often identified in financial planning as a threshold where the complexity of wealth management shifts. At this level, individuals typically surpass standard retail banking and generic investment platforms. The primary shift involves moving toward high-net-worth (HNW) or ultra-high-net-worth (UHNW) strategies.
When you cross this mark, the conversation changes from "how do I save more" to "how do I optimize what I have." You are likely now subject to advanced tax considerations, estate tax exemption limits, and the need for diversification across non-correlated asset classes. Celebrating this milestone should therefore be characterized by structural consolidation rather than merely transactional rewards.
Immediate Financial Actions Post-Milestone
Before engaging in any personal celebration, it is essential to conduct a "milestone audit." This ensures that the growth you have achieved is locked in and protected against systemic risks.
1. Re-evaluating Asset Allocation
A portfolio that grew to 10 million dollars via aggressive equity accumulation may carry higher volatility than is sustainable for long-term preservation. Transitioning to a core-satellite portfolio—where 70-80% of assets are in low-cost, diversified index funds and the remainder in tactical or alternative investments—is a common move.
2. Estate Planning and Asset Protection
If you have not already established a revocable living trust or, in some jurisdictions, an irrevocable trust, the 10 million dollar mark is the appropriate time to do so. This protects your assets from probate and provides a framework for multi-generational wealth transfer. Ensure your beneficiary designations are updated on all accounts, including retirement vehicles and insurance policies.
3. Tax Liability Optimization
Review your current tax bracket against the potential for tax-advantaged vehicles. This may include municipal bonds for income generation, donor-advised funds for philanthropic goals, or the restructuring of business holdings to utilize pass-through entity advantages where applicable.

Comparative Frameworks for Wealth Management
As you reach this level of capital, the tools you use to manage that capital must scale accordingly. The following table contrasts the standard retail approach with the high-net-worth approach.
| Service Area | Retail/Standard Approach | High-Net-Worth Approach |
|---|---|---|
| Advisory Model | Commission-based broker | Fee-only Fiduciary / Multi-Family Office |
| Asset Classes | Public stocks and bonds | Private equity, real estate, hedge funds |
| Tax Strategy | Standard deductions | Tax-loss harvesting, LPs, and Trusts |
| Insurance | Standard policies | Umbrella/Excess Liability ($5M+ limits) |
| Estate Strategy | Simple Will | Living Trusts, Family Limited Partnerships |
The Philosophy of Celebrating Wealth Responsibly
Celebrating a 10 million dollar net worth is often best approached through "lifestyle alignment." This means ensuring that your consumption habits remain decoupled from the volatility of your investment portfolio. Many high-net-worth individuals opt to celebrate this milestone by investing in experiences that facilitate long-term growth, such as advanced education, health optimization programs, or philanthropic endeavors that provide social capital.
Investing in Human Capital
Many who reach this milestone realize that their greatest asset remains their health and decision-making capacity. Consider allocating a portion of your wealth to "longevity" services—comprehensive executive physicals, high-end nutritional consulting, or executive coaching. Unlike a depreciating asset like a luxury vehicle, these investments have the potential to increase your ability to continue generating and managing wealth.
Legacy and Philanthropy
If your net worth goal was met through a specific business venture or professional career, your celebration might involve the creation of a private foundation or a donor-advised fund. This allows for a structured approach to giving, which can also provide significant tax benefits while cementing your values into the future.
Common Mistakes After Reaching the 10M Mark
The most frequent error observed in individuals who hit 10 million dollars is "lifestyle creep," where fixed expenses balloon to match the perceived level of wealth. This creates a dependency on high income levels that can become a trap if market conditions shift.
- Failure to Diversify: Relying on a single asset, such as a business you own or a specific tech stock, is dangerous. Once the 10M milestone is reached, the priority must shift from concentration for growth to diversification for survival.
- Neglecting Liability Coverage: As your net worth grows, so does your profile as a potential target for litigation. Moving from standard insurance to a high-limit umbrella policy is a foundational requirement for anyone with significant assets.
- Emotional Decision Making: The psychology of managing a large portfolio is different from the psychology of building it. Avoid the "recency bias" of believing that past market performance will dictate the future, and resist the urge to chase speculative "get rich faster" trends once you have already reached a comfortable level of financial independence.
Frequently Asked Questions
Is 10 million dollars enough for full retirement?
Whether 10 million is "enough" depends entirely on your burn rate. Using the 3% rule—a conservative withdrawal rate—you would have 300,000 dollars in annual pre-tax income. If your lifestyle requires more than this, you are not necessarily retired in the traditional sense, but rather "financially independent" with the freedom to pursue lower-stress or passion-based work.
When should I move from a standard advisor to a family office?
A single-family office is typically reserved for wealth exceeding 50 to 100 million dollars. However, at the 10 million dollar mark, you should consider a "Multi-Family Office" (MFO). These firms provide high-level, integrated financial planning, including tax, legal, and estate services under one roof, specifically for individuals in your net worth bracket.
How do I protect my 10 million dollar net worth from lawsuits?
Asset protection is usually achieved through a combination of insurance and legal entity structures. An umbrella insurance policy is the first line of defense. Beyond that, keeping assets in various LLCs or trusts helps insulate different parts of your wealth from legal judgments against you personally. Consult with an asset protection attorney specializing in high-net-worth planning.
Should I pay off my mortgage when I hit this milestone?
This is a mathematical calculation rather than an emotional one. If your mortgage interest rate is low (e.g., locked in at a historical rate below 4%), it is often more efficient to keep the debt and invest the capital in vehicles yielding higher returns. If the mortgage carries a high rate, paying it off provides a guaranteed "return" equal to the interest rate, which is a risk-free way to reduce fixed monthly overhead.
How does the 2026 tax environment affect this milestone?
As of 2026, the federal estate tax exemption remains a critical consideration. With current tax laws, large estates need to be proactive about gifting strategies to utilize the lifetime exemption before any potential sunsetting of provisions. Always review your tax strategy with a certified public accountant (CPA) who has experience with UHNW tax codes.
Practical Next Steps
Your next action should be a "Wealth Gap Analysis." Take your current financial statement and compare it against your long-term goals for the next 10, 20, and 30 years.
- Meet with a Fiduciary: If your current advisor is a broker, interview at least three fee-only fiduciary advisors to ensure your incentives are aligned.
- Conduct an Estate Review: Verify that your trust and will documents are not only created but also funded correctly. A trust is useless if your assets are not titled in its name.
- Define your "Why": Wealth is a tool, not an end. Spend time defining what this milestone allows you to do that you could not do before. Whether it is mentoring others, funding a specific cause, or buying back your time, your celebration should reflect your personal values.
By viewing this milestone as a baseline for future stability rather than a finish line for growth, you protect your future and ensure that your 10 million dollar net worth remains a foundation for a life well-lived.
Image Gallery
Select an image to open it in a new tab.



Akira Tanaka
International Academic Trends Correspondent
