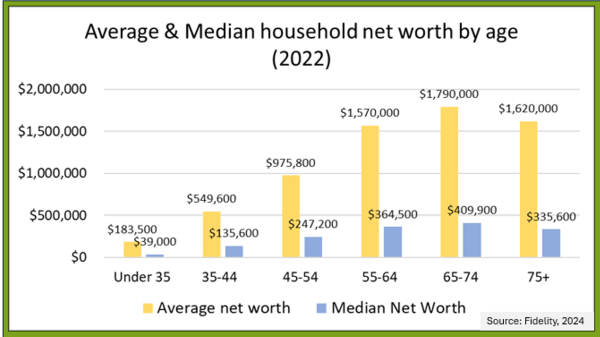
The average net worth of a household in Spain is approximately €285,000, while the median net worth—a more accurate reflection of the typical family—stands near €135,000. Wealth in Spain is heavily concentrated in real estate, with nearly 75% of total household assets held in property, reflecting a cultural preference for homeownership over financial market investments.
Understanding the landscape of wealth in Spain requires a distinction between income (the flow of money) and net worth (the stock of accumulated assets minus liabilities). As of 2026, the Spanish economic profile remains one of the most property-centric in the European Union. While the "average" or mean figure is often cited in headlines, it is frequently skewed by the country's wealthiest decile. To truly grasp the financial health of the Spanish population, one must examine the distribution of assets, the impact of generational shifts, and the heavy weight of the real estate sector.
Defining Net Worth in the Spanish Context
Net worth is the total value of all assets owned by an individual or household, minus all outstanding debts. In Spain, the primary data source for these figures is the "Encuesta Financiera de las Familias" (EFF), or the Household Financial Survey, conducted by the Bank of Spain (Banco de España). This survey is the gold standard for wealth metrics because it looks beyond simple bank balances to include the value of primary residences, secondary properties, business equity, and private pension plans.
Spanish assets are typically categorized into two groups: real assets and financial assets. Real assets include the primary residence, other real estate properties (such as holiday homes or rental units), and durable goods. Financial assets include checking accounts, savings deposits, stocks, investment funds, and pension schemes. On the liability side of the ledger, the most significant debt for Spanish households remains the mortgage, followed by consumer credit and personal loans.
In 2026, we see that the recovery of the property market and the steady, albeit modest, growth of the Spanish stock market (IBEX 35) have contributed to a nominal increase in net worth. However, when adjusted for inflation and the rising cost of living in major hubs like Madrid and Barcelona, the "real" purchasing power of this wealth has faced significant pressure over the last five years.
The Mean vs. Median Disparity
When discussing "average" net worth, economists distinguish between the mean and the median. The mean net worth in Spain is significantly higher than the median because of wealth concentration at the top. The top 10% of the population holds a disproportionate share of the country’s total wealth, which pulls the mathematical average upward.
The median net worth—the midpoint where half the population has more and half has less—provides a more realistic picture of the "average" Spaniard. In 2026, while the mean net worth is approaching the €300,000 mark, the median remains significantly lower, hovering around €135,000. This gap highlights a persistent wealth inequality that is common across Southern Europe, though Spain’s inequality is often mitigated by the high rate of property ownership among older generations.
This disparity is also reflected in the "wealth deciles." The bottom 20% of households in Spain often have a net worth of less than €5,000, frequently consisting of young professionals with high student or consumer debt and no real estate equity. In contrast, the top 1% of households often possess a net worth exceeding €3 million, largely driven by diversified portfolios and commercial real estate holdings.
Real Estate: The Pillar of Spanish Wealth
The most defining characteristic of wealth in Spain is the "ladrillo" (brick) culture. Unlike the United States or the United Kingdom, where a larger portion of household wealth is often held in equities (stocks) and 401(k)-style retirement accounts, Spaniards historically distrust the volatility of the stock market. Instead, they view property as the ultimate "safe haven" asset.
Primary Residence and Secondary Properties
According to data from the National Statistics Institute (INE), approximately 75% of Spanish households own their primary residence. This is one of the highest rates in the OECD. For many families, the mortgage-free ownership of a home is their primary form of "pension" or social security.
Furthermore, a significant portion of the middle and upper-middle class in Spain owns a second home, often in coastal regions or ancestral villages. These secondary properties contribute significantly to the total net worth of households in the 50-70 age bracket. In 2026, the valuation of these properties has become a double-edged sword; while it increases paper net worth, it also creates a high "illiquid" wealth profile, where families are "house-rich but cash-poor."
The Shift Toward Financial Assets
While real estate remains dominant, there is a gradual shift among younger generations (under 45) toward financial assets. This is driven by several factors:
- Market Accessibility: The rise of low-cost fintech platforms and "neo-brokers" has made it easier for Spaniards to invest in global ETFs and international stocks.
- Housing Affordability: With property prices in Madrid, Barcelona, and Malaga reaching record highs in 2025 and 2026, many young professionals are forced to rent, leading them to put their savings into liquid financial markets instead of a down payment.
- Tax Incentives: While Spain's wealth tax (Impuesto sobre el Patrimonio) remains a point of contention, certain investment vehicles like Spanish "fondos de inversión" offer tax-deferred growth, making them more attractive than they were a decade ago.
Net Worth by Age and Generation
Age is the single most important predictor of net worth in Spain. The distribution follows a traditional "hump-shaped" profile, where wealth accumulates through a person's working life, peaks just before or at retirement, and gradually declines as assets are liquidated or gifted to heirs.
| Age Group | Estimated Median Net Worth (2026) | Primary Asset Type | Debt Profile |
|---|---|---|---|
| Under 35 | €25,000 | Savings / Vehicles | High (Student/Consumer) |
| 35–44 | €85,000 | Primary Residence Equity | High (Mortgage) |
| 45–54 | €160,000 | Real Estate / Pensions | Moderate (Decreasing Mortgage) |
| 55–64 | €210,000 | Real Estate / Investments | Low |
| 65–74 | €195,000 | Real Estate / Cash | Very Low |
| 75+ | €155,000 | Real Estate | Negligible |
The "Under 35" demographic in Spain faces unique challenges. High youth unemployment rates over the last decade, combined with the "temporary contract" culture, have delayed the age at which young Spaniards can enter the property market. Consequently, the net worth of this group is significantly lower than that of their counterparts in Northern Europe or the United States, who may have higher levels of retirement account contributions.
Conversely, the "Baby Boomer" generation in Spain (those born between 1955 and 1975) holds the lion's share of national wealth. They benefited from the rapid appreciation of property prices following Spain's entry into the European Union and have largely paid off their mortgages.
Regional Disparities: The Wealth Map
Spain is not a monolith when it comes to wealth. There is a stark divide between the industrial and financial hubs and the more rural, agrarian provinces.
Madrid and the Basque Country
The Community of Madrid and the Basque Country consistently rank as the wealthiest regions. In Madrid, the concentration of corporate headquarters and high-paying service jobs drives both high incomes and high property values. The Basque Country benefits from a strong industrial base and a unique tax arrangement (the Concierto Económico) that allows for significant local reinvestment. In these regions, the average net worth can be 20-30% higher than the national average.
The Mediterranean Arc
Regions like Catalonia, Valencia, and the Balearic Islands show high levels of wealth, but with greater inequality. The Balearic Islands, in particular, have seen an explosion in net worth due to international demand for luxury real estate, though this often displaces the local population whose net worth does not match the skyrocketing property values.
The South and the Interior
Extremadura, Andalusia, and parts of Castile-La Mancha generally report the lowest average net worth. These regions rely more heavily on agriculture and tourism, which typically offer lower wages. However, it is worth noting that the "cost of living" in these areas is also lower, meaning that a lower net worth may still provide a comparable quality of life to a higher net worth in an expensive city like Barcelona.
The Impact of Debt on Net Worth
To calculate net worth, we must subtract liabilities. In Spain, household debt is overwhelmingly tied to the residential mortgage market. According to the Bank of Spain, the ratio of household debt to disposable income has stabilized in 2026 after a period of deleveraging following the 2008 financial crisis.
However, the "Euribor" (the interest rate at which European banks lend to one another) remains a critical factor. Since the majority of Spanish mortgages were historically variable-rate, fluctuations in the Euribor have a direct and immediate impact on a household's net worth. When interest rates rise, the liability portion of the net worth equation increases as more money is diverted to interest payments rather than principal reduction or savings. In 2026, we see a trend toward fixed-rate mortgages as consumers seek to protect their net worth from future volatility.
Taxes and Net Worth
Spain is one of the few countries in the European Union that maintains a Wealth Tax (Impuesto sobre el Patrimonio) and a Solidarity Tax on Large Fortunes. These taxes are levied on the total net worth of individuals above certain thresholds (generally starting at €700,000, though this varies by autonomous community).
For residents and expats alike, these taxes act as a "drag" on net worth accumulation for high-net-worth individuals. Additionally, the Inheritance and Gift Tax (Impuesto sobre Sucesiones y Donaciones) plays a role in how wealth is passed between generations. In regions where this tax is high, heirs may be forced to liquidate assets (like the family home) just to pay the tax bill, which can lead to a sudden drop in the household's net worth.
Frequently Asked Questions
Is the "average" net worth in Spain higher or lower than in the US?
The average (mean) net worth in Spain is significantly lower than in the United States. However, the median net worth is often more comparable. This is because the US has extreme wealth concentration at the very top, which inflates its mean, while Spain has a broader "middle class" of property owners. Furthermore, Spaniards generally have less "net" debt in the form of student loans or medical debt compared to Americans.
Does net worth include the value of my car?
Technically, yes. Net worth includes all "durable goods," which includes vehicles, jewelry, and art. However, for most financial planning purposes in Spain, these are considered "lifestyle assets" rather than "investment assets" because they typically depreciate in value. Most official surveys like the EFF include them but weight them less heavily than real estate or financial investments.
How has inflation affected net worth in 2026?
Inflation has a complex relationship with net worth. While it increases the nominal value of real estate (the largest asset for Spaniards), it erodes the purchasing power of cash savings. For many Spanish households, the "nominal" net worth has increased because their homes are worth more euros, but their "real" wealth may have stagnated if the cost of goods and services rose faster than their asset appreciation.
What is considered a "good" net worth in Spain?
A "good" net worth is subjective and depends on age and location. For a couple in their 50s living in a major city, a net worth of €400,000 (including a paid-off home and some savings) is considered very comfortable. For a single individual in their 30s, having a positive net worth of any amount—meaning their assets exceed their debts—is considered a strong financial starting point in the current economic climate.
Do pensions count toward net worth?
Public state pensions in Spain do not count toward your personal net worth because they are a future "right" to income rather than an owned asset you can sell or bequeath. However, private pension plans (Planes de Pensiones) are considered financial assets and are included in the calculation of your total net worth.
Practical Recommendation for 2026
If you are looking to increase or protect your net worth in Spain, the most effective strategy in 2026 is diversification. While the cultural impulse is to buy more property, the "illiquidity" of real estate can be a risk during economic downturns.
- Evaluate Liquidity: Ensure that at least 15-20% of your net worth is in liquid financial assets (stocks, bonds, or cash) to cover emergencies without needing to sell property.
- Review Mortgage Terms: If you hold a variable-rate mortgage, calculate the impact of potential Euribor shifts on your net liabilities.
- Tax Planning: If your net worth exceeds €700,000, consult with a Spanish tax specialist to understand the implications of the Wealth Tax and how to structure your assets to minimize "tax drag."
- Generational Transfer: Given the complexity of Spanish inheritance laws, families should plan for the transfer of wealth early to avoid situations where heirs cannot afford the taxes on the assets they inherit.
Image Gallery
Select an image to open it in a new tab.
Akira Tanaka
International Academic Trends Correspondent
