Appealing an auto insurance claim denial is a critical step to ensure you receive the compensation required for vehicle repairs, medical expenses, and liability protection. In 2026, with the rise of automated claims processing, an appeal provides a necessary human review to correct algorithmic errors, challenge unfair liability assessments, and prevent long-term financial damage or increased premiums.
Receiving a denial letter from an insurance company can feel like a final verdict, but in the insurance industry, it is often just the beginning of a negotiation. Insurance companies are for-profit entities that utilize complex software and strict policy interpretations to minimize payouts. If you believe your claim was valid under the terms of your contract, accepting a denial without challenge can result in thousands of dollars in out-of-pocket costs and a permanent mark on your claims history.
The Financial Stakes of a Claim Denial
The primary reason an appeal matters is the immediate and long-term financial impact. When a claim is denied, the financial burden of the accident shifts entirely to the policyholder. In 2026, the average cost of vehicle repairs has risen significantly due to the integration of advanced sensor suites, lidar, and specialized EV components. A "minor" fender bender that might have cost $1,500 a decade ago can easily exceed $5,000 today.
Beyond physical repairs, a denial can leave you responsible for medical bills. If you or your passengers were injured, personal injury protection (PIP) or medical payments coverage is designed to provide immediate relief. A denial here does not just mean you pay the bills; it can also lead to medical debt that affects your credit score and future financial stability.
The Impact on Future Premiums
Many policyholders do not realize that a denied claim still appears on your Comprehensive Loss Underwriting Exchange (CLUE) report. This report is a database used by nearly all insurers to determine your risk level and set your premiums. If a claim is denied because the insurer determined you were at fault or that the incident was "not a covered peril," that designation stays with you. By successfully appealing and getting the denial overturned or the fault reassessed, you can protect your "clean" driving record and avoid the "high-risk" surcharges that can haunt your insurance rates for three to five years.
Correcting Algorithmic and Human Errors
In 2026, the insurance industry relies heavily on Artificial Intelligence (AI) and automated "straight-through processing" for claims. While this speeds up simple claims, it lacks the nuance required for complex accidents. AI models may misinterpret dashcam footage, overlook specific regional traffic laws, or fail to account for mechanical failures that were not the driver's fault.
Administrative Oversight
Insurance adjusters handle hundreds of files simultaneously. It is remarkably common for a denial to stem from a simple administrative error, such as:
- Missing Documentation: An adjuster may have overlooked a police report or a witness statement that was uploaded to a portal but not correctly linked to the file.
- Policy Misinterpretation: Adjusters may apply an outdated version of a policy or fail to recognize an endorsement or rider you purchased that specifically covers the incident in question.
- Incorrect VIN or Data Entry: A simple typo in a Vehicle Identification Number or a date can trigger an automated denial based on "no coverage on the date of loss."
Appealing forces a manual "second look" by a supervisor or a dedicated appeals specialist. This human intervention is often the only way to catch these binary errors that an automated system would never flag.
Challenging Subjective Liability Determinations
Liability—who is at fault for the accident—is rarely black and white. Most states operate under some form of comparative or contributory negligence. This means that even if you were partially responsible, you may still be entitled to a percentage of your damages.
Insurers often issue a blanket denial if they believe their policyholder is more than 50% at fault (in modified comparative negligence states). However, their initial determination is based on the evidence they have at hand, which is often incomplete. By appealing, you can introduce new evidence to shift the liability percentage.
Essential Evidence for Overturning Liability
- Dashcam Footage: In 2026, high-definition dashcam footage is the "gold standard" for appeals. It provides an objective record that overrides conflicting "he-said, she-said" statements.
- Telemetry Data: Modern vehicles record "black box" data including speed, braking force, and steering angle at the time of impact. If your insurer claims you were speeding, telematics data can prove otherwise.
- Independent Appraisals: If a claim is denied because the insurer believes the damage was "pre-existing," an independent mechanic or appraiser can provide a professional opinion distinguishing old wear-and-tear from fresh collision damage.
Legal Protection and the Duty of Good Faith
Insurance policies are legal contracts. When you pay your premium, the insurance company assumes a "Duty of Good Faith and Fair Dealing." This means they are legally obligated to investigate claims thoroughly, interpret policy language reasonably, and pay valid claims promptly.
An appeal is the first formal step in holding an insurer accountable to this duty. If an insurer denies a claim without a reasonable basis or fails to conduct a proper investigation, they may be acting in "Bad Faith."
The Significance of the Internal Appeal
Most states require you to exhaust the insurance company's internal appeal process before you can file a complaint with the State Insurance Commissioner or pursue a lawsuit. If you skip the appeal, a court may dismiss your case for "failure to exhaust administrative remedies." Therefore, the appeal matters because it preserves your right to take legal action later. It creates a paper trail of your attempts to resolve the dispute reasonably, which is vital if the case ever reaches a judge or jury.
Understanding the Stages of an Appeal
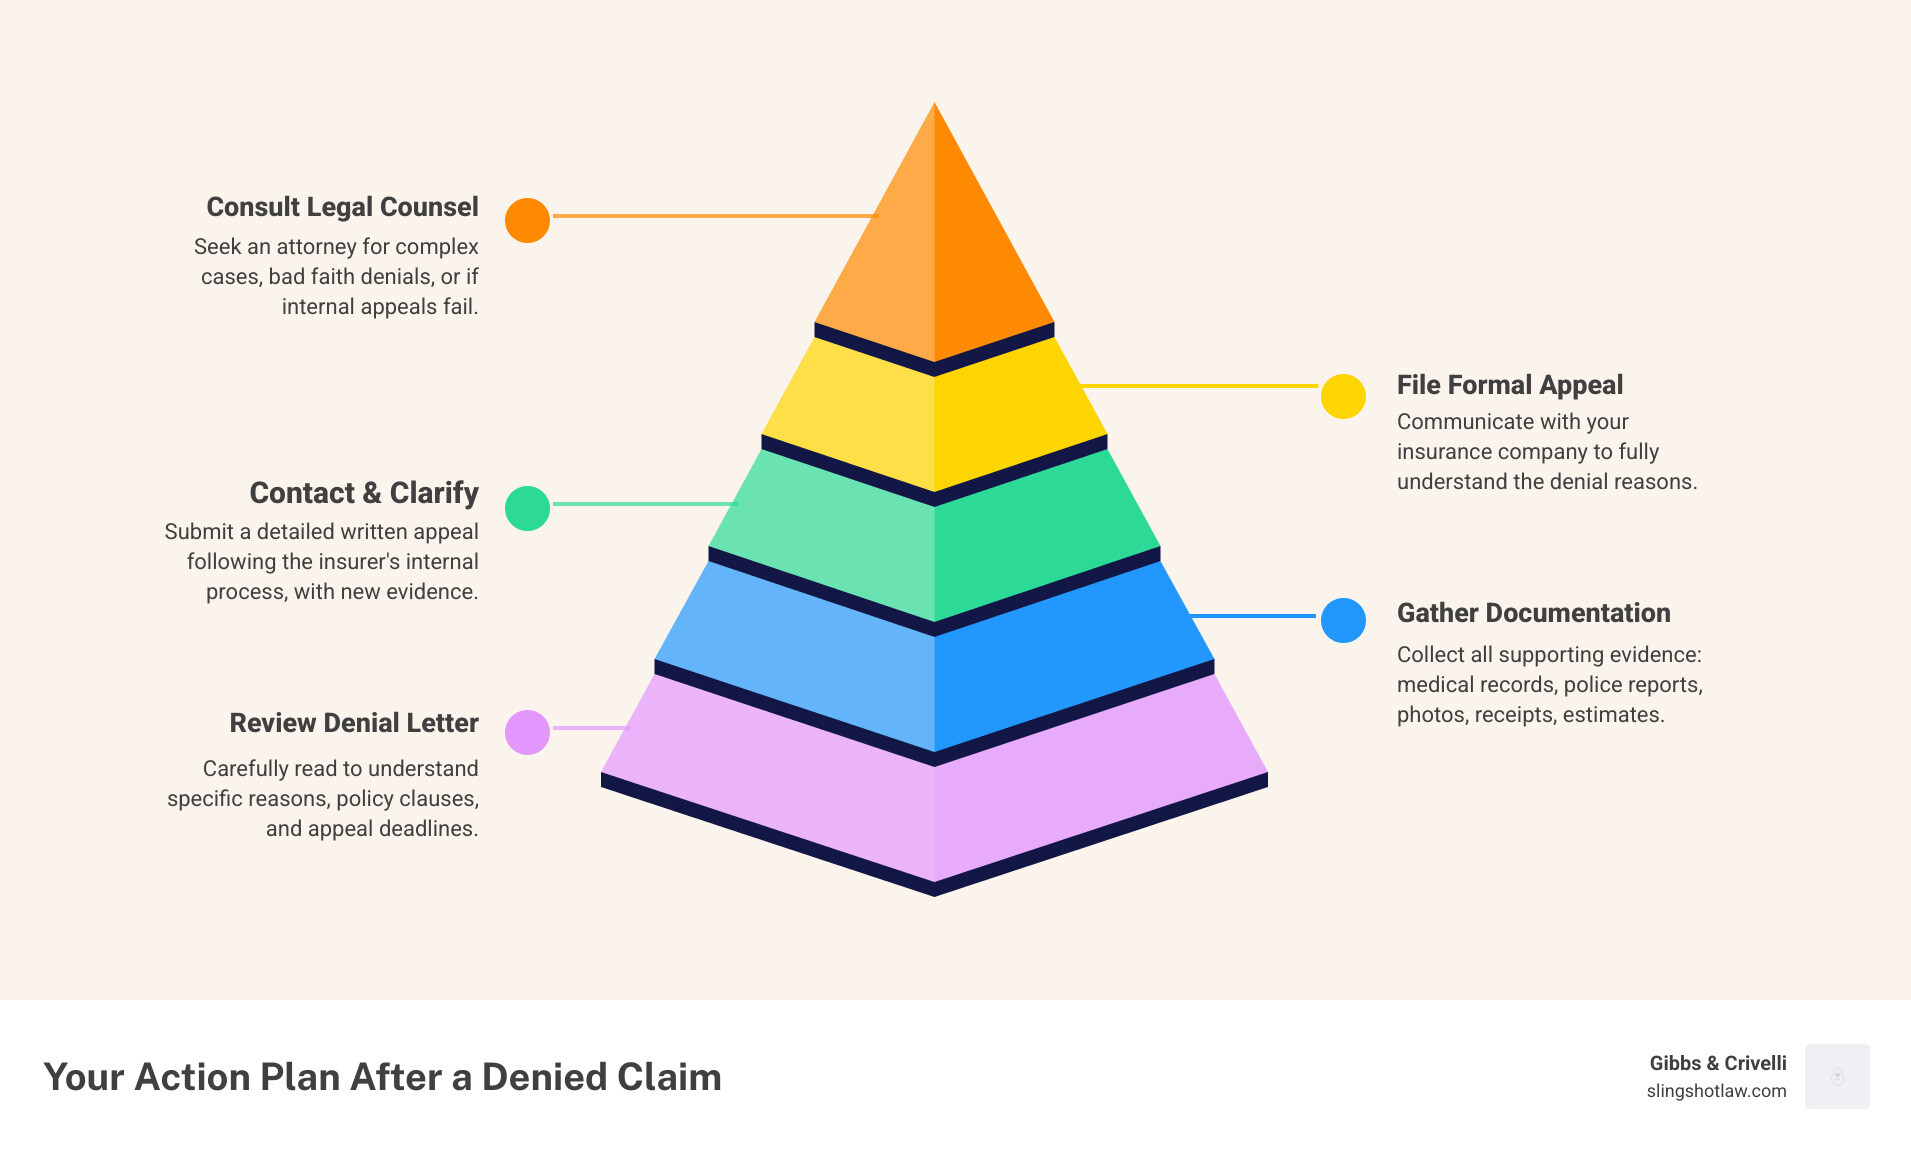
The appeal process is not a single event but a series of escalating steps. Understanding where you stand helps in managing expectations and resource allocation.
| Appeal Stage | Description | Key Participants | Success Indicator |
|---|---|---|---|
| Internal Review | A secondary review by a supervisor or a different adjuster within the same company. | Adjuster, Claims Manager | Correction of clerical errors or policy misinterpretations. |
| External Review | An independent third party (often mandated by the state) reviews the case. | Independent Arbitrator, Policyholder | Binding decision that overrides the insurer's denial. |
| State Regulatory Complaint | Filing a grievance with the State Department of Insurance or Insurance Commissioner. | State Regulator, Insurer's Legal Dept | Investigation into the insurer's patterns of behavior. |
| Litigation/Mediation | Filing a formal lawsuit or entering a court-ordered mediation process. | Attorneys, Judges, Mediators | Settlement or court judgment for damages and legal fees. |
Why "Acceptance" Can Lead to Future Denials
If you accept a denial for an incident where you were not at fault, you are essentially agreeing with the insurer's version of history. This can create a "precedent" within your insurance file. For example, if your claim for a cracked windshield is denied as "maintenance neglect" rather than "road debris damage," and you don't appeal, a future claim for a shattered sunroof might be denied using the same "history of poor vehicle maintenance" logic.
Furthermore, accepting a denial can affect your ability to seek compensation from the other driver's insurance. If your own insurer denies the claim and places you at fault, the other driver's insurer will use that determination as leverage to deny your third-party claim against them. Appealing your own insurer's decision is often the only way to break this cycle and force the other party's carrier to take your demand seriously.
Common Reasons for Denial and the Appeal Counter-Argument
To appeal effectively, you must understand the specific reason for the denial. The "Explanation of Benefits" (EOB) letter will cite a specific policy provision.
Late Reporting
Insurers require "prompt" notification of an accident. If they deny your claim because you waited two weeks to report it, your appeal should focus on why the delay occurred (e.g., medical incapacitation) and, more importantly, prove that the delay did not "prejudice" the insurer's ability to investigate the scene or the vehicles.
Excluded Driver
If a claim is denied because the person driving was not listed on the policy, the appeal matters because it allows you to prove "permissive use." Most policies cover occasional drivers who do not live in your household. If the driver was a guest or a relative visiting from out of town, providing proof of their separate residence can overturn the denial.
Pre-existing Damage
This is a frequent point of contention in 2026 as insurers use photo-analysis AI to scan for old dents. An appeal allows you to present maintenance records, recent photos of the car from a car wash or parking app, or a statement from your regular mechanic to prove the vehicle was in pristine condition prior to the accident.
The Role of Public Adjusters and Legal Counsel
For high-value claims or complex liability disputes, an appeal matters because it provides the opportunity to bring in professionals. A Public Adjuster is an independent professional who works for the policyholder, not the insurance company. They specialize in documenting the full extent of a loss and arguing the technical points of policy language.
In cases involving significant medical bills or permanent disability, an attorney specializing in insurance law becomes essential. They can identify "Bad Faith" practices that a layperson would miss. For instance, if the insurer used a "biased" medical examiner to deny a PIP claim, an attorney can cross-examine that expert's history of always siding with insurance companies.
Strategic Benefits of the Written Appeal Letter
The formal appeal letter is your most powerful tool. It should be dispassionate, fact-based, and evidence-heavy. By drafting a comprehensive appeal, you are signaling to the insurer that you are an informed consumer who knows their rights.
Oversight bodies and internal legal teams at insurance companies often view a well-written appeal as a signal of "litigation risk." If the cost of fighting your appeal (legal fees, man-hours, potential regulatory fines) exceeds the cost of paying the claim, the company may choose to settle the claim as a "business decision." This is why the quality and persistence of your appeal matter—it changes the insurer's cost-benefit analysis.
FAQs
How long do I have to appeal an auto insurance denial?
In 2026, most policies provide a window of 30 to 60 days from the date of the denial letter to file an internal appeal. However, state laws vary, and some jurisdictions allow up to a year for certain types of coverage. It is vital to check the "Right to Appeal" section of your denial notice immediately, as missing this deadline can result in a permanent forfeiture of your right to challenge the decision.
Will appealing a claim denial increase my insurance rates?
The act of appealing itself does not increase your rates. In fact, if your appeal is successful and results in a "not-at-fault" determination, it can prevent the rate hike that usually follows a denied claim where you were blamed by default. Insurance premiums are based on risk profiles; proving you were not the cause of an accident through an appeal actually lowers your risk profile in the eyes of future underwriters.
What should I do if the internal appeal is denied?
If the internal appeal fails, your next step is usually an "external review" or a complaint to your State Insurance Commissioner. Many states have an ombudsman program that provides free mediation services for insurance disputes. If the claim is substantial (e.g., a totaled vehicle or high medical costs), this is the point where consulting with a specialized insurance attorney is highly recommended.
Do I need a lawyer to appeal a simple property damage denial?
Not necessarily. Many property damage appeals are resolved through clear documentation, such as repair estimates and photos. However, if the insurer is stubborn or the "Actual Cash Value" (ACV) they are offering is significantly lower than the market rate for a replacement vehicle in 2026, a lawyer or a public adjuster can provide the leverage needed to reach a fair settlement.
Can I appeal a denial from the other driver's insurance company?
Yes. When the other driver's insurer denies your "third-party claim," they are essentially saying their driver wasn't at fault or their policy doesn't cover the incident. Your "appeal" in this case is often a formal demand letter backed by evidence. If they refuse to budge, your recourse is to file a claim under your own "uninsured/underinsured motorist" coverage or to sue the other driver personally, which triggers their insurer's duty to defend them.
Practical Recommendation
If you receive an auto insurance claim denial, do not treat it as a final decision. Begin by requesting a complete copy of your claim file, including any internal notes and the specific evidence used to justify the denial. Compare this against your policy declarations page to identify inconsistencies. Within 14 days of the denial, submit a formal, written appeal via certified mail that addresses each point of the denial with objective evidence (photos, witness statements, or technical data). If the claim involves more than $10,000 or any personal injury, consult with a qualified insurance professional to ensure your rights are fully protected under the 2026 regulatory guidelines.
Image Gallery
Select an image to open it in a new tab.


Mateo Castillo
Decentralized Finance and E-Payments Strategist
