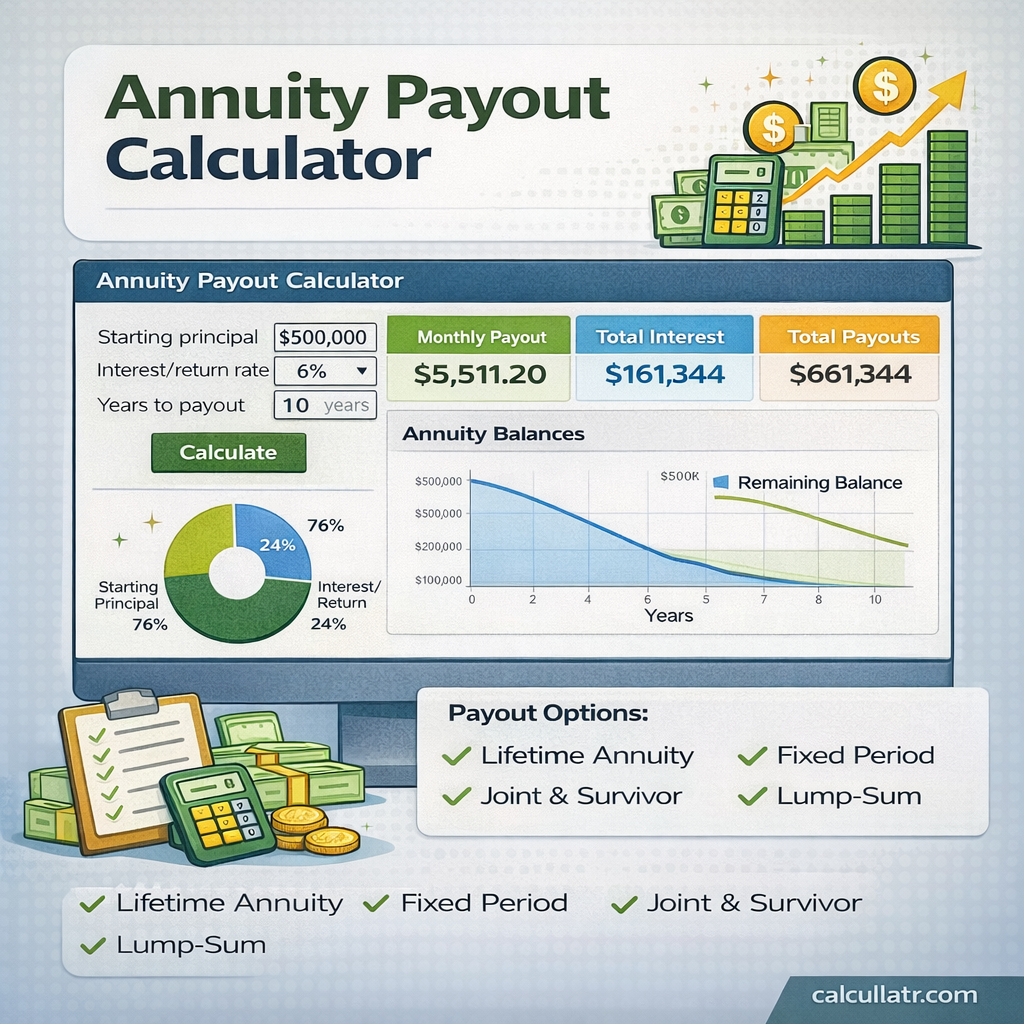
An annuity payout calculator is a digital tool designed to project the stream of future income payments an individual will receive based on specific financial inputs, such as the initial premium, interest rates, and the chosen payout duration. By processing these variables against actuarial tables and internal company formulas, these calculators help prospective annuitants visualize how different contract configurations impact their long-term retirement cash flow.
The Core Mechanics of Annuity Calculations
At its most fundamental level, an annuity payout calculator serves as a bridge between a lump-sum investment and a predictable income stream. When you provide data to an annuity calculator, the tool is not merely performing simple arithmetic; it is modeling a series of complex financial variables that insurance carriers use to determine their liability and your benefit.
The engine of any such calculator relies on the relationship between the principal amount (the amount invested), the assumed rate of return, and the duration of the payout period. Whether you are dealing with a fixed, variable, or indexed annuity, the calculator applies an interest-compounding formula to ensure that the total pool of money is depleted in accordance with the terms of your contract over the specified time frame.
For life-based annuities, the calculation becomes significantly more complex. In these instances, the calculator must integrate actuarial data. This includes life expectancy tables that account for age, biological sex, and sometimes health-related factors. Because the insurance company bears the risk of the individual living longer than statistically projected, the calculator adjusts the payout amount downward to account for the "longevity risk" the insurer assumes.
Essential Inputs Required for Accurate Projections
To obtain a meaningful output from an annuity payout calculator, you must provide accurate data. Minor variations in your input can lead to significant discrepancies in the projected monthly income. Most professional calculators require the following specific data points:
- Initial Investment Amount: This is the total principal you intend to deposit. If you are rolling over funds from a 401(k) or an Individual Retirement Account (IRA), the gross amount—before potential surrender charges or fees—is typically used.
- Current Age: This is a primary driver for payout calculations, particularly for lifetime income streams.
- Payout Start Date: If you are using a deferred annuity, the number of years between your investment and the first payment is crucial, as the principal will grow through interest accumulation during this "accumulation phase."
- Payout Period or Type: You must distinguish between "period certain" (payments for a fixed number of years) and "life only" (payments until death).
- Assumed Interest Rate: Many calculators allow users to adjust the interest rate. It is vital to use conservative estimates to avoid overestimating your future income, especially in volatile market conditions.
Distinguishing Between Annuity Types
The functionality of a payout calculator is highly dependent on the type of annuity being modeled. Understanding these differences is essential for interpreting the results correctly.
Fixed Annuities
With a fixed annuity, the calculator assumes a guaranteed, stable interest rate. The projection is usually quite reliable because the insurer bears the investment risk. The calculator simply applies the guaranteed rate to the principal and distributes it over the chosen term.
Variable Annuities
Variable annuities are tied to sub-accounts, which function similarly to mutual funds. Because the underlying assets fluctuate, a "payout calculator" for a variable annuity is often more of an estimation tool. It might show a range of potential outcomes—optimistic, neutral, and pessimistic—based on historical market performance.
Indexed Annuities
These products offer returns linked to a market index (such as the S&P 500) but often include "caps" or "participation rates" that limit both gains and losses. An accurate calculator for an indexed annuity must be sophisticated enough to apply these complex contractual boundaries to the projected growth of the principal.
Table: Comparison of Annuity Payout Calculation Factors
| Factor | Fixed Annuity | Variable Annuity | Indexed Annuity |
|---|---|---|---|
| Primary Variable | Fixed Interest Rate | Market Performance | Index Performance |
| Risk Bearer | Insurance Company | Annuitant (Investor) | Shared / Limited |
| Output Type | Guaranteed Amount | Projected Range | Estimated Potential |
| Complexity | Low | High | High |
| Predictability | High | Low | Moderate |
How Actuarial Tables Influence Results
When selecting a lifetime income option, the calculator uses mortality tables to estimate your life expectancy. This is the mechanism that differentiates an annuity from a standard investment account. In a bank savings account, you draw down your own principal and interest until the balance reaches zero. In a lifetime annuity, you are participating in a risk pool.
If you pass away earlier than expected, the remaining balance in your "pool" stays with the insurance company to help fund the payments for other participants in the pool who live longer than their actuarial expectation. Conversely, if you live well past your life expectancy, the insurance company continues to pay you from the pool, even if your original principal and earned interest were theoretically exhausted years prior. The calculator models this risk sharing, which is why lifetime payouts are generally lower than "period certain" payouts for the same principal amount.
Common Mistakes When Using Payout Calculators
Users frequently encounter frustration because they fail to account for the "hidden" variables of an annuity contract. Avoiding these common pitfalls will yield much more accurate results:
- Ignoring Fees: Many online calculators omit internal administrative fees, mortality and expense (M&E) charges, and rider costs. Always check if the calculator allows for an "expense ratio" or "annual fee" field.
- Assuming Constant Interest: Especially for variable products, assuming the market will consistently return 7% or 8% can lead to dangerously inaccurate retirement planning. Always run a "stress test" on your calculator by lowering the interest rate assumption to see if the plan remains viable.
- Overlooking Surrender Charges: If you are calculating the payout for an annuity you already own, ensure that you are using the current surrender value, not the total historical premiums paid. Surrender charges can significantly reduce the amount of capital actually available to generate an income stream.
- Failure to Account for Inflation: Unless the annuity has a Cost of Living Adjustment (COLA) rider, the purchasing power of your payout will decrease over time. A calculator may show a steady payment of $2,000 per month, but that amount will buy far fewer goods in 2040 than it does in 2026.
Practical Steps for Effective Utilization
If you are using a calculator provided by a specific insurance company, ensure you have your latest annual statement in front of you. Most companies provide a "benefit base" or "income base" figure, which is often different from the "account value." Using the income base in a calculator will yield a much more accurate projection of your future payments than using the cash surrender value.
If you are in the planning phase and comparing products, use a neutral, independent third-party calculator. These tools often allow for side-by-side comparisons of different insurance carriers' products, enabling you to see how different expense structures affect your long-term outcome.
Frequently Asked Questions
Why does my calculator show different results than my annuity statement? Your statement shows the current account value, while an income calculator uses your "income base." The income base is a contractual value specifically used to determine future payouts and often includes bonuses or growth credits that do not apply to the cash surrender value.
Can a calculator tell me if an annuity is a good investment? No. A calculator only models the mathematical outcome based on the inputs provided. Whether an annuity is a "good" investment depends on your personal financial goals, your risk tolerance, and the specific terms of the contract, which a calculator cannot evaluate.
Do I need to include Social Security in my annuity payout calculation? While you should not input Social Security into an annuity-specific calculator, you should consider the two income streams together. Annuity payouts are often intended to bridge the gap between your essential expenses and your guaranteed income from Social Security and pensions.
Why is my lifetime payout lower than the "period certain" option? The lifetime option includes a longevity guarantee. Because the insurance company assumes the risk that you might live for 30 or 40 years, the payout is structured to be sustainable over a longer, uncertain period, whereas a "period certain" option has a definitive end date.
Recommendation and Next Actions
For the most accurate assessment of your retirement income, use an annuity payout calculator only as a foundational starting point. Once you have a general understanding of the income ranges, contact your financial advisor to review the specific contract documents. Verify that any "guaranteed income riders" are correctly accounted for, as these can drastically change the payout figures compared to a basic annuity calculation. If you are comparing multiple products, always ask for an "illustration" from each carrier, as these documents are the definitive legal projections used to set your actual contract payments.

Image Gallery
Select an image to open it in a new tab.
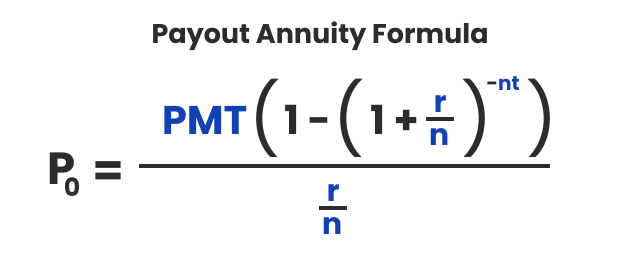
Lars Thomsen
Global Labor Markets and Economic Strategy Editor
