99517 Auto Insurance Coverage Explained: Regulations, Requirements, and Policy Choices
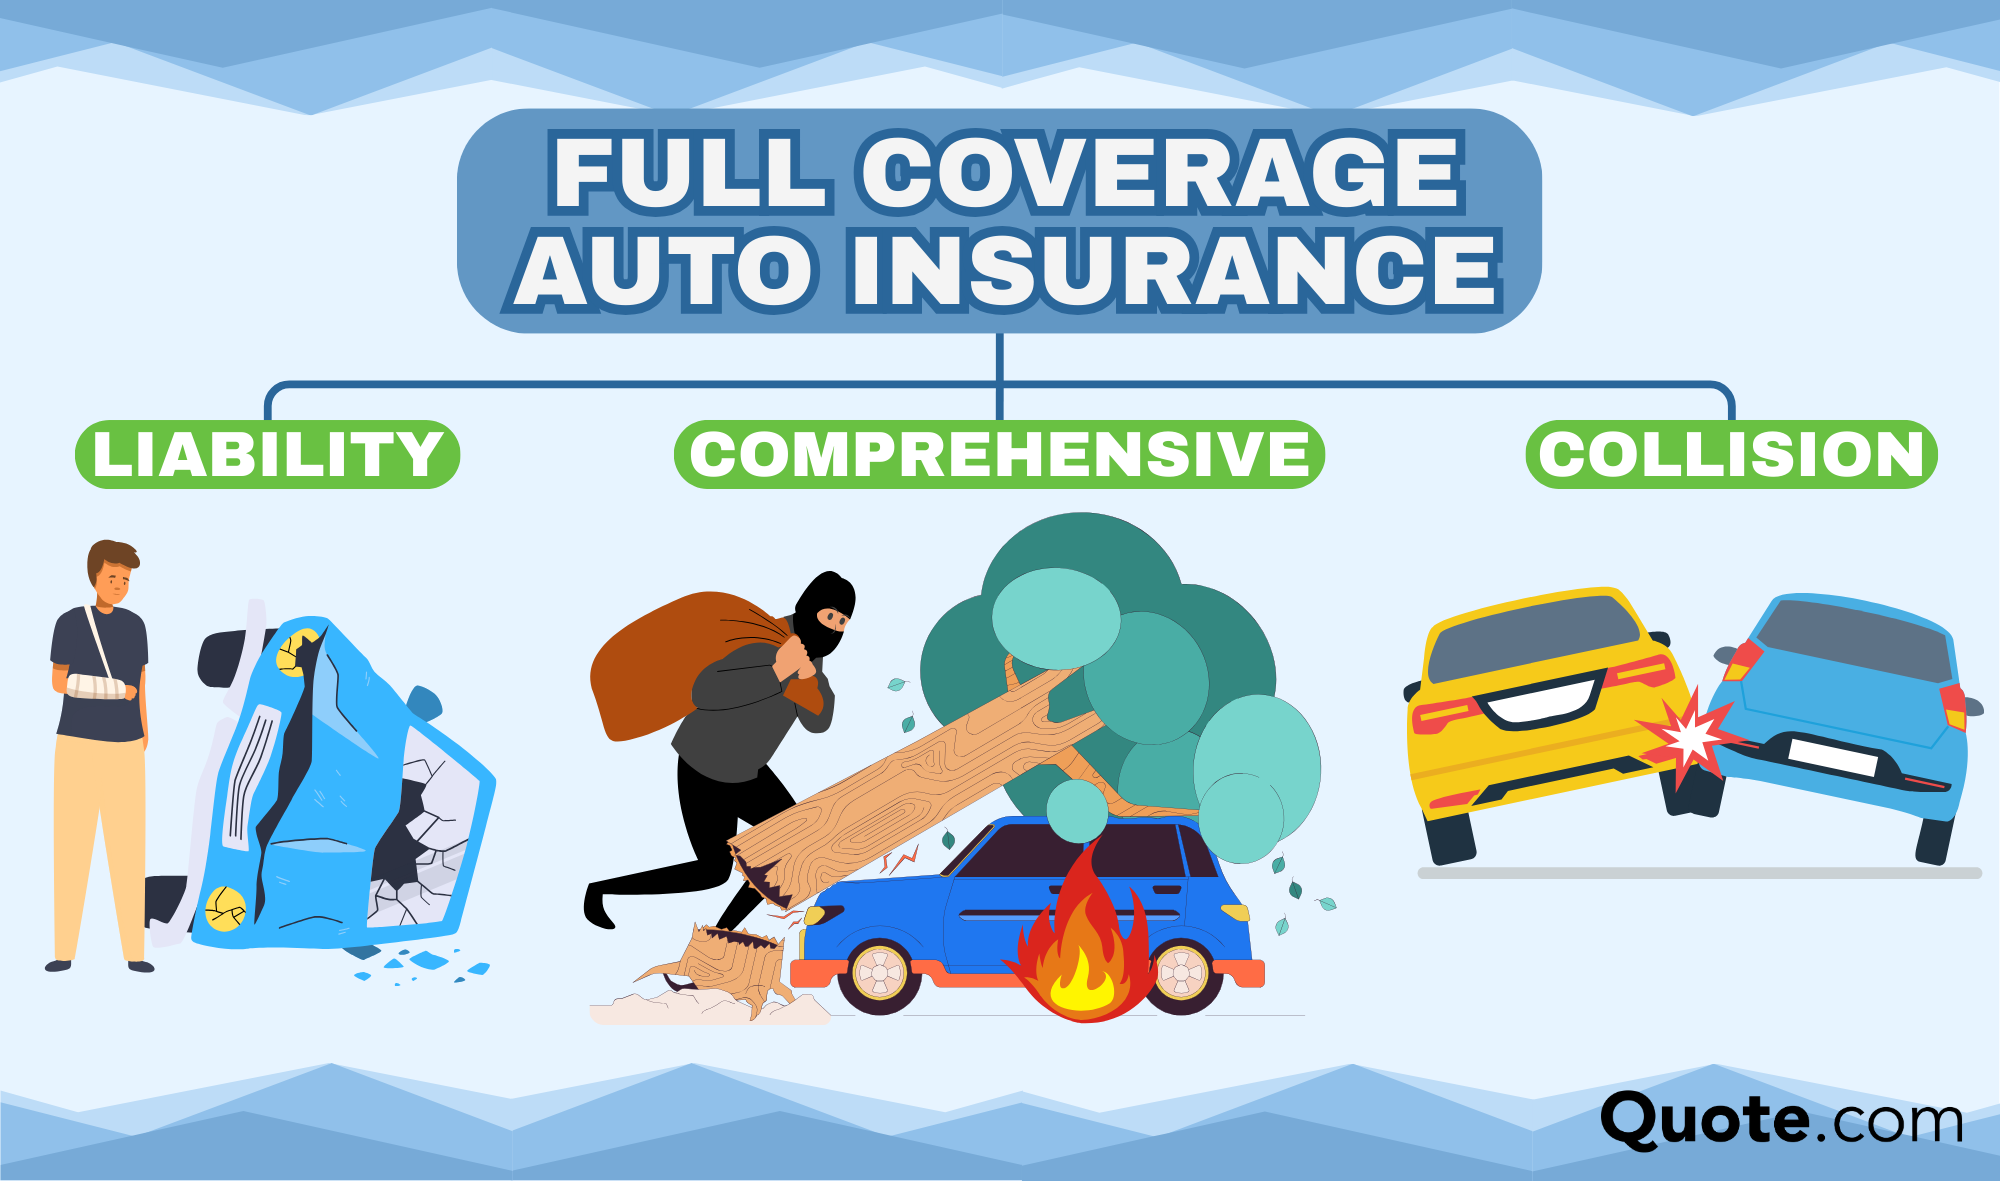
Navigating auto insurance in the 99517 ZIP code—which encompasses the rural areas west of Anchorage, Alaska, including Skookum, Fire Island, and parts of the Cook Inlet region—requires understanding both Alaska state mandates and local environmental risk factors. Alaska law requires all drivers to carry minimum liability coverage, while local geography, severe winter weather, and wildlife hazards necessitate exploring comprehensive and collision options to ensure full financial protection.
Understanding Alaska Auto Insurance Regulations and the 99517 Context
Auto insurance regulations in Alaska are established at the state level by the Alaska Division of Insurance, meaning that drivers residing in the 99517 ZIP code must comply with statewide statutory minimums. However, geographic context plays a vital role in how insurance carriers underwrite policies for this specific region. The 99517 area includes unique terrains, coastal weather patterns near Cook Inlet, and remote transit corridors where road maintenance can differ significantly from major metropolitan hubs like downtown Anchorage.
State law mandates that every registered motor vehicle operated on public roadways must carry valid liability insurance. This requirement is designed to ensure that if a driver is at fault in an accident, funds are available to compensate other parties for bodily injury, death, or property damage. Operating a vehicle without insurance in Alaska carries severe administrative penalties, including fines, license suspension, and potential impoundment of the vehicle. Beyond compliance, selecting the right policy involves balancing state legal minimums against personal financial exposure in a region prone to severe weather events and wildlife collisions.
Minimum Statutory Liability Requirements in Alaska
To legally drive within the 99517 ZIP code and across Alaska, motorists must purchase a policy that meets or exceeds the state's mandatory liability limits. These limits are commonly expressed as a three-part ratio. For Alaska, the mandatory minimum liability insurance limits are:
- $50,000 for bodily injury or death of one person in any one accident.
- $100,000 for total bodily injury or death liability when two or more people are injured in a single accident.
- $25,000 for property damage liability resulting from any single accident.
These figures are often written shorthand as 50/100/25. While purchasing these minimum limits satisfies the legal requirement to operate a vehicle, financial experts and insurance professionals frequently caution that these amounts can be easily exhausted in a serious collision. Medical costs, vehicle replacement values, and legal fees associated with an at-fault accident regularly exceed these thresholds, leaving unprotected motorists personally liable for the remaining balance.
Essential Policy Coverages Beyond State Minimums
Relying solely on liability insurance leaves a driver's own vehicle and personal health unprotected. To safeguard against the unique hazards present in the 99517 region—such as slick winter ice, heavy snowfall, and encounters with large wildlife like moose—drivers typically bundle several additional coverage types into their auto insurance policies.
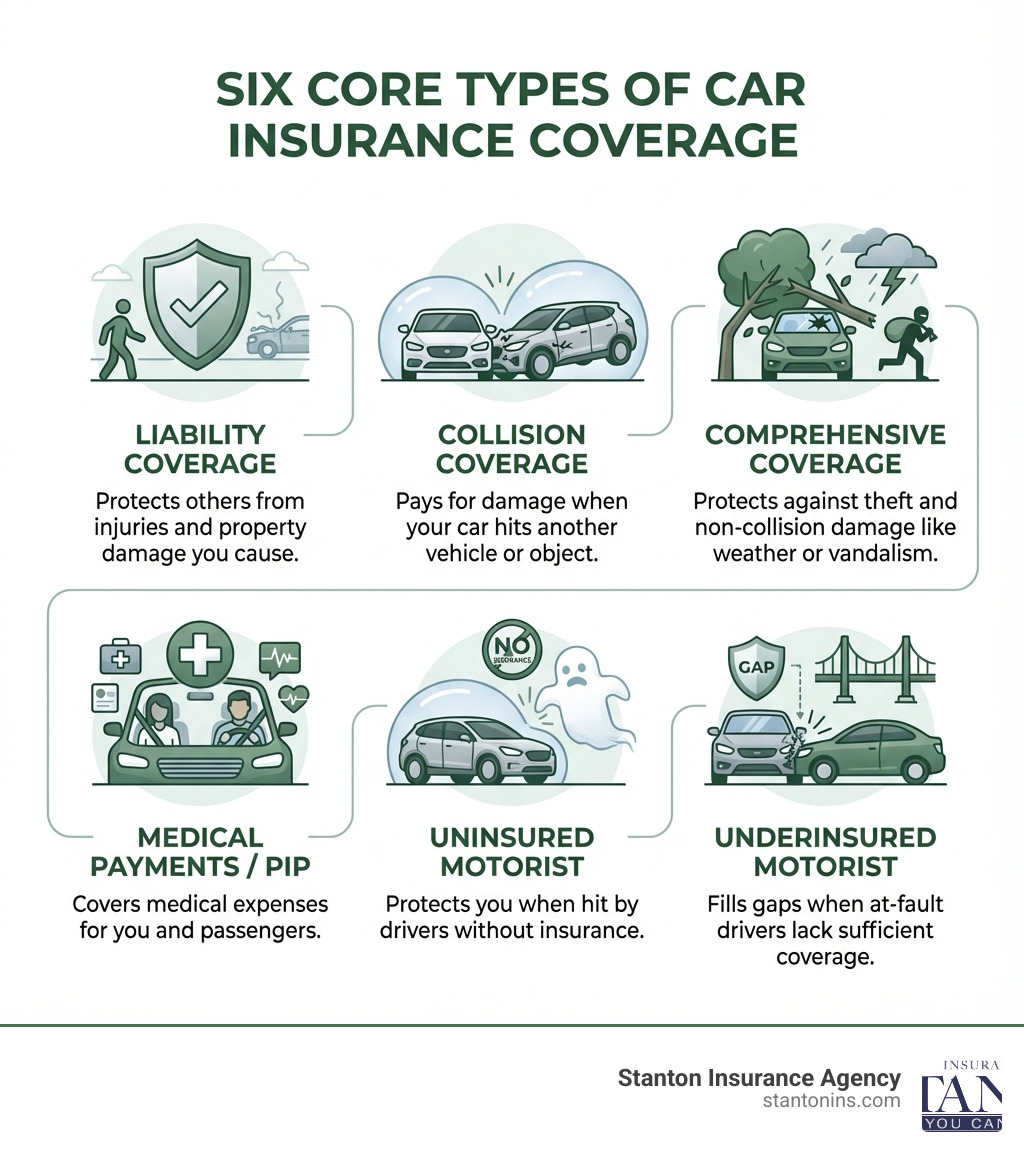
Collision Coverage
Collision coverage pays for damage to your own vehicle when it strikes another car or an object, such as a guardrail, tree, or snowbank. Given the challenging winter driving conditions in the 99517 area, single-vehicle slide-offs into snowbanks or ditches are common. Collision insurance ensures that repair costs or the actual cash value of the vehicle are covered, minus the chosen deductible amount.
Comprehensive Coverage
Often referred to as "other than collision," comprehensive coverage protects your vehicle against damage caused by incidents outside of traditional traffic crashes. In Alaska, this coverage is vital due to high rates of wildlife strikes (particularly moose and bears), flying gravel on unpaved or thawing roads, falling tree branches, vandalism, theft, and severe weather damage.
Uninsured and Underinsured Motorist (UM/UIM) Coverage
Despite state laws, a percentage of motorists drive without any insurance or carry insufficient limits to pay for damages they cause. Uninsured Motorist (UM) and Underinsured Motorist (UM/UIM) coverages step in to pay for your medical bills, lost wages, and sometimes vehicle repairs if you are hit by a driver who lacks adequate insurance. Given the financial risks of severe accidents, adding high limits of UM/UIM protection is a critical safety net.
| Coverage Type | What It Protects | Mandatory in Alaska? | Recommended For 99517 Residents |
|---|---|---|---|
| Bodily Injury Liability | Other drivers/pedestrians injured in an accident you cause | Yes (50/100 minimum) | Mandatory (Consider higher limits) |
| Property Damage Liability | Other people's property damaged in an accident you cause | Yes ($25,000 minimum) | Mandatory (Consider higher limits) |
| Collision | Your vehicle after a crash or rollover | No | Highly Recommended |
| Comprehensive | Your vehicle from theft, weather, fire, or animal strikes | No | Highly Recommended |
| Uninsured Motorist (UM) | Your medical bills if hit by an uninsured driver | No | Highly Recommended |
How Location and Environment Influence 99517 Insurance Rates
Insurance companies use sophisticated actuarial models to determine premiums, and geographic location is a primary rating factor. For residents in the 99517 postal code, several environmental and infrastructural factors directly influence rate calculations:
- Weather and Road Conditions: Sub-zero temperatures, black ice, heavy snowfall, and extended periods of winter darkness increase the statistical probability of accidents. Insurers factor these regional loss histories into base rates.
- Wildlife Population Density: Rural and semi-remote areas adjacent to the Anchorage bowl experience frequent interactions with large wildlife. Colliding with a moose can cause catastrophic structural damage to a passenger vehicle and severe occupant injuries, leading to high claim payouts for comprehensive coverage.
- Repair and Towing Costs: Proximity to repair facilities, specialized parts availability, and the distance required to tow a disabled vehicle from remote sections of the 99517 area can elevate claim costs. Insurers adjust premiums to reflect these logistical expenses.
- Commuting Patterns and Mileage: Annual mileage estimates affect risk exposure. Drivers commuting into Anchorage from the western outskirts face dense commuter traffic during peak hours, increasing collision exposure compared to strictly local rural driving.
Factors That Lower Your Auto Insurance Premiums
Securing comprehensive coverage in the 99517 region does not mean accepting exorbitant rates. Insurers offer numerous discounts and rating adjustments that drivers can leverage to manage premium costs effectively:
- Safe Driving Records: Maintaining a clean driving record free of at-fault accidents and speeding citations for three to five years is the most reliable way to secure lower rates.
- Deductible Adjustments: Opting for a higher deductible—such as $1,000 instead of $250—lowers your monthly or semi-annual premium. However, policyholders must ensure they have that cash saved to cover the out-of-pocket expense if a claim occurs.
- Multi-Policy Bundling: Purchasing auto insurance from the same carrier that insures your home, renters, or secondary vehicles typically triggers significant multi-policy discounts.
- Vehicle Safety Features: Anti-lock brakes, factory-installed passive restraint systems, daytime running lights, and advanced anti-theft devices can qualify vehicles for specific insurance discounts.
- Low Mileage Discounts: If your vehicle is driven less than the national or regional average annual mileage, reporting this to your insurer can reduce your baseline rate.
Steps to Verify and Maintain Active Coverage Compliance
Ensuring that your auto insurance policy remains valid and fully compliant with Alaska regulations requires regular review and adherence to administrative steps:
- Review Policy Declarations Page: Annually inspect your declarations page to verify that coverage limits, deductibles, and listed drivers are accurate. Ensure that vehicles kept at secondary residences or driven by newly licensed household members are properly declared.
- Carry Proof of Insurance: Alaska law requires drivers to present proof of insurance upon demand by law enforcement or during vehicle registration renewals with the Alaska Division of Motor Vehicles (DMV). Keep digital or physical insurance cards accessible in the vehicle.
- Report Address Changes Immediately: If you move within the 99517 area or relocate elsewhere in Alaska, notify your insurer immediately. Failing to update your residential address can lead to rating errors or, in worst-case scenarios, claim denials if the insurer determines the vehicle's primary garage location was misrepresented.
- Maintain Continuous Coverage: Avoid gaps in coverage, even if a vehicle is temporarily stored or not being driven during winter months. Lapses in coverage lead to higher future premiums, cancellation of registration privileges by the state, and lack of protection against unexpected garage or weather damage.
Frequently Asked Questions
What are the minimum legal auto insurance limits in Alaska?
Alaska law requires a minimum liability coverage split of 50/100/25. This means $50,000 for bodily injury per person, $100,000 for total bodily injury per accident, and $25,000 for property damage per accident. These limits represent the bare legal minimum required to operate a vehicle on public roads.
Does standard auto insurance in 99517 cover hitting a moose?
Hitting a moose or other large animal is classified as a comprehensive claim, not a collision claim. If you carry comprehensive coverage on your policy, damage caused by hitting an animal will be repaired after you pay your chosen comprehensive deductible. Without comprehensive coverage, you must pay for all vehicle repairs out of pocket.
How do winter driving conditions in the 99517 area affect my insurance rates?
Insurance companies calculate premiums based on regional loss data, which includes historical accident rates linked to severe winter weather, ice, and reduced visibility in the region. While you cannot change the local climate, you can offset higher base rates by maintaining a clean driving record, bundling policies, and selecting higher deductibles.
Is uninsured motorist coverage required in Alaska?
Uninsured motorist (UM) coverage is not legally mandated by the state of Alaska for purchase, but insurance companies are legally required to offer it to you in writing. You have the right to reject it, but doing so removes a vital financial cushion if an uninsured or hit-and-run driver injures you or damages your vehicle.
What should I do immediately after an auto accident in Alaska?
First, ensure everyone is safe and call 911 if there are injuries or significant property damage. Alaska law requires you to report accidents resulting in injury, death, or total property damage exceeding $2,000 to local law enforcement. Exchange contact, insurance, and vehicle information with the other drivers, document the scene with photos if safe to do so, and notify your insurance company as soon as possible to start the claims process.
Image Gallery
Select an image to open it in a new tab.

Mateo Castillo
Decentralized Finance and E-Payments Strategist
