Understanding What the Interest Rate on a Personal Loan Means for Your Financial Health
The interest rate on a personal loan represents the annual cost you pay to a lender for borrowing money, expressed as a percentage of the principal amount. It functions as the price of credit, determining both your monthly payment amount and the total interest expense accumulated over the life of the loan.
When you take out a personal loan, you are essentially entering into a contractual agreement to borrow a set sum of money, which you must repay with interest over a predetermined period. While many borrowers focus exclusively on the monthly payment, the interest rate is the primary mechanical factor that dictates how much that debt will cost you in the long run. Understanding this rate requires moving beyond the basic percentage figure to look at how it interacts with compounding, loan terms, and your specific credit profile.
The Mechanics of Interest Rates
At its core, an interest rate is the fee a lender charges for the risk of lending you capital. This rate is usually quoted as an Annual Percentage Rate (APR), though it is important to distinguish between the two. The interest rate is the cost of the principal balance alone, whereas the APR is a broader metric that includes the interest rate plus any mandatory fees—such as origination or processing fees—expressed as an annual cost.
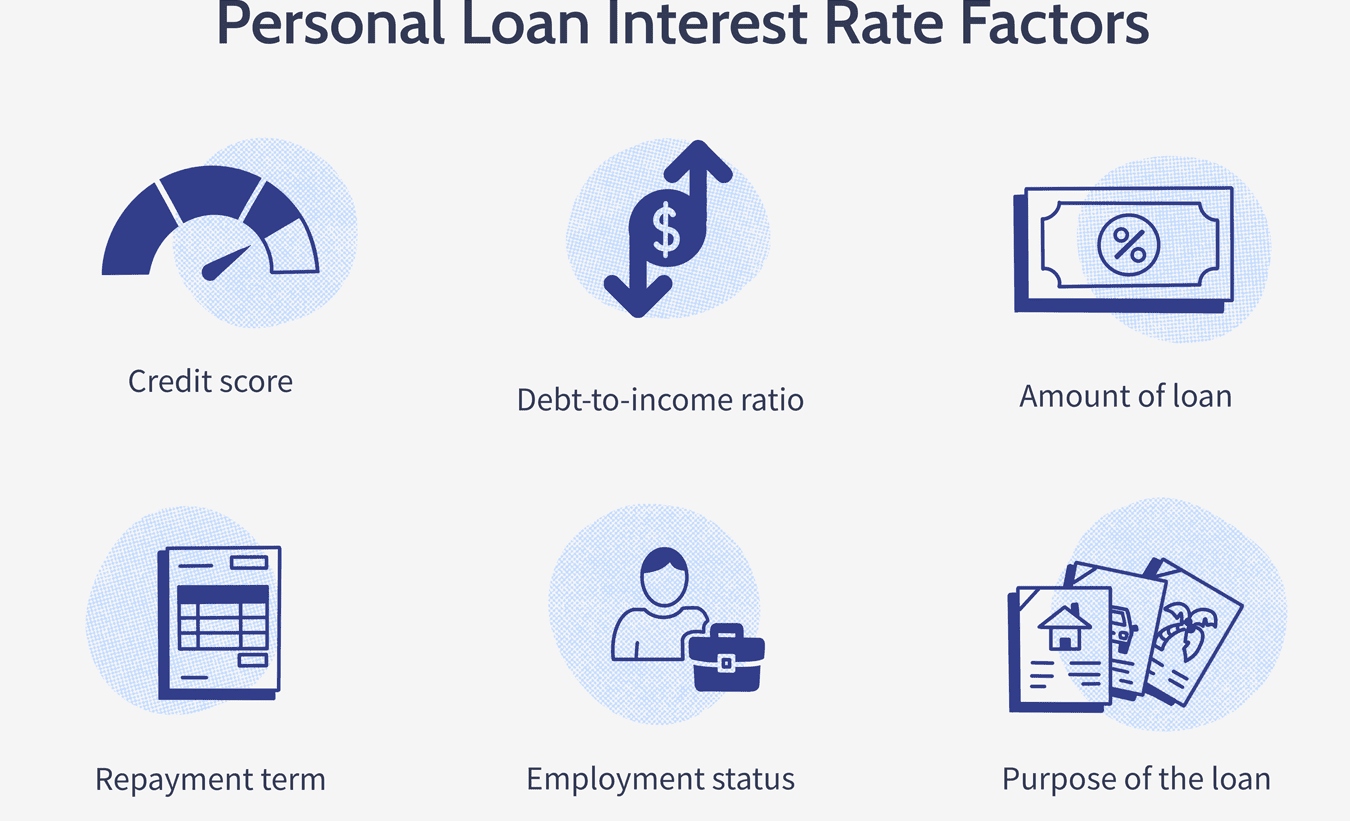
When you apply for a loan in 2026, lenders use sophisticated algorithms to assess your creditworthiness. Factors such as your credit score, debt-to-income (DTI) ratio, employment history, and current market conditions influence the rate you are offered. A higher credit score generally qualifies you for a lower interest rate because it signals to the lender that you are a lower-risk borrower. Conversely, if your credit history shows missed payments or high levels of existing debt, the lender may assign a higher rate to offset the increased risk of default.
Fixed vs. Variable Interest Rates
Not all personal loans operate with the same type of interest structure. Before signing a loan agreement, you must verify whether your rate is fixed or variable.
- Fixed Interest Rates: With a fixed-rate loan, the interest percentage remains constant throughout the entire repayment term. This provides predictability, as your monthly principal and interest payments remain identical from the first month to the last. This structure is generally preferred by those who want to stabilize their monthly budget.
- Variable Interest Rates: These rates are tied to an external benchmark, such as the Prime Rate or the Secured Overnight Financing Rate (SOFR). If the benchmark rate fluctuates, your interest rate—and consequently your monthly payment—will move up or down accordingly. While a variable rate might start lower than a fixed rate, it carries the inherent risk of increasing over time, potentially making the loan more expensive than anticipated.
How Interest Impacts Your Total Repayment
The interest rate does not exist in a vacuum; it works in tandem with the loan term (the duration of time you have to pay back the money). A common mistake among borrowers is choosing a longer loan term simply to lower the monthly payment. While a longer term reduces the pressure on your immediate cash flow, it often results in paying significantly more in total interest over time.
Because interest is usually calculated on the remaining principal balance, paying off a loan faster reduces the amount of time that interest has to accrue. Therefore, a loan with a slightly higher monthly payment but a shorter term will almost always be cheaper than a loan with a lower monthly payment stretched over a longer term, assuming the interest rates are similar.
The Role of Origination Fees and APR
In the financial market of 2026, it is common for lenders to charge an origination fee. This is a one-time fee deducted from your loan proceeds or added to the total balance at the time of funding. Because this fee changes the "effective" cost of your borrowing, you should always compare the APR rather than just the interest rate.
For example, if Lender A offers an 8% interest rate with a 5% origination fee, and Lender B offers an 8.5% interest rate with no origination fee, the "cheaper" loan might actually be the one with the higher rate. Always check the Truth in Lending Act (TILA) disclosure provided by your lender, which is required by law to clearly state the APR and the total finance charge you will pay.
Comparison Table: Interest Rate Dynamics
| Feature | Fixed-Rate Loan | Variable-Rate Loan |
|---|---|---|
| Payment Predictability | High; payment never changes. | Low; payment fluctuates with benchmarks. |
| Risk Profile | Borrower carries no market risk. | Borrower carries interest rate risk. |
| Initial Cost | Often slightly higher. | Often starts lower to attract borrowers. |
| Suitability | Best for long-term budgeting. | Best for short-term borrowing if rates drop. |
Prerequisites for Securing a Favorable Rate
Securing the most competitive rate requires proactive financial management. Lenders are not mandated to give you their lowest advertised rate; they offer rates based on the risk tier you fall into at the time of application.
- Check Your Credit Report: Before applying, review your report for errors that might be artificially suppressing your score. Dispute any inaccuracies with the credit bureaus.
- Reduce Debt Utilization: If possible, pay down existing credit card balances. Lowering your DTI ratio shows lenders that you have the capacity to take on new debt without overextending yourself.
- Shop Around: Financial institutions have different lending criteria. Do not accept the first offer you receive. Apply with multiple lenders within a short window (typically 14 to 45 days) to minimize the impact on your credit score, as these inquiries are often grouped as a single event for scoring purposes.
Common Pitfalls to Avoid
Many borrowers fall into the trap of focusing solely on the "monthly payment" metric. While budgeting is essential, ignoring the total cost of credit can lead to "debt traps" where the borrower pays double or triple the principal amount over several years. Another pitfall is failing to read the fine print regarding prepayment penalties. Some lenders charge a fee if you pay off your loan early. If you plan to pay off the loan in large chunks, ensure your contract has "no prepayment penalty" clauses.
Understanding Your Personal Loan Contract
By law, lenders must provide you with a loan agreement that details every aspect of the financial obligation. Before signing, ensure you verify the following components:
- Principal Amount: The exact amount you are borrowing.
- Total Interest Paid: The dollar amount of interest you will pay over the entire term if you follow the standard schedule.
- Late Fee Policy: The amount charged if a payment is missed.
- The Repayment Schedule: The date each payment is due.
Financial Advice Limitation
The information provided here is for educational purposes and does not constitute professional financial, tax, or legal advice. Interest rate products are subject to specific jurisdictional laws and institutional policies. Before committing to a loan, consider consulting with a qualified financial advisor who can assess your specific situation, debt capacity, and long-term financial goals.
Frequently Asked Questions
Does a higher credit score always guarantee a lower interest rate? Not always, but it significantly improves your chances. While credit score is the primary driver, lenders also look at income stability and current debt load. Even with an excellent score, other factors like your total monthly debt obligations may influence the final rate offered.
How often does a variable interest rate change? This depends on the specific terms of your loan contract. Most variable-rate personal loans adjust monthly or quarterly based on the movement of the underlying index (e.g., the Prime Rate). Your lender is required to provide notification before any change in your required payment amount.
Can I refinance a personal loan if interest rates drop? Yes. If market interest rates decrease or your credit score improves significantly, you may be able to refinance your existing loan with a new one at a lower rate. However, ensure the savings from the lower interest rate outweigh any new origination fees associated with the new loan.
Is the interest rate on a personal loan tax-deductible? Generally, interest on personal loans is not tax-deductible in the United States. Unlike mortgage interest or certain student loan interest, interest paid on personal debt used for consumption is typically considered a personal expense and does not qualify for tax deductions.
What is a "good" interest rate for a personal loan? What constitutes a "good" rate is relative to the economic environment of 2026 and your specific credit profile. A rate that is considered competitive for a borrower with "fair" credit will be significantly higher than a rate offered to someone with "excellent" credit. Always compare your offer against current national averages for your credit tier.
Next Steps for Borrowers
If you are currently evaluating a loan, your immediate next step is to use an online loan calculator. Input the principal, the interest rate, and the term of the loan you are considering to see the total interest cost. Compare this against your monthly budget to ensure that the payment is sustainable. If the total interest cost seems prohibitive, look for ways to shorten the term or increase your down payment, if applicable. Always prioritize lenders that provide transparent TILA disclosures and clearly define their fee structures.

Image Gallery
Select an image to open it in a new tab.

Ingrid Bjornson
Global Cyber Policy and Regulation Analyst
