
Term life insurance via Bickford Insurance provides a fixed death benefit over a specified period, typically ranging from 10 to 30 years. As an independent agency, Bickford helps clients navigate multiple carriers to find the most competitive rates for their specific health profile and financial goals in 2026. This coverage offers pure protection without the complex investment components of permanent policies.
The Role of Bickford Insurance in Term Life Coverage
When exploring term coverage, the choice of an agency is as critical as the choice of the policy itself. Bickford Insurance operates as an independent brokerage, which fundamentally changes the consumer experience compared to "captive" agencies that only sell one brand. In 2026, the value of an independent agent lies in their ability to scan the entire marketplace—including major national carriers and specialized regional providers—to find a policy that fits a client’s unique "risk bucket."
By working with Bickford, applicants gain access to a professional needs analysis. This process involves calculating not just immediate funeral costs, but long-term liabilities such as mortgage balances, tuition fees, and income replacement for surviving spouses. Because Bickford is not beholden to a single insurance company, their loyalty remains with the policyholder, ensuring that the term length and coverage amount are optimized for the client’s budget rather than a corporate quota.
Defining Term Life Insurance: Pure Protection
Term life insurance is often described as the most straightforward form of life insurance. It is designed to provide financial security for a "term" or a specific number of years. If the insured person passes away during this window, the insurance company pays a tax-free death benefit to the named beneficiaries. If the term expires and the insured is still living, the coverage simply ends, unless a renewal or conversion option is exercised.
Level Premium Term Insurance
The most common type of term coverage offered through Bickford is "Level Premium Term." This means that your monthly or annual premium is guaranteed to remain the same for the entire duration of the policy. Whether you are in the first year of a 20-year policy or the nineteenth, your cost will not increase, even if your health declines. This predictability is a cornerstone of financial planning in 2026, allowing families to lock in low rates while they are young and healthy.
Decreasing Term Insurance
In some instances, Bickford may recommend a decreasing term policy. This is often used for mortgage protection. As the balance of your debt decreases over time, the death benefit of the policy also decreases, though the premium usually remains level. This is a targeted tool for those who specifically want to ensure a debt is cleared if they are no longer there to pay it.

Key Features of 2026 Term Policies at Bickford
The insurance landscape in 2026 has integrated advanced technology and more flexible policy language than in previous decades. When you secure term coverage through an agency like Bickford, you are looking at several modernized features:
- Accelerated Death Benefits: Most modern term policies include "living benefits." If the insured is diagnosed with a terminal illness, they may be able to access a portion of the death benefit while still alive to cover medical costs or end-of-life care.
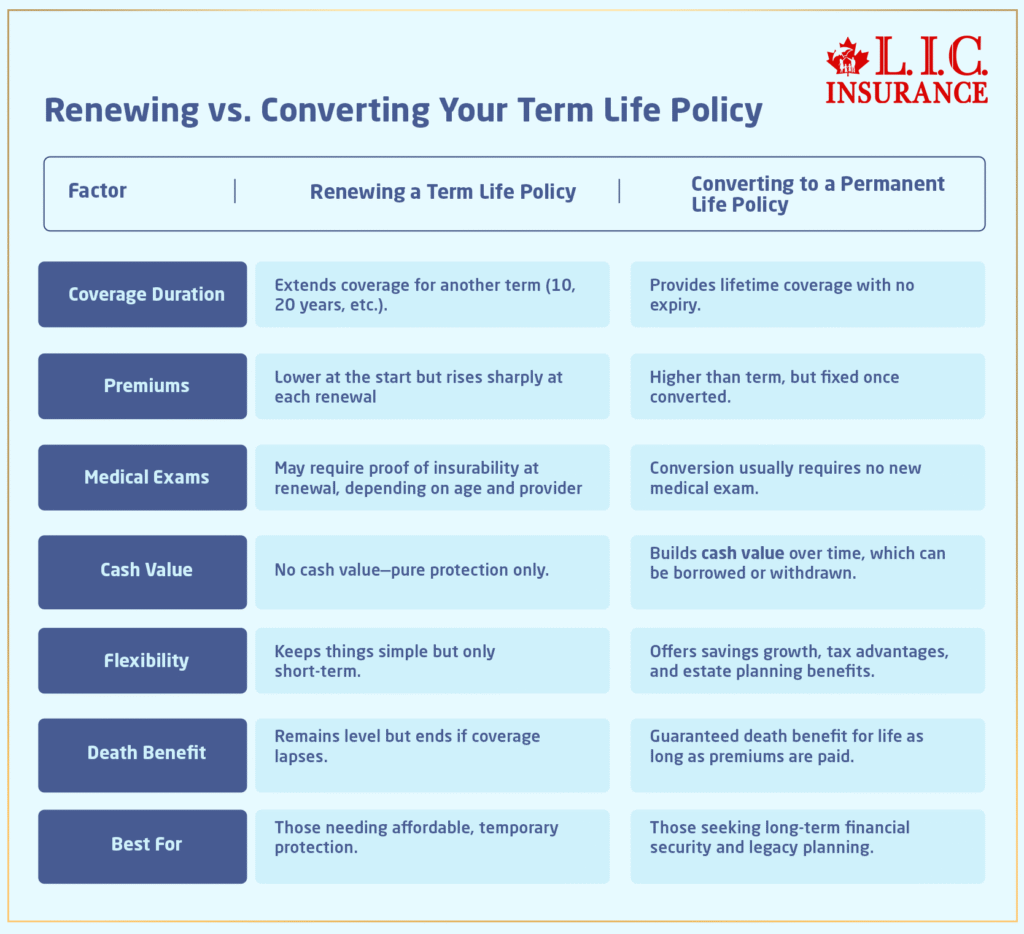
- Convertibility Options: A crucial feature to look for is the "conversion rider." This allows you to convert your term policy into a permanent (whole or universal) life insurance policy at the end of the term without undergoing a new medical exam. This is vital if you develop a health condition that would otherwise make you uninsurable later in life.
- Renewability: Some policies offer "guaranteed renewability," allowing you to extend coverage on a year-to-year basis after the initial term expires, though premiums typically spike significantly at that point.
Factors Influencing Your Term Life Premiums
When you apply for coverage through Bickford, several variables will determine your monthly premium. Understanding these can help you prepare for the underwriting process.
Age and Health Status
Age is the primary driver of cost. Every year you wait to purchase life insurance, the premium increases. Health is the second major factor. In 2026, underwriting has become more sophisticated, often using "attained age" and digital health records to determine risk. Bickford agents look at:
- Cardiovascular health: Blood pressure and cholesterol levels.
- Body Mass Index (BMI): Height-to-weight ratios.
- Tobacco Use: Smokers can expect to pay two to three times more than non-smokers. This includes vaping and nicotine replacement therapies in many jurisdictions.
Term Length and Coverage Amount
The longer the term and the higher the death benefit, the higher the premium. A $1,000,000 policy for 30 years carries significantly more risk for the insurer than a $250,000 policy for 10 years. Bickford helps clients find the "sweet spot" where coverage is sufficient to protect the family but the premium remains affordable.
Lifestyle and Occupation
High-risk hobbies (such as private aviation or technical SCUBA diving) or dangerous occupations can lead to "ratings," which are surcharges added to the base premium. Bickford's expertise involves knowing which carriers are "friendlier" toward specific risks, such as certain medical conditions or hobbies.
Comparing Term Insurance Options
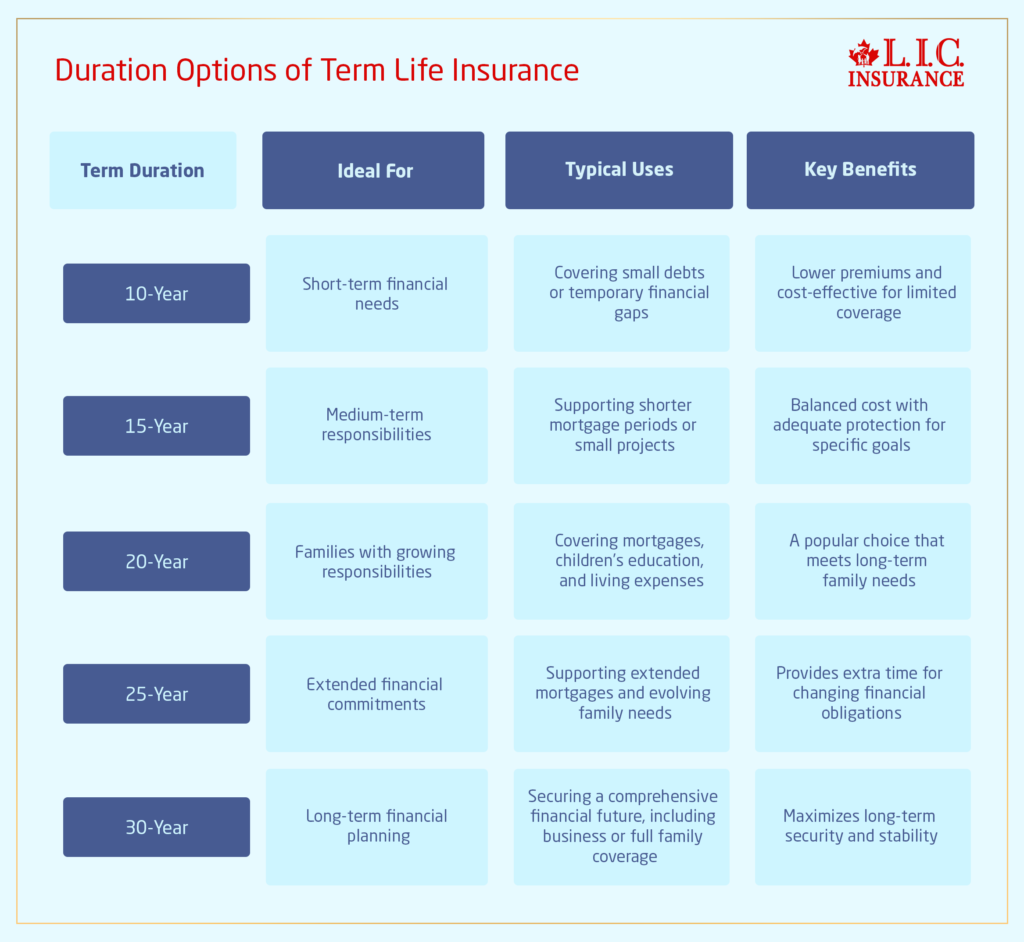
The following table outlines the common term lengths available through Bickford and the typical financial milestones they are designed to protect.
| Term Length | Ideal For | Primary Goal |
|---|---|---|
| 10-Year Term | Older adults or those with short-term debt | Protecting a small remaining mortgage or business loan. |
| 15-Year Term | Parents of teenagers or mid-career professionals | Ensuring children reach adulthood and college is funded. |
| 20-Year Term | New homeowners or young families | Covering the bulk of a 30-year mortgage and child-rearing years. |
| 30-Year Term | Newlyweds and young professionals | Providing long-term peace of mind throughout the entire career. |
| Annual Renewable | Individuals between jobs or in transition | Short-term gap coverage that is renewed every 12 months. |
The Underwriting Process at Bickford Insurance
Underwriting is the process by which an insurance company evaluates the risk of insuring you. When working with Bickford, this process has been streamlined by 2026 standards, but it still follows a rigorous path.
1. The Application and Needs Analysis
The process begins with a conversation with a Bickford agent. You will provide basic information and determine how much coverage you need. You will then fill out a formal application with the selected carrier.
2. Medical Evidence
Depending on the amount of coverage and the carrier, you may undergo "Accelerated Underwriting," which uses data from your medical records and prescription history to approve you instantly. If a traditional exam is required, a technician will visit your home to collect blood and urine samples and record your vitals.
3. Actuarial Review
The insurance company’s underwriters review all the data. They check the Medical Information Bureau (MIB) and motor vehicle records. They look for patterns that suggest higher mortality risk.
4. Policy Issue and "Free Look" Period
Once approved, the policy is issued. In most states and provinces, you are granted a "Free Look" period—usually 10 to 30 days. During this time, you can review the policy details and, if you are unsatisfied for any reason, return it for a full refund of any premiums paid.
Common Mistakes to Avoid with Term Coverage
Navigating life insurance independently can lead to several pitfalls. Working with an agency like Bickford helps mitigate these risks, but consumers should remain aware of the following:
- Underinsuring: Many people choose a round number like $250,000 without realizing that in 2026, that amount may only cover a few years of lost income and basic funeral expenses. It is essential to account for inflation and future costs.
- Waiting Too Long: Because premiums are based on age, waiting even two or three years to "save money" usually results in a higher total cost over the life of the policy.
- Ignoring the "Term" in Term Life: Some buyers forget that the policy ends. If you don't have a conversion rider or a plan for when the term expires, you could find yourself without coverage at age 60 or 70 when your health may have declined.
- Naming Only One Beneficiary: Failing to name a "contingent" (secondary) beneficiary can lead to the death benefit going into your estate, where it may be subject to probate and creditors.
Why 2026 is a Pivotal Year for Term Insurance
In 2026, the insurance industry has fully embraced "insurtech" integrations. This means that Bickford clients benefit from faster approval times and more personalized pricing. Wearable technology data (like heart rate and activity levels from smartwatches) is increasingly being used to offer "wellness discounts" on term policies. This allows proactive individuals to lower their premiums by proving a healthy lifestyle, a feature that was once only experimental but is now standard for many top-tier carriers.
Furthermore, the legal landscape surrounding insurance has seen updates regarding beneficiary rights and digital asset management. A Bickford agent ensures that your policy is compliant with the latest 2026 regulations, particularly concerning how death benefits are paid out in a world where digital currency and international accounts are more prevalent.
Frequently Asked Questions
Can I have multiple term life insurance policies?
Yes. This is a strategy known as "laddering." For example, you might have a 30-year policy to cover your spouse and a separate 20-year policy to cover your mortgage. This allows you to have high coverage while your debts are high, and reduced (less expensive) coverage as those debts are paid off.
Does Bickford Insurance offer "No-Exam" life insurance?
Bickford works with many carriers that offer simplified issue or accelerated underwriting. For healthy individuals under a certain age (often 50 or 60), a physical medical exam may not be required. The insurer instead relies on a digital review of your health history.
What happens if I miss a premium payment?
Most term policies have a "grace period," typically 30 or 31 days. If you pay within this window, your coverage remains in force. If you exceed the grace period, the policy will lapse. Unlike permanent insurance, term insurance has no cash value to cover missed payments.
Is the death benefit from a term policy taxable?
Generally, no. In 2026, as in previous years, the death benefit of a life insurance policy is paid to beneficiaries tax-free. However, if the benefit is paid to your estate rather than a named individual, it may be subject to estate taxes depending on the total value of your assets and local laws.
Can I cancel my term policy at any time?
Yes. Term life insurance is a voluntary contract. You can stop paying premiums at any time, which will cause the coverage to end. There are no cancellation fees, but you will not receive any "refund" of premiums paid, as those premiums were used to provide coverage during the preceding months.
Practical Recommendation
For those considering term coverage through Bickford Insurance in 2026, the first step is a comprehensive needs analysis. Do not guess at your coverage amount. Calculate your total debt, including mortgages and car loans, add five to ten times your annual salary for income replacement, and include a buffer for your children's future education.
Once your "number" is established, ask your Bickford agent to run a comparison across at least three different carriers. Pay close attention to the conversion rider—ensure you have the right to switch to a permanent policy later without a medical exam. Finally, lock in your rate as soon as possible; in the world of life insurance, your health and your age are your greatest assets, and they are both at their peak today.
Image Gallery
Select an image to open it in a new tab.


Celine Dubois
Contemporary Living and Global Arts Columnist
