Finding low auto insurance rates in Florida requires a combination of maintaining a clean driving record, maximizing available discounts, and aggressively shopping the market. Because Florida is a no-fault state with high litigation rates and frequent severe weather, premiums are among the highest in the country. Drivers can lower their costs by adjusting deductibles, utilizing telematics programs, and ensuring they only pay for the specific coverages required for their vehicle's age and value.
Understanding the Florida Auto Insurance Landscape in 2026
Florida’s insurance market is unique and often volatile. As of 2026, the state remains a no-fault jurisdiction, meaning that regardless of who causes an accident, your own insurance pays for your medical treatments up to a certain limit. This system was designed to reduce the burden on the court system, but it has historically led to high premiums due to fraud and high medical costs.
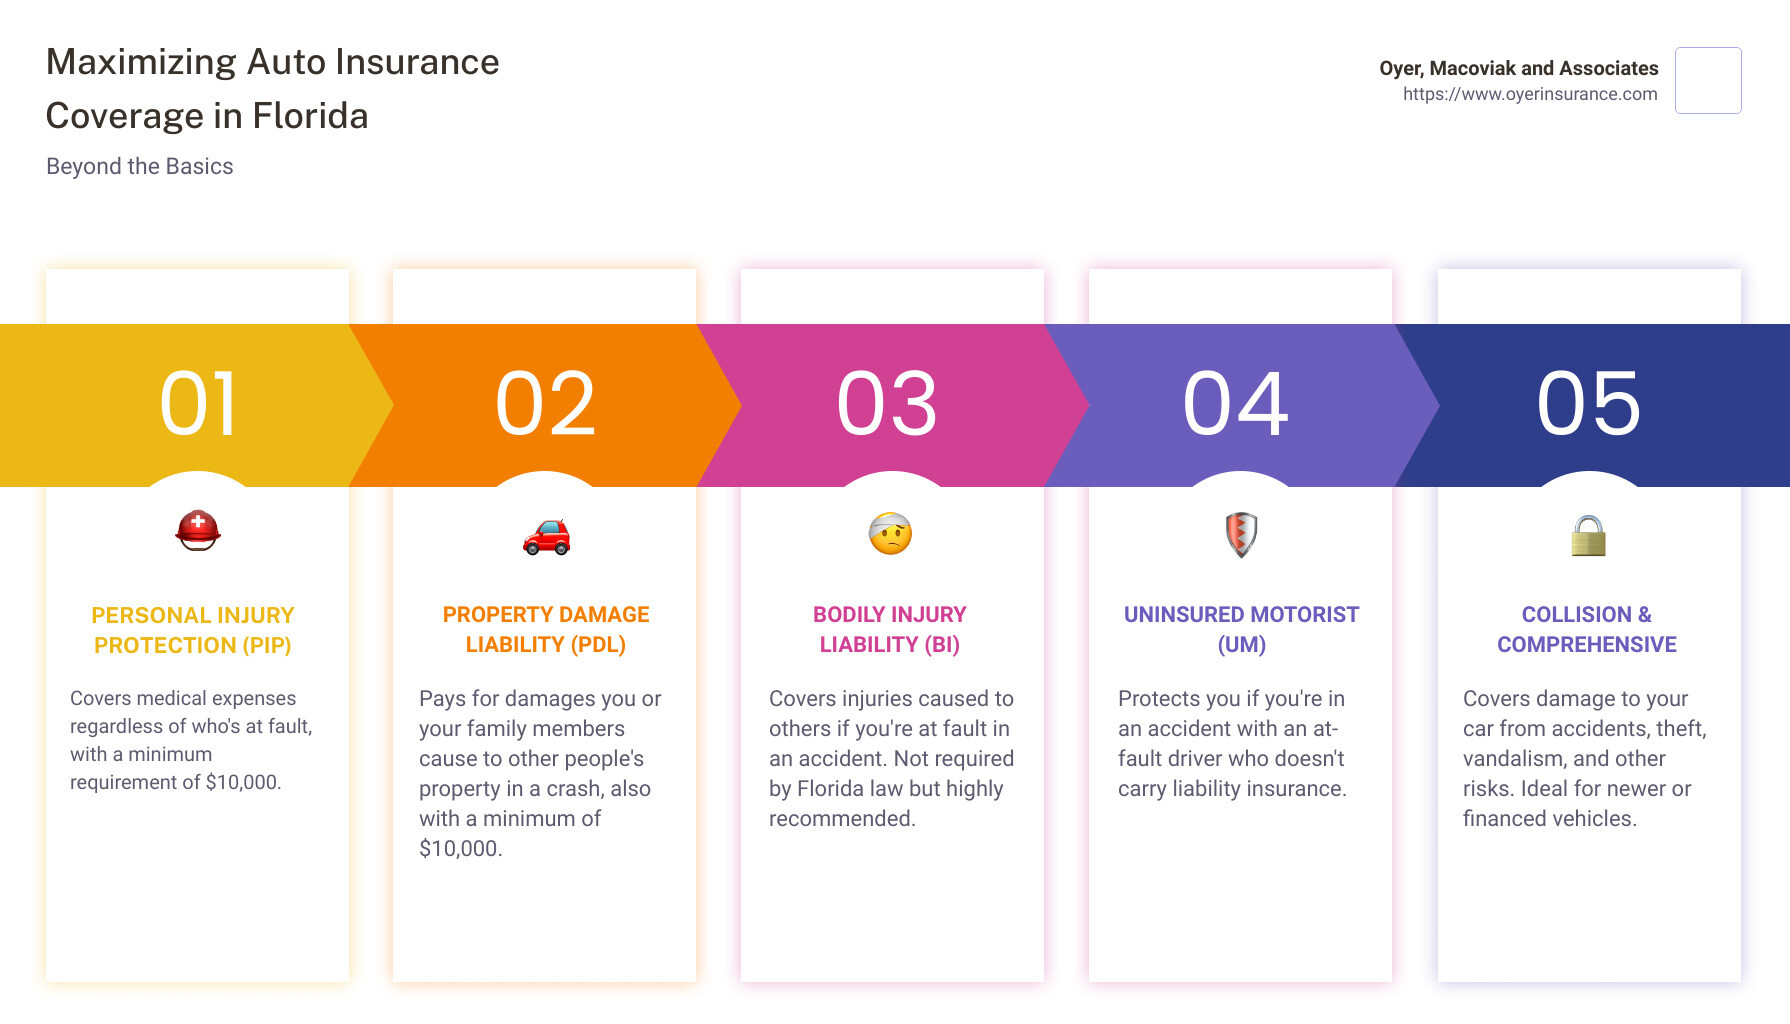
To find the lowest rates, you must first understand the state's mandatory minimums. Florida law requires every driver to carry at least:
- $10,000 in Personal Injury Protection (PIP): This covers 80% of all necessary and reasonable medical expenses, regardless of who caused the accident.
- $10,000 in Property Damage Liability (PDL): This pays for damage you cause to someone else's property (like their car or a fence) while driving.
While these are the minimums, many drivers find that these limits are insufficient for 2026 vehicle repair costs. However, if your primary goal is the lowest possible monthly premium, the "minimum-only" policy is the baseline.
Why Florida Rates Are Historically High
Several factors contribute to the high cost of insurance in the Sunshine State. Understanding these helps you navigate why certain carriers might charge more than others:
- Uninsured Motorists: Florida consistently has one of the highest percentages of uninsured drivers in the United States. Carriers pass this risk onto insured drivers through higher premiums or Uninsured Motorist (UM) coverage costs.
- Weather Events: Hurricanes and tropical storms lead to significant comprehensive claims (flood and wind damage), particularly in coastal regions.
- High Traffic Density: Urban centers like Miami, Orlando, and Tampa have high accident frequencies, which correlates directly with higher zip-code-based rates.
- No-Fault Litigation: Despite reforms, the PIP system still sees high levels of legal activity, which increases the overhead for insurance companies.
Strategic Steps to Lower Your Florida Premiums
Securing a lower rate isn't just about picking the right company; it’s about managing your "risk profile" as seen by the insurance company’s algorithms.
1. Optimize Your Credit-Based Insurance Score
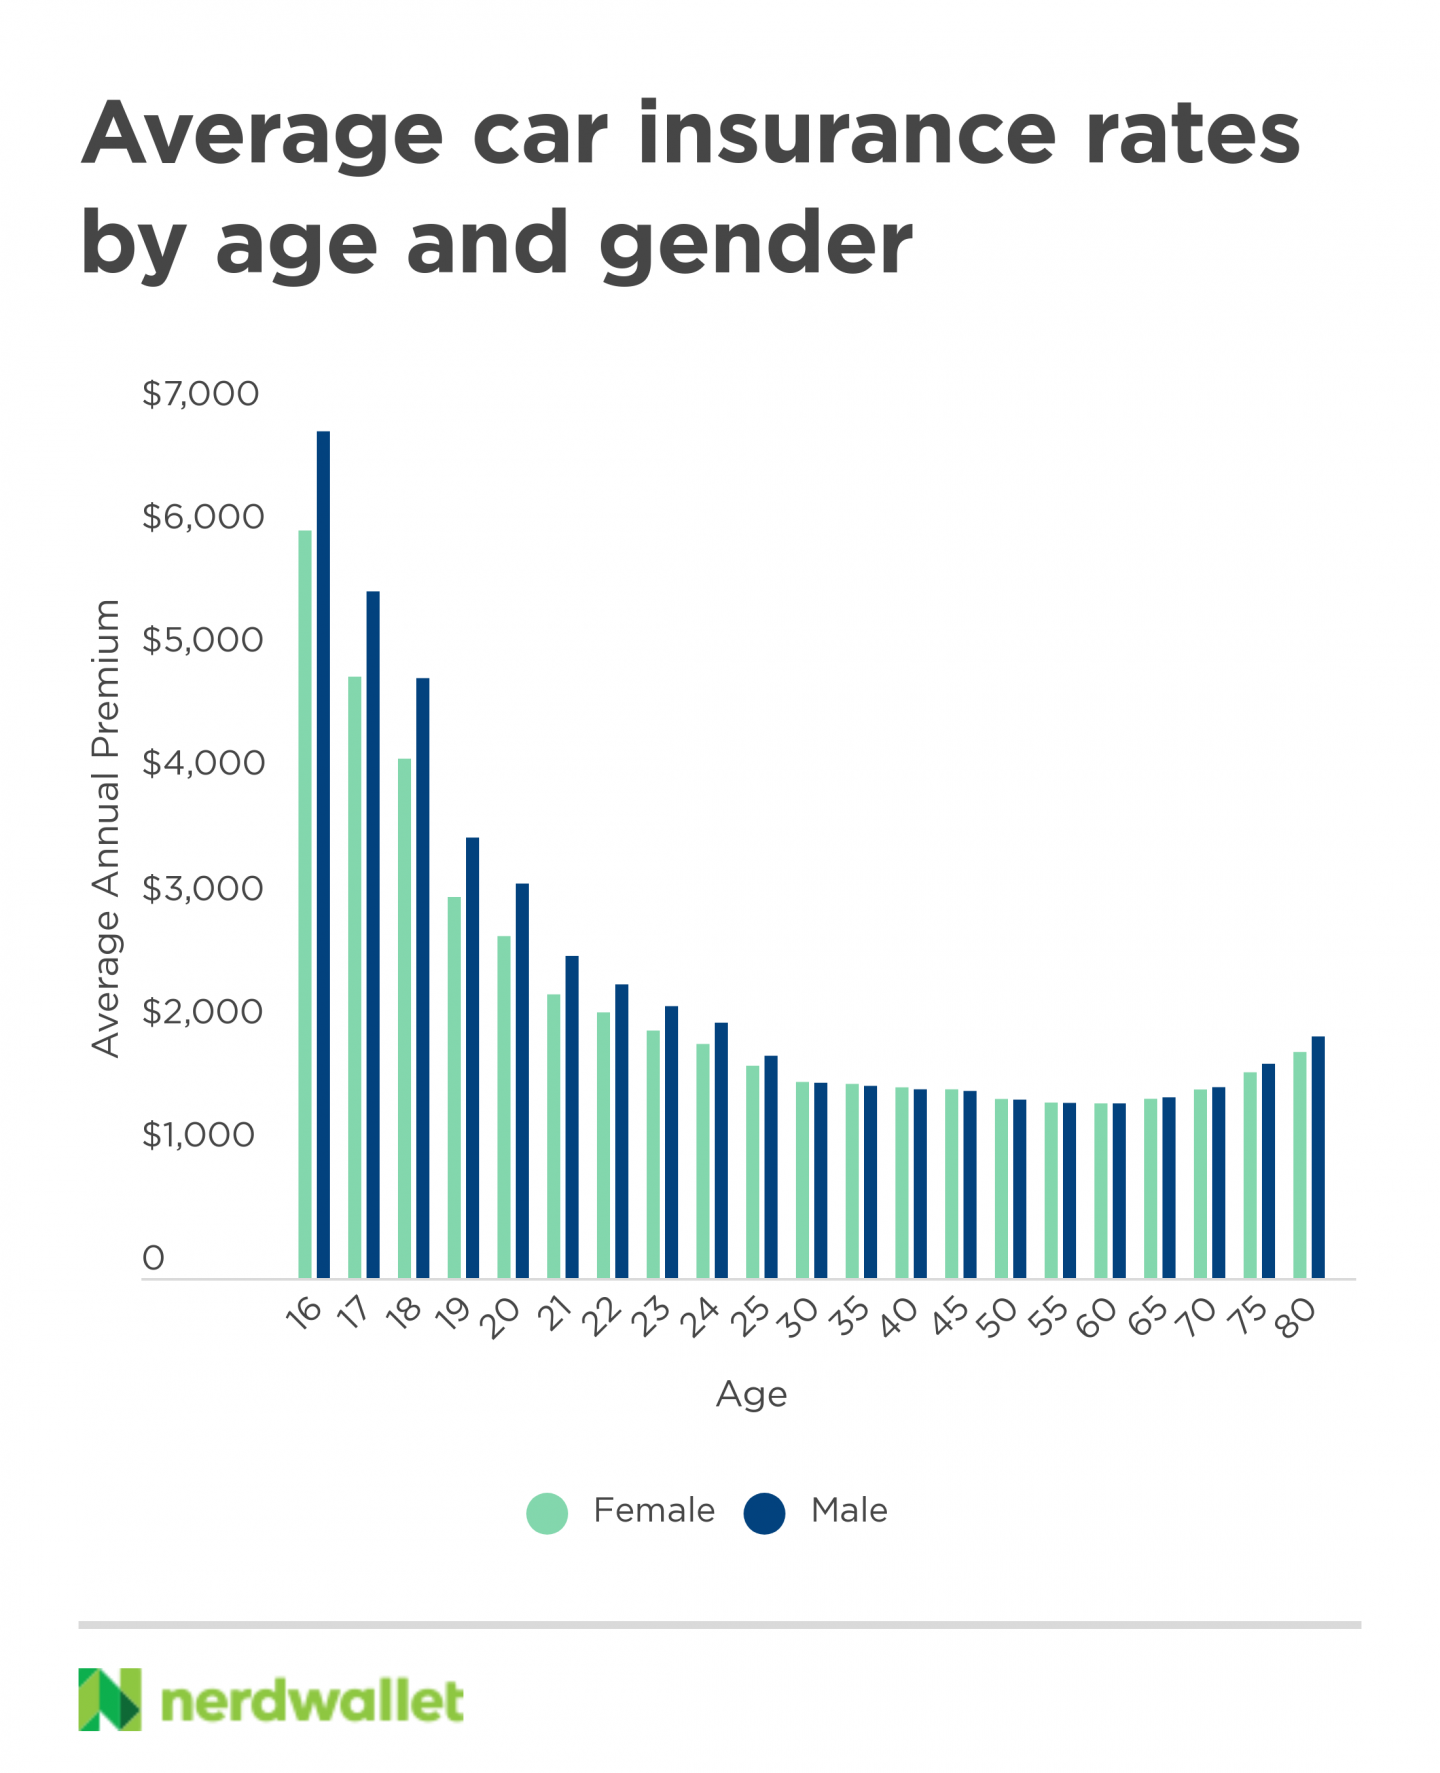
In Florida, insurers are legally allowed to use your credit history to help determine your premium. In 2026, this remains one of the most significant factors in your rate calculation. Actuaries have found a high correlation between credit health and insurance claim frequency.
- Action: Monitor your credit report for errors. Even a 50-point increase in your credit score can result in a 10–15% decrease in your annual auto insurance premium.
2. Leverage Telematics and Usage-Based Insurance (UBI)
Most major carriers in Florida, including GEICO, State Farm, and Progressive, now offer "pay-how-you-drive" programs. These programs use a smartphone app or a plug-in device to track your driving habits, such as hard braking, rapid acceleration, and late-night driving.
- The Benefit: If you are a safe, low-mileage driver, you can see discounts ranging from 10% to 40%.
- The Caveat: Some programs may actually increase your rates if the data shows you are a high-risk driver. Always read the terms of the telematics agreement before enrolling.
3. Adjust Your Deductibles
The deductible is the amount you pay out-of-pocket before your insurance kicks in for collision or comprehensive claims. Raising your deductible from $500 to $1,000 can significantly lower your monthly premium.
- When to do this: If you have an emergency fund that can easily cover the $1,000, this is a highly effective way to save money over the long term.
- When to avoid this: If a $1,000 unexpected expense would cause financial hardship, stick to a lower deductible.
4. Review Your Coverage for Older Vehicles
If you are driving a vehicle that is over 10 years old or has a low resale value, you might be over-insuring it. Collision and Comprehensive coverages are optional.
- The Rule of Thumb: If the annual cost of your collision and comprehensive coverage exceeds 10% of your car's total value, it may be time to drop those coverages and stick to the state-mandated liability and PIP.
Comparison of Coverage Levels in Florida (2026 Estimates)
The following table illustrates how different coverage levels impact the average premium and what you receive for that investment.
| Coverage Level | Key Components | Best For | Estimated Monthly Savings Potential |
|---|---|---|---|
| Minimum Liability | $10k PIP / $10k PDL | Drivers of low-value cars; those on a strict budget. | Highest Savings (Base Price) |
| Standard Coverage | $50k/$100k BI, $50k PDL, PIP, $500 Deductible | Most drivers with a vehicle loan or moderate assets. | 20-30% higher than minimum |
| Full/Comprehensive | $100k/$300k BI, UM, Comp/Coll, $250 Deductible | Drivers of new cars or those with significant personal assets. | 50-70% higher than minimum |
Note: BI (Bodily Injury Liability) is not technically required for all drivers in Florida but is highly recommended to protect against lawsuits. Under the Financial Responsibility Law, you may be required to show proof of BI after an accident or certain convictions.
Top Discounts for Florida Drivers
Florida’s Office of Insurance Regulation (OIR) oversees how companies apply discounts. Ensure you are receiving every credit for which you are eligible:
Multi-Policy (Bundling)
This remains the most effective discount. If you combine your auto insurance with a Florida homeowners, renters, or condo policy, you can often save 15% or more on both. However, given the volatility of the Florida home insurance market in 2026, sometimes the cheapest option is actually to keep them separate if your home insurer is a specialized niche carrier.
Safe Driver and Claims-Free Credits
If you haven't had a moving violation or an at-fault accident in the last three to five years, you should be receiving a "Safe Driver" discount. In Florida, even one speeding ticket can increase your rates by 20% or more for up to three years.
Student and Graduate Discounts
Florida is home to many large universities (UF, FSU, UCF, UM). Most insurers offer:
- Good Student Discount: Usually requires a 3.0 GPA or higher.
- Student Away at School: If a student on your policy attends a school more than 100 miles away and doesn't have a car, you can significantly reduce their cost while still keeping them covered when they return home for breaks.
Senior Discounts
Drivers over the age of 55 in Florida can take a state-approved accident prevention course to receive a mandatory discount on their insurance for three years. The Florida Department of Highway Safety and Motor Vehicles (FLHSMV) maintains a list of approved course providers.
How Your Location in Florida Affects Your Rate
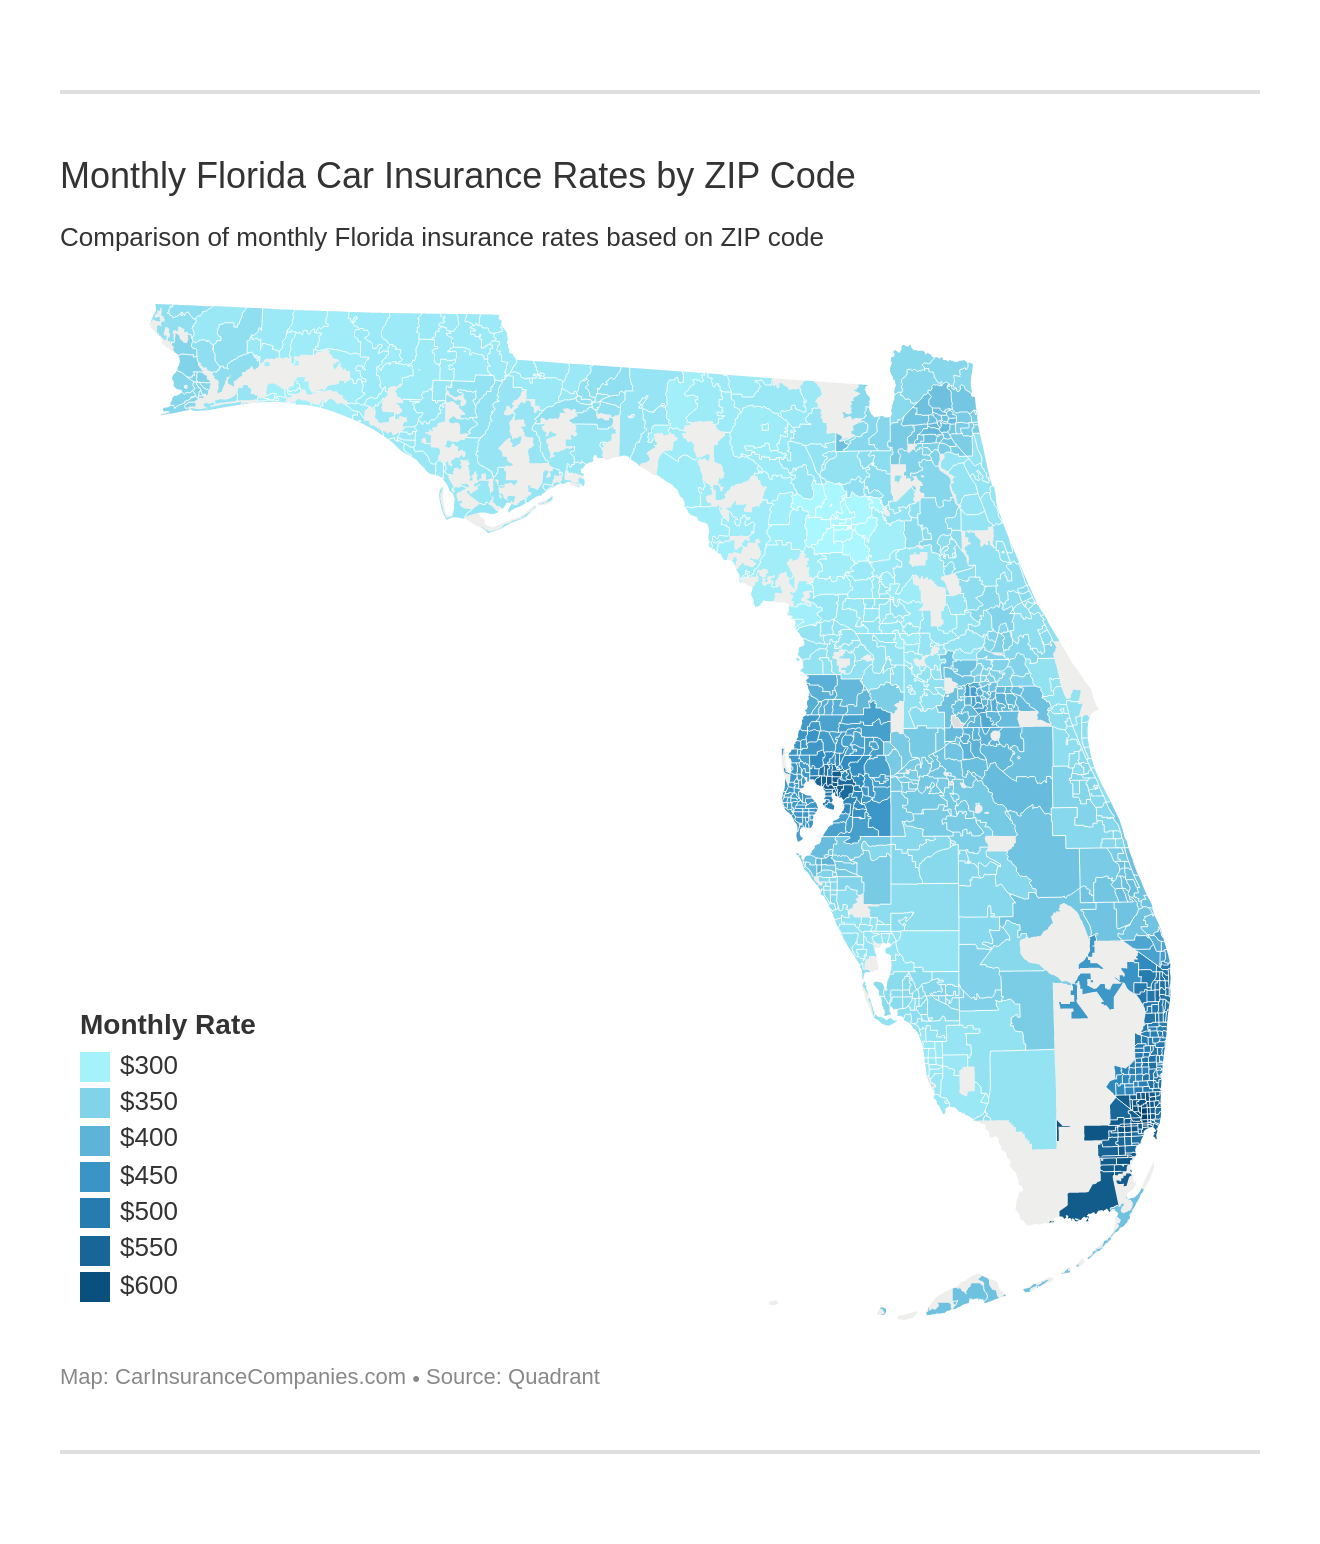
In 2026, the "zip code effect" is stronger than ever. Insurance companies use actuarial data to determine the risk of theft, vandalism, and accidents in specific neighborhoods.
- Miami-Dade and Broward Counties: These consistently rank as the most expensive areas in Florida due to high traffic density and higher rates of insurance litigation.
- Tampa Bay Area: Rates are moderately high, influenced by flood risks and frequent heavy traffic on the I-4 corridor.
- Tallahassee and Gainesville: Generally offer lower rates than the coastal or southern regions due to lower traffic volume and different weather patterns.
- The Panhandle: Rates can be lower, but residents must be wary of "Hurricane Deductibles" or higher comprehensive premiums if they live directly on the coast.
Common Mistakes When Searching for Low Rates
1. Ignoring "SR-22" or "FR-44" Requirements
If you have had a DUI or were caught driving without insurance, Florida may require an FR-44 or SR-22 filing. An FR-44 requires significantly higher liability limits ($100,000/$300,000/$50,000), which will make "low rates" much harder to find. In these cases, you must look for "non-standard" insurance carriers that specialize in high-risk drivers.
2. Underestimating the Importance of Bodily Injury (BI) Coverage
Because Florida is no-fault, many people assume they don't need BI. However, if you cause an accident that results in "permanent injury" to someone else, you can be sued. Without BI coverage, your personal assets (savings, home equity) are at risk. The "cheapest" insurance is not cheap if it leads to a $100,000 legal judgment against you.
3. Not Shopping Every 6 to 12 Months
The insurance market is not static. A company that was the cheapest for you two years ago might have had a "rate filing" increase in 2026 that makes them the most expensive now. Use an independent agent or an online comparison tool twice a year to verify you still have the best deal.
Frequently Asked Questions
Is PIP insurance mandatory even if I have good health insurance?
Yes. Florida law requires $10,000 in PIP regardless of your private health insurance status. PIP is designed to pay quickly without the delays often associated with health insurance billing, and it covers things health insurance might not, such as lost wages or funeral expenses.
Can I get a discount for a dashcam in Florida?
While most major insurers in Florida do not offer a direct "dashcam discount" in 2026, having one can indirectly lower your rates. If a dashcam proves you were not at fault in an accident, it prevents an "at-fault" surcharge on your policy, which can save you thousands over several years.
How do Florida's new insurance laws affect my 2026 rates?
Legislative reforms aimed at reducing "assignment of benefits" (AOB) abuse and bad-faith litigation have started to stabilize the market. While rates may not be "dropping" significantly, the pace of increases has slowed compared to the early 2020s, allowing for more competition among carriers.
What happens if I drive in Florida without insurance?
Florida has a very strict electronic tracking system. If your insurance is canceled and the FLHSMV does not receive notice of a new policy, your driver's license and license plate can be suspended. To reinstate them, you will have to pay a fee (ranging from $150 to $500) and provide proof of insurance.
Does the type of car I drive affect my Florida insurance rate?
Absolutely. Beyond the car's value, insurers look at the "Loss Cost" for that specific model. A vehicle with high safety ratings and low repair costs (like many mid-sized SUVs) will generally be cheaper to insure than a high-performance sports car or a vehicle that is frequently targeted by thieves.
Final Recommendation for 2026
To find the lowest auto insurance rates in Florida, you should start by obtaining a minimum of three quotes from different types of carriers: one national brand (like GEICO or Progressive), one "direct" insurer (like USAA if you are military-affiliated), and one through an independent agent who can access regional Florida carriers. If you are a safe driver, prioritize companies with robust telematics programs, as these offer the most significant discounts in the 2026 market. Always verify that any company you choose is licensed and in good standing via the Florida Office of Insurance Regulation.
Image Gallery
Select an image to open it in a new tab.



Simon Caldwell
Enterprise Technology and Systems Editor
