Securing a Home Equity Line of Credit (HELOC) often depends on a lender’s specific risk appetite rather than a single industry-wide standard. To find the easiest HELOC to get, you must prioritize lenders with flexible debt-to-income (DTI) ratio requirements, lower credit score minimums, and automated underwriting processes, while maintaining sufficient equity in your property.
Understanding the HELOC Mechanism
A Home Equity Line of Credit functions as a revolving credit line secured by your residential property. Unlike a traditional mortgage or a home equity loan, which provides a lump sum, a HELOC allows you to borrow, repay, and borrow again up to a specified limit during a "draw period," typically lasting 10 years. Because the debt is secured by your home, lenders generally view these loans as less risky than unsecured personal loans; however, the lender still imposes strict criteria to ensure the borrower can manage the repayment obligation.
When searching for the "easiest" loan, you are essentially looking for lenders that utilize more lenient underwriting guidelines. While "easy" might imply a lack of paperwork, in the mortgage world, it actually refers to a higher tolerance for common financial variables, such as slightly lower credit scores or higher utilization of existing debt.
Core Eligibility Criteria: The Reality of Lending
Regardless of how "easy" a lender is, federal regulations and standard banking safety practices require a baseline of documentation. You cannot bypass the fundamental need for proof of income, property valuation, and a clear title.
Credit Score Benchmarks
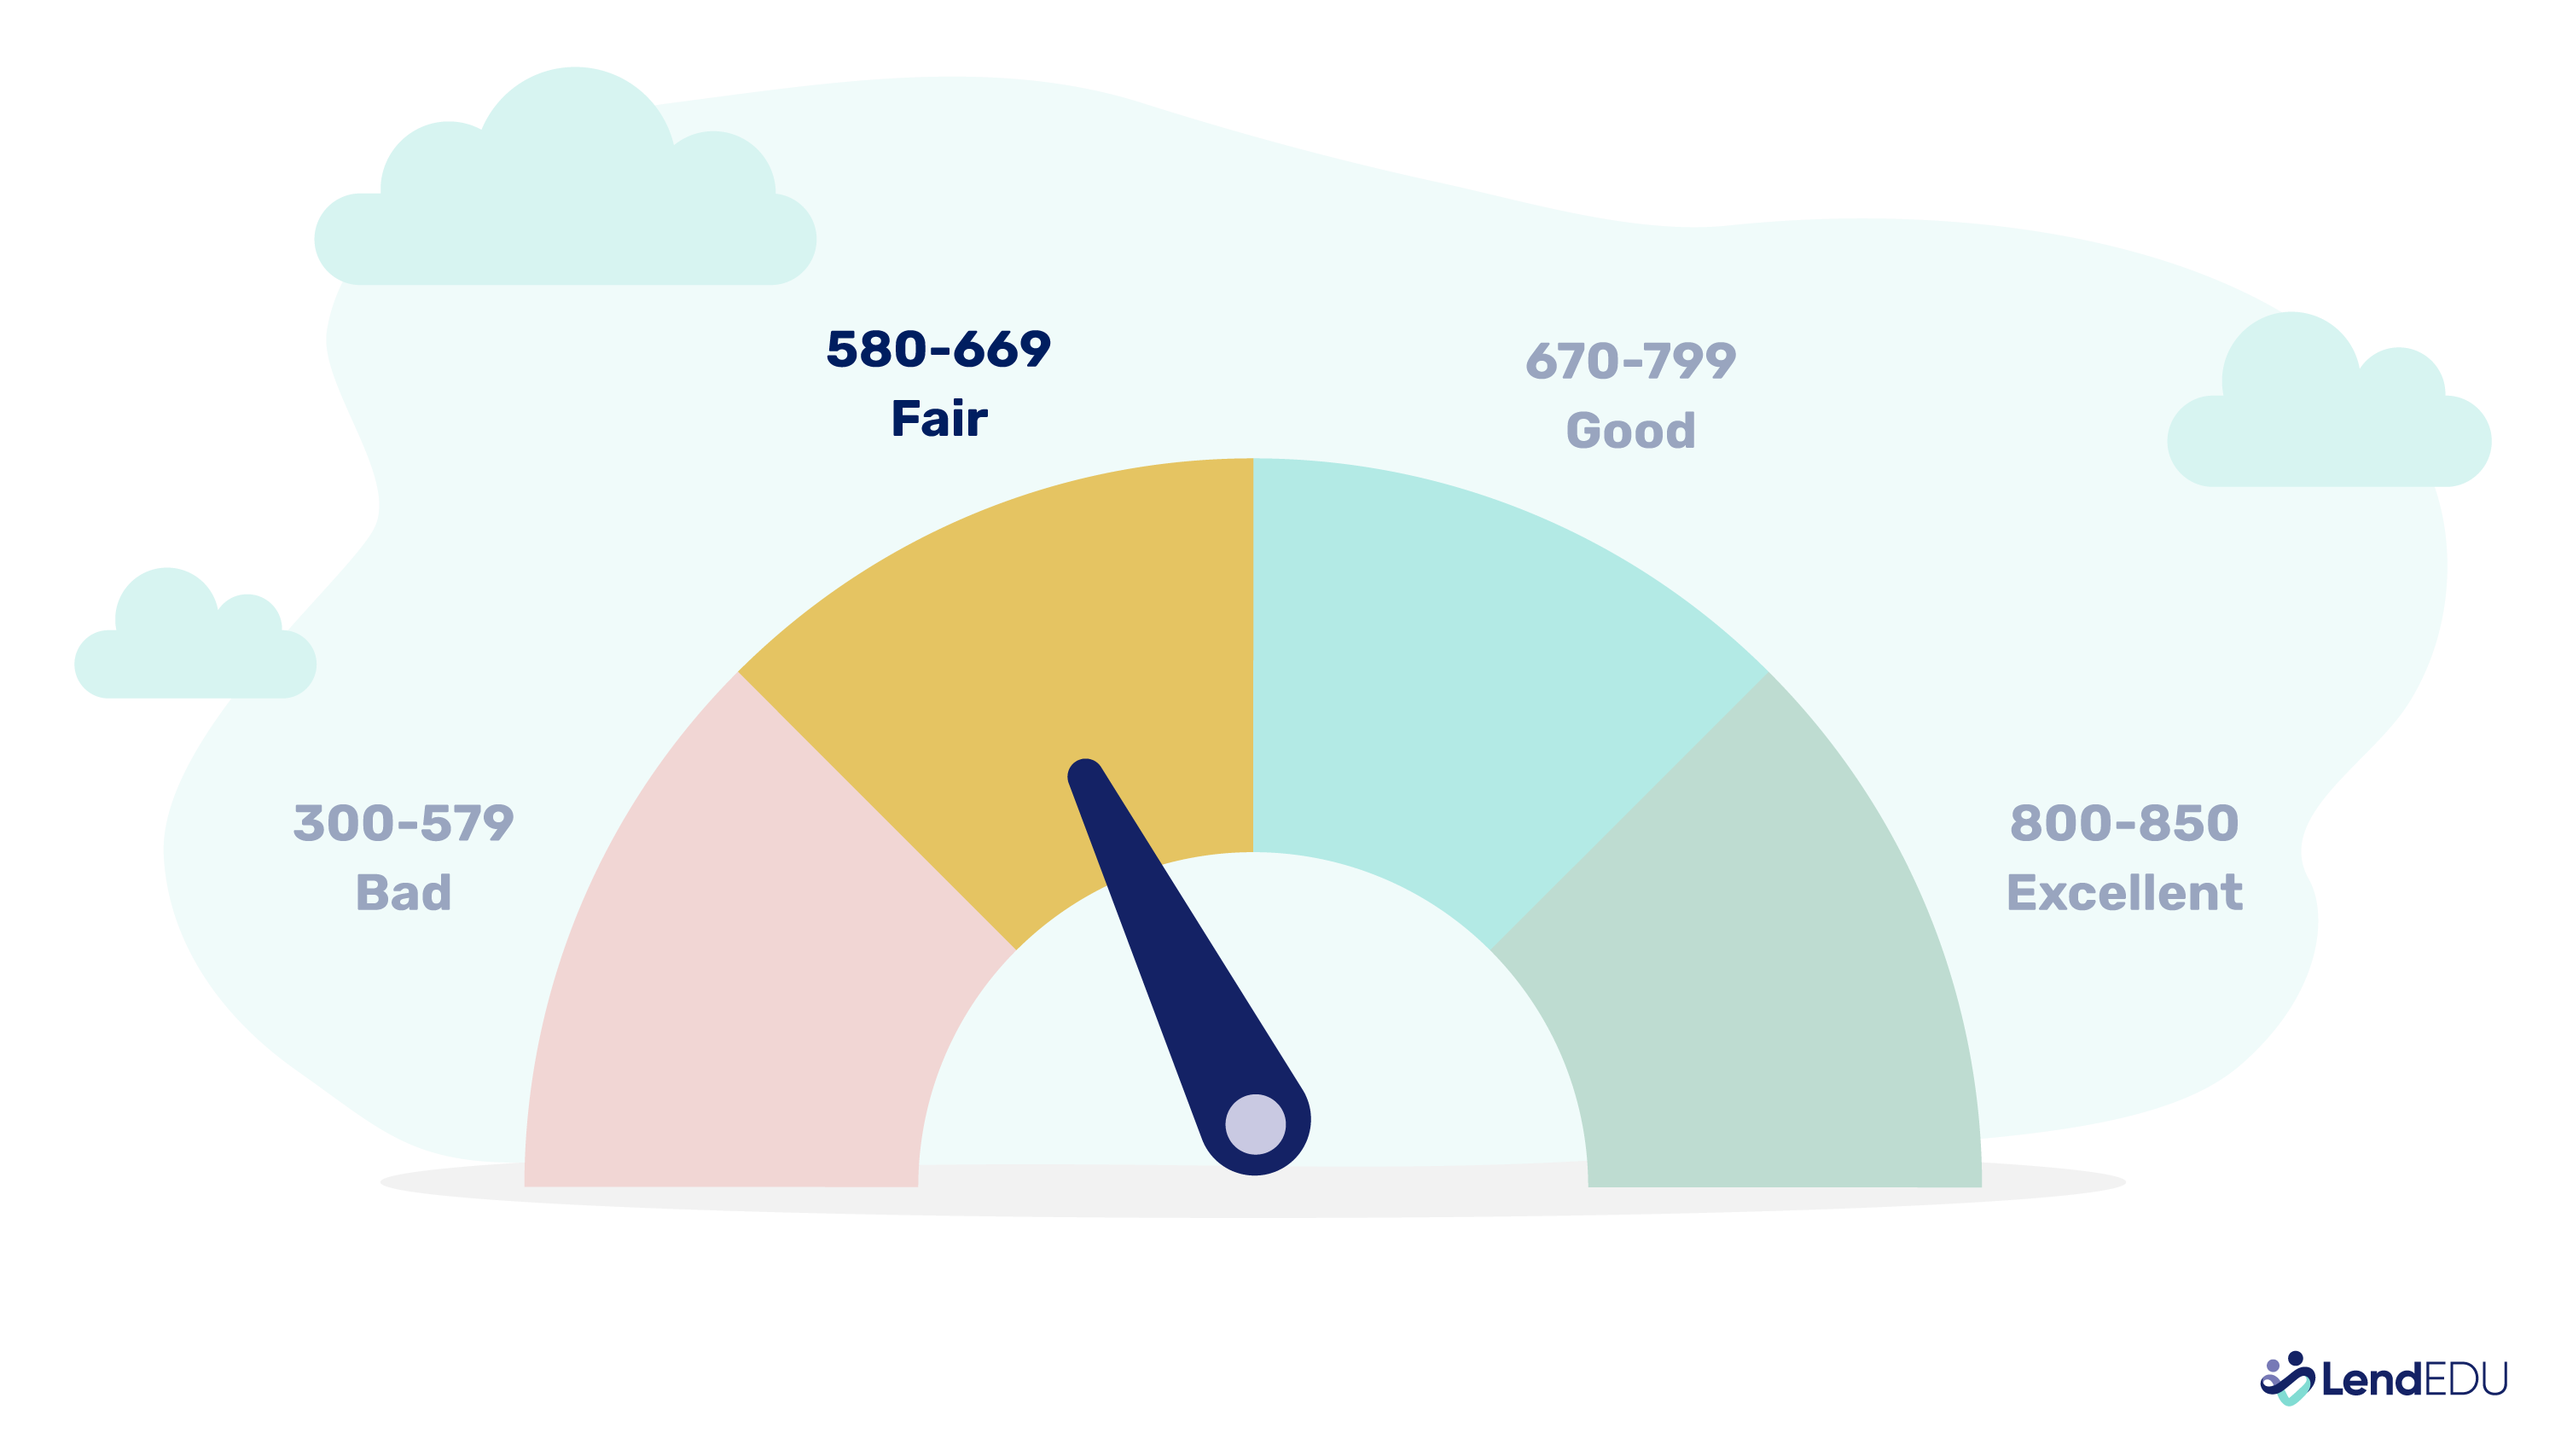
Most traditional banks require a credit score of 680 or higher to offer competitive rates. When seeking the easiest path to approval, look toward credit unions and smaller regional banks. These institutions often conduct "manual underwriting," meaning they may look at your overall financial picture—such as a history of consistent employment or a low balance on existing credit cards—to offset a credit score that falls in the 620–660 range.
Loan-to-Value (LTV) Ratios
The most significant factor in approval speed and ease is your LTV ratio. LTV is calculated by dividing your total mortgage debt by the appraised value of your home. If you owe $200,000 on a home worth $400,000, your LTV is 50%. A lower LTV is the single most effective way to simplify the approval process. If you have significant equity, lenders are far less concerned with your credit history because their risk of loss in a foreclosure scenario is significantly diminished.
Debt-to-Income (DTI) Ratios
Lenders analyze your DTI to ensure you can afford the monthly payments once the HELOC enters its repayment phase. A standard requirement is a DTI of 43% or lower. Lenders who market themselves as "easy" to work with are typically those willing to push this limit toward 50%, provided you have substantial cash reserves or a high residual income after monthly expenses are met.
Comparing Lender Types for Accessibility
When evaluating where to apply, it is helpful to categorize lenders based on their operational structure.
| Lender Category | Typical Approval Velocity | Flexibility | Best For |
|---|---|---|---|
| National Banks | Moderate to Slow | Low | Customers with existing high-balance accounts |
| Credit Unions | Fast to Moderate | High | Members with local, long-term relationships |
| Fintech/Online Lenders | Very Fast | Moderate | Applicants with clean credit and digital-ready files |
| Regional Banks | Moderate | High | Borrowers with unique property or income profiles |
The Role of Automated Underwriting
In 2026, the shift toward digitized mortgage processing has made the application experience feel "easier" even if the underlying criteria remain strict. Online lenders often use automated underwriting systems (AUS). These systems instantly verify your assets, employment status, and property value using digital databases. If your financial profile is straightforward—meaning you are a W-2 employee with a clear credit history—these lenders provide the most frictionless experience.
However, if you are self-employed or have non-traditional income sources, an online-only, highly automated lender might be more difficult to navigate than a local community bank where a human loan officer can manually review your tax returns and explain the nuances of your income.
Steps to Streamline Your Application
To make your HELOC application as smooth as possible, take a proactive approach to organizing your documentation before you initiate the request.
- Conduct an Informal Appraisal: Before applying, research recent sales of similar homes in your neighborhood. If your estimated equity is too low (usually below 15–20% of the home's value), you will face immediate rejection regardless of your credit score.
- Review Your Credit Report: Use a free, government-authorized site to check for inaccuracies. A single reporting error can cause an automatic decline from an automated underwriting system.
- Organize Tax Documentation: Gather at least two years of W-2 forms or 1099s. If you are self-employed, ensure your Schedule C documentation clearly demonstrates net profit, as lenders focus on "qualifying income" rather than gross revenue.
- Identify Existing Liens: A HELOC must generally be in a subordinate lien position. If you have secondary mortgages or large tax liens, these must be addressed or paid off, as they can disqualify you from the primary HELOC process.
Common Pitfalls and How to Avoid Them
The most common mistake applicants make is applying with multiple lenders simultaneously, which generates multiple "hard" inquiries on your credit report. While one or two inquiries have a negligible impact, a barrage of applications within a short window can trigger fraud alerts or suggest financial distress, making lenders more hesitant.
Another pitfall is assuming that your home’s tax-assessed value reflects its market value. Municipal tax assessments are often significantly lower than the fair market value. If you base your equity calculation on tax records, you may believe you qualify for a larger line than the bank is willing to approve. Always use a current Comparative Market Analysis (CMA) or a recent professional appraisal to gauge your actual equity.
Professional Financial Guidance
A HELOC is a variable-rate debt instrument. By 2026, many borrowers are re-evaluating the risk of variable interest rates. Before finalizing any HELOC, consult with a financial advisor or tax professional to understand the impact of the interest payments on your monthly cash flow. In some cases, a fixed-rate home equity loan may be a safer, albeit less flexible, alternative.
Ensure you read the "What You Should Know About HELOCs" disclosure document that federal law requires lenders to provide. It contains vital information about the draw period, potential balloons, and the specific terms of the variable rate index used by that lender.
Frequently Asked Questions
Does a higher credit score make a HELOC easier to get? Yes. While some lenders have lower minimum requirements, a credit score above 740 effectively bypasses many of the manual checks in the underwriting process, leading to faster approvals and lower interest rate tiers.
Can I get a HELOC with no equity? No. A HELOC is a secured product. Lenders require you to retain a minimum amount of equity (usually at least 15% to 20%) to ensure they can recover their investment should the property value decline during the life of the loan.
Is it easier to get a HELOC from my current mortgage lender? Often, yes. Your current mortgage lender already has verified copies of your property deed, title insurance, and perhaps even your income history, which can reduce the amount of redundant documentation required during the application process.
What is the most common reason for a HELOC denial? Insufficient equity is the most frequent cause for denial. If the combined total of your primary mortgage and the requested HELOC exceeds the lender's LTV limit (usually 80% to 85%), the application will be denied regardless of your credit score or income.
Do I need a formal appraisal for a HELOC? In many cases, yes. While some lenders use automated valuation models (AVMs) for homes with high equity and clear records, a formal appraisal provides the verified data necessary to justify the lender’s risk, especially if your LTV is nearing their maximum threshold.
Next Action Recommendation
To secure the easiest path to a HELOC, start by requesting a current statement from your existing mortgage lender to confirm your exact remaining principal balance. Then, contact your primary bank or credit union to ask for their specific "underwriting overlays"—the internal rules they use beyond standard guidelines. If they offer an in-house, human-reviewed process, submit your documents there first, as the human element often allows for flexibility that automated, national online platforms cannot provide.
Image Gallery
Select an image to open it in a new tab.
Akira Tanaka
International Academic Trends Correspondent
