Demystifying the Contract to Pay Back Money in Simple Terms
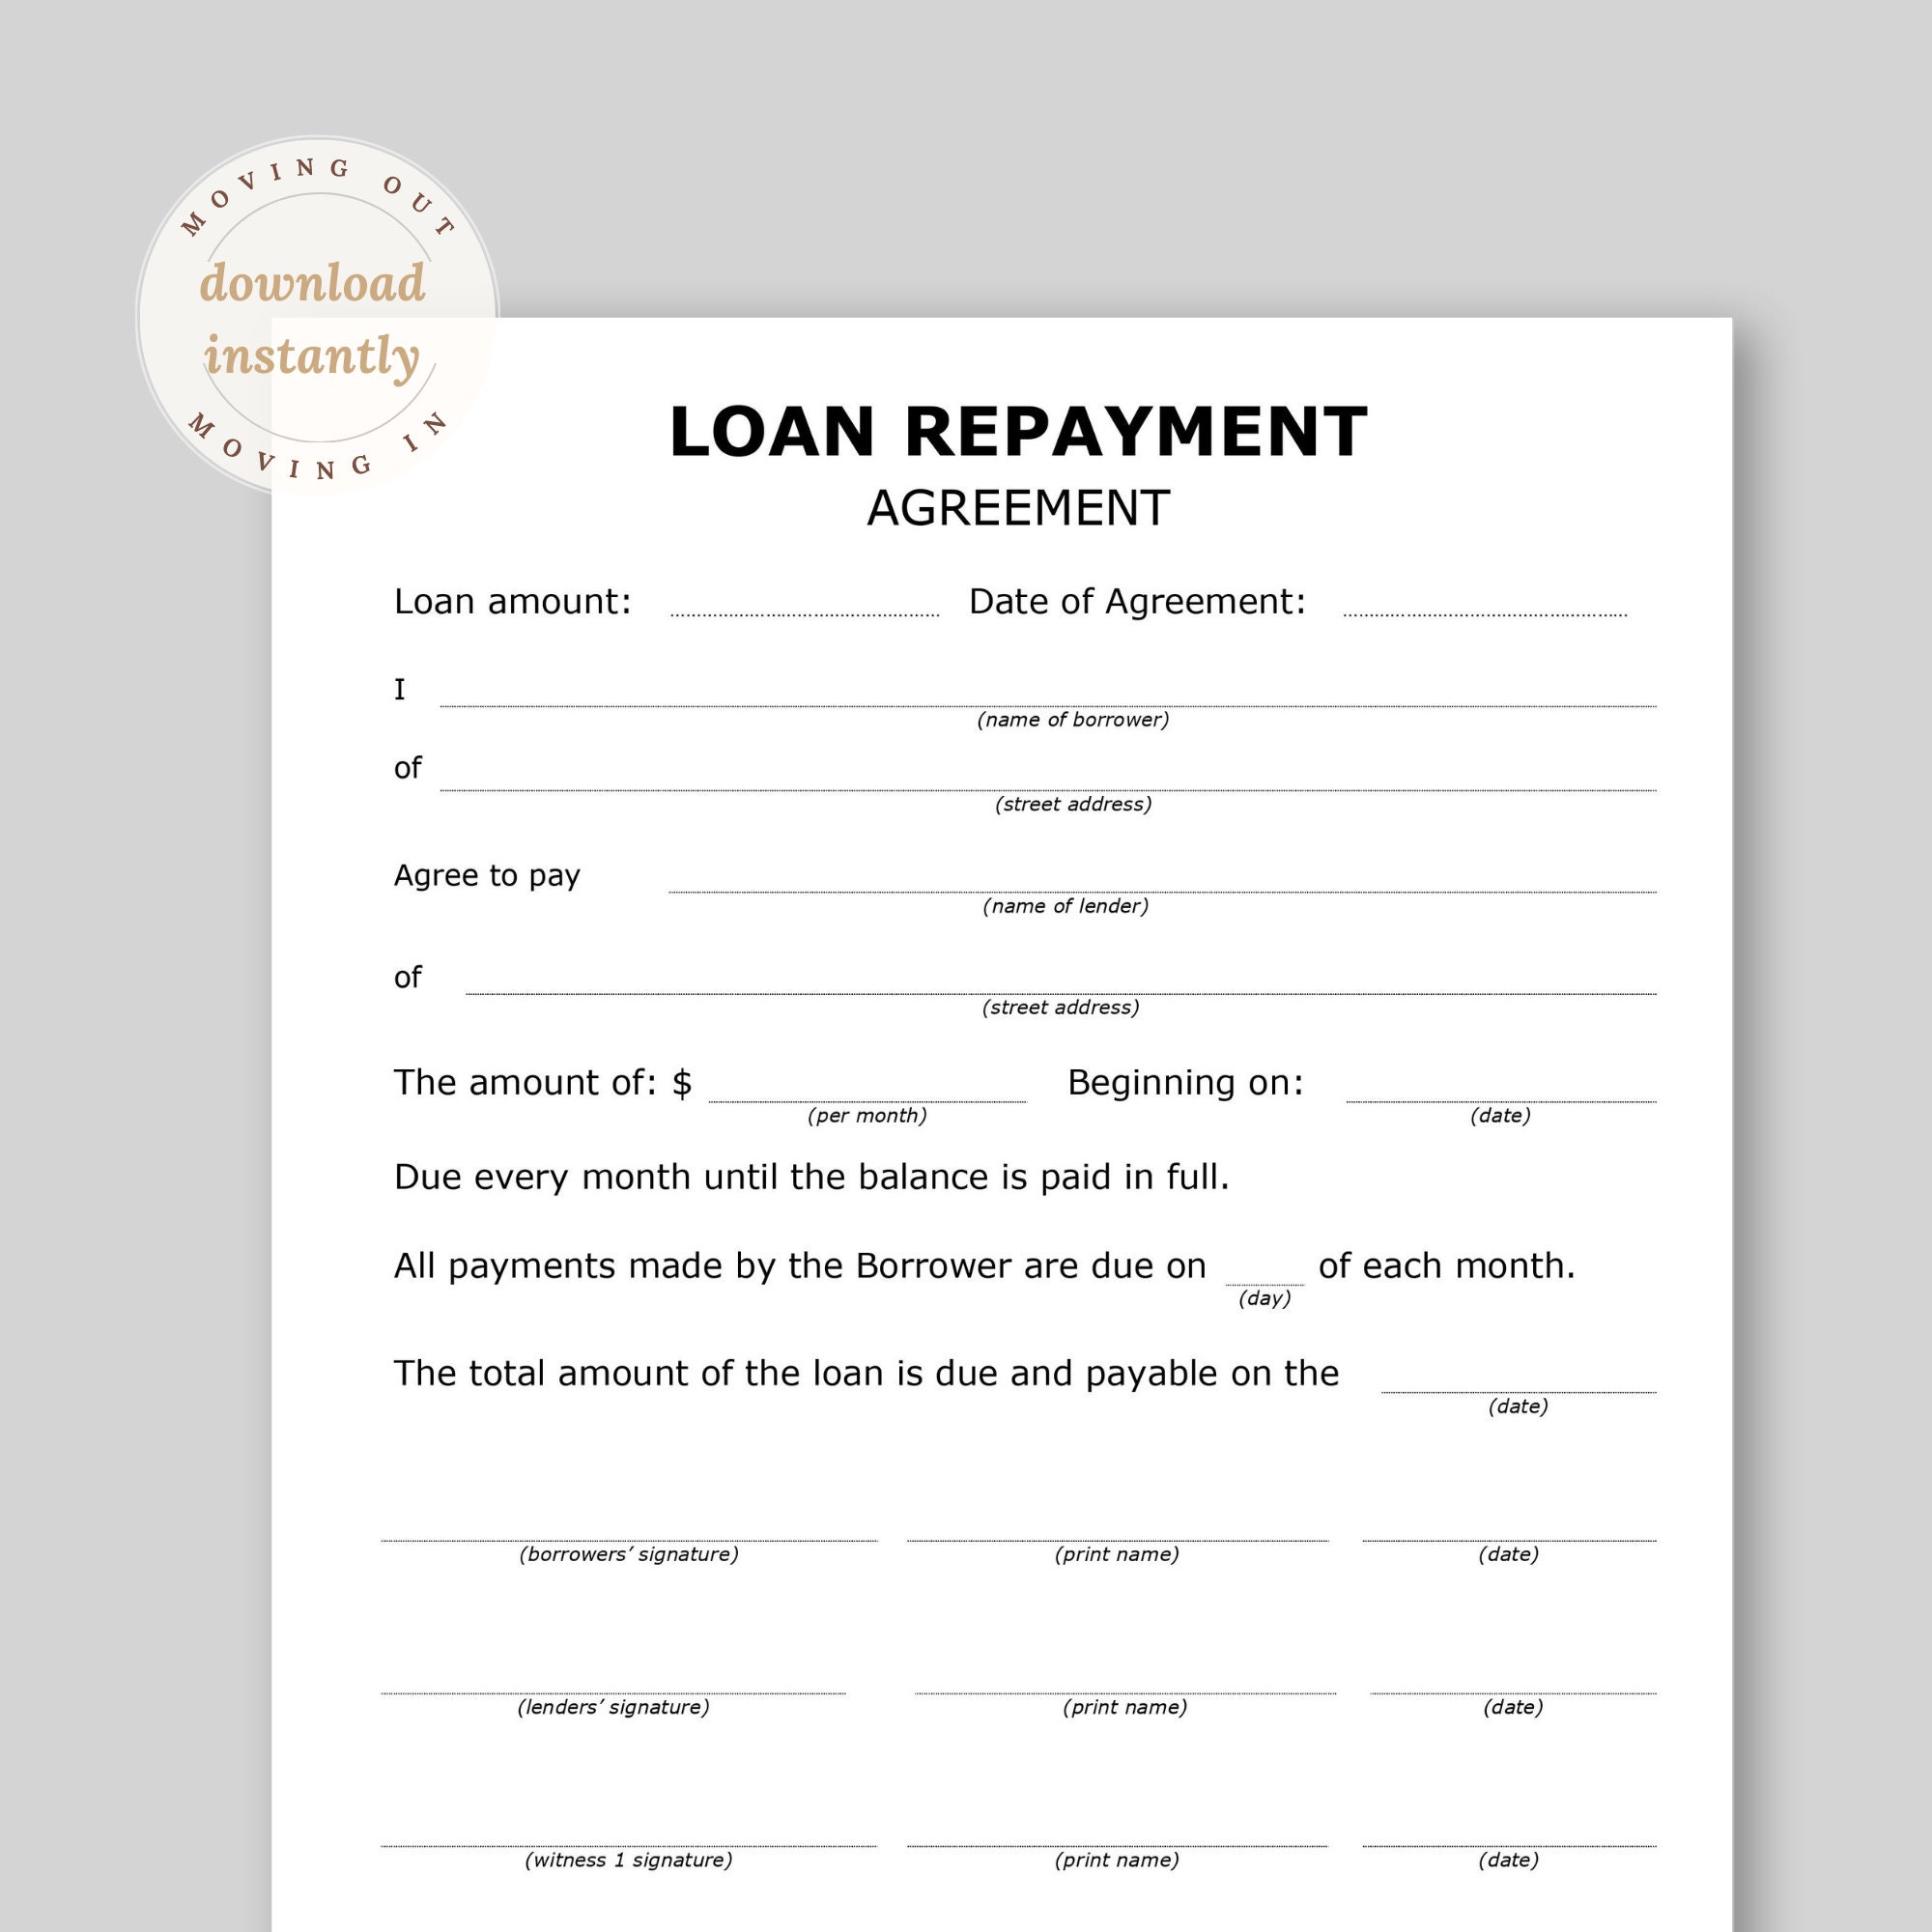
A contract to pay back money is a legally binding agreement that clearly outlines how a borrower will repay a loan to a lender, detailing the exact repayment amount, schedule, interest rates, and consequences of default to protect both parties and prevent future misunderstandings.
When individuals or businesses enter into a financial arrangement where one party lends funds to another, establishing a clear framework is essential for maintaining trust and legal security. Whether you are lending money to a family member, borrowing from a private investor, or formalizing an informal arrangement, understanding how a repayment agreement works protects everyone involved. Legal documents can often feel intimidating, filled with dense jargon and complex clauses. However, the core purpose of a repayment contract is remarkably straightforward: to document a debt and outline the exact steps for its resolution.
Navigating the mechanics of these agreements requires looking beyond intimidating legal terminology and focusing on the core components that make a document enforceable, fair, and clear. This guide breaks down everything you need to know about setting up, structuring, and executing a contract to pay back money, ensuring that both lenders and borrowers remain protected throughout the life of the loan.
Understanding the Purpose of a Repayment Agreement
At its heart, a contract to pay back money—often referred to as a promissory note, loan agreement, or repayment contract—serves as written evidence of a debt. Human memory is fallible, and informal verbal agreements frequently lead to misunderstandings regarding when, how, and even whether money is supposed to be returned.
When a dispute arises, a verbal agreement offers little to no protection in a court of law. A written contract establishes an objective record of the transaction. It confirms that the borrower acknowledges receipt of the funds and explicitly promises to return them under agreed-upon terms. This clarity reduces friction in personal relationships and provides legal recourse for commercial lenders if payments stop.
Furthermore, a well-drafted repayment agreement establishes boundaries. It prevents lenders from demanding immediate full repayment when the borrower is experiencing a temporary cash crunch, and it protects lenders from borrowers who might otherwise delay payment indefinitely. By setting clear expectations from day one, both parties can manage their financial planning with confidence.
Core Elements Every Simple Repayment Contract Must Include
To be effective and legally enforceable, a contract does not need to span fifty pages of dense legalese. In fact, simpler agreements are often more effective because they are easier for both parties to understand. However, omitting certain foundational elements can render the document useless. Every solid repayment contract must incorporate specific structural components.
Identification of the Parties
The agreement must clearly name the individuals or legal entities involved. This includes the full legal names and physical addresses of both the lender (the creditor) and the borrower (the debtor). If a business is involved, the official registered name and corporate structure should be used.
Principal Amount and Disbursement
The document must explicitly state the exact amount of money being lent, known as the principal. Additionally, it should detail how and when the funds will be transferred to the borrower—whether via wire transfer, check, or cash—and confirm that the borrower has received or is actively receiving the funds.
Repayment Terms and Schedule
This is the operational core of the contract. It must answer the fundamental questions of how the debt will be serviced. Key details include:
- Installment frequency: Whether payments are due weekly, monthly, quarterly, or as a single lump sum.
- Payment amounts: The precise dollar amount due during each payment cycle.
- Start and end dates: When the first payment is due and when the final payment will clear the balance.
- Acceptable payment methods: Whether checks, electronic bank transfers, or digital payment platforms are permitted.
Interest Rates and Fees
If the lender is charging interest for the use of the money, the annual percentage rate (APR) must be clearly stated. The contract should also specify whether the interest is simple or compound, how it accrues, and whether there are any penalties for late payments or incentives for early repayment.

Structuring the Agreement: A Comparative Overview
Different financial scenarios require different structural approaches. Choosing the right format ensures that the document matches the complexity of the loan.
| Agreement Type | Best Suited For | Key Characteristics | Complexity Level |
|---|---|---|---|
| Simple Promissory Note | Personal loans between friends or family | Short, concise, focuses on principal and basic repayment date. | Low |
| Installment Loan Agreement | Structured commercial or private loans | Detailed amortization schedule, monthly payments, interest calculations. | Moderate |
| Demand Note | Flexible loans with undefined end dates | Lender can demand full repayment at any time with adequate notice. | Low-Moderate |
| Secured Loan Agreement | Higher-value loans requiring collateral | Links specific assets (vehicles, property) to the debt as security. | High |
Incorporating Safeguards: Interest, Collateral, and Default
A comprehensive repayment contract does more than just schedule payments; it also accounts for what happens when things do not go according to plan. Anticipating potential financial friction points protects both parties from unexpected losses.
Interest and the Time Value of Money
Lending money carries an opportunity cost. Even in informal arrangements between relatives, charging a nominal interest rate can protect the lender against inflation. When drafting this section, it is vital to check state or local usury laws. These laws set statutory caps on the maximum interest rate a lender can legally charge, protecting borrowers from predatory lending practices.
Secured Versus Unsecured Loans
A contract can be either unsecured or secured. An unsecured loan relies solely on the borrower’s promise to pay. If the borrower defaults, the lender must sue in court to garnish wages or seize general assets. A secured loan, by contrast, ties the debt to a specific piece of collateral—such as a car, equipment, or real estate. If the borrower fails to pay, the lender has the legal right to take possession of the collateral to satisfy the debt.
Handling Defaults and Late Payments
Hope is not a strategy when it comes to debt collection. The contract should explicitly define what constitutes a default—such as missing three consecutive payments or filing for bankruptcy. Furthermore, it should outline grace periods, late fees, and acceleration clauses. An acceleration clause allows the lender to demand the entire remaining balance immediately if the borrower breaches the terms of the agreement.
Step-by-Step Guide to Drafting and Executing the Contract
Creating a legally sound repayment contract does not require a law degree, but it does demand attention to detail. Following a structured workflow ensures that no critical element is overlooked.
- Discuss and Agree on Terms: Before writing anything down, sit down with the other party to discuss the loan amount, repayment timeline, interest, and what happens if financial difficulties arise. Alignment upfront prevents disputes later.
- Draft the Document: Use a clear, template-based approach or draft a customized document that includes all essential sections: parties, principal, interest, schedule, and default terms. Keep the language plain and unambiguous.
- Review for Legal Compliance: Check local state or national lending regulations regarding interest caps and disclosure requirements. For significant sums, having a qualified attorney review the document is highly recommended.
- Sign and Execute: Both parties should sign and date the document. To add an extra layer of authenticity and prevent future claims of forgery or coercion, have the signatures notarized by a licensed notary public.
- Maintain Copies: Both the lender and the borrower must retain a signed, original copy of the contract in a secure location for their financial and legal records.
Common Pitfalls to Avoid
Even with good intentions, amateur contract drafters frequently fall into traps that compromise the validity or effectiveness of their agreements. Avoiding these common mistakes saves both parties considerable stress.
- Vague Repayment Terms: Writing phrases like "the borrower will pay back the money when able" creates an unenforceable contract. Repayment triggers must be objective and time-bound.
- Ignoring Local Laws: Failing to verify local interest rate caps can result in an illegal contract that exposes the lender to regulatory penalties or voids the interest clause entirely.
- Failing to Document Payments: When cash changes hands without a paper trail, disputes frequently arise over how much has already been paid. Every payment should be acknowledged with a written receipt or processed through a traceable electronic channel.
- Neglecting Co-signers or Witnesses: For larger amounts, relying solely on a handshake and two signatures without witnesses or notarization weakens the evidentiary weight of the document if challenged in court.
Frequently Asked Questions
Do I need a lawyer to write a contract to pay back money?
For small amounts between trusted friends, a well-drafted template or simple written agreement is often sufficient. However, for large sums, complex collateral arrangements, or business loans, consulting a qualified attorney ensures compliance with local laws and protects both parties' interests.
What happens if the borrower stops making payments?
If the borrower defaults, the lender can refer to the default clauses in the contract. Depending on the terms, the lender may issue a demand letter, assess late fees, trigger an acceleration clause, or pursue legal action through small claims court or civil court to recover the funds.
Can a repayment contract be modified after it is signed?
Yes, but any changes must be made in writing and signed by both the lender and the borrower. Verbal modifications are generally difficult to enforce legally, so amending the original contract with a signed addendum is always the safest approach.
Is a handshake agreement legally binding?
While verbal agreements can technically be contracts under contract law, proving their terms in court is notoriously difficult. A written contract provides clear, indisputable evidence of the agreement, making it vastly superior for resolving disputes.
Should a repayment contract be notarized?
While notarization is not legally required in every jurisdiction to make a contract valid, it is strongly recommended. Notarization verifies the identities of the signatories and prevents one party from later claiming that their signature was forged or obtained under duress.
Next Actions and Best Practices
If you are preparing to lend or borrow money, start by having an open, honest conversation about expectations and financial realities. Draft a clear agreement that outlines every detail of the transaction, from the principal amount to the final payment date. Always execute the document in writing, secure signatures with a notary public if the amount is substantial, and keep meticulous records of every payment made. By approaching the process with transparency and legal diligence, you establish a solid foundation for financial security and mutual trust.
Image Gallery
Select an image to open it in a new tab.
Simon Caldwell
Enterprise Technology and Systems Editor
