Understanding Cindy Monroe Net Worth in Context: Professional Achievement and Market Reality

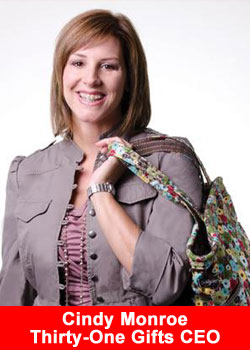
Cindy Monroe, best known as the founder of the direct-sales company Thirty-One Gifts, has built a significant financial profile rooted in entrepreneurship, retail strategy, and organizational growth. While public estimates of her net worth vary widely due to the private nature of her assets and the fluctuating valuation of her former business interests, her financial status is best understood by analyzing the trajectory of her company, its corporate evolution, and her sustained impact on the direct-sales industry.
The Foundation of Financial Success: Thirty-One Gifts
To contextualize Cindy Monroe's wealth, one must examine the entity that serves as the primary engine of her career: Thirty-One Gifts. Founded in 2003 in the basement of her home in Dayton, Ohio, the company specialized in personalized bags, totes, and organizational products. Unlike retail ventures that rely on brick-and-mortar storefronts, Monroe utilized a direct-selling business model, empowering independent consultants to market products through home parties and, eventually, robust digital platforms.
The company's rapid ascent between 2003 and 2012 marked a period of immense growth. At its peak, Thirty-One Gifts was recognized as one of the fastest-growing woman-owned companies in the United States. This era of hyper-growth required significant capital investment, strategic supply chain management, and the scaling of an independent contractor workforce that numbered in the hundreds of thousands. Monroe’s net worth is inextricably linked to the valuation of this enterprise during its most profitable years.
Understanding Direct-Sales Business Valuations
In the context of financial analysis, calculating the net worth of a founder of a private direct-sales organization is inherently speculative. Private companies do not issue public stock, meaning their market capitalization—a key metric in determining a founder’s wealth—is not transparently indexed.
Instead, professional evaluations of such individuals typically rely on:
- Revenue Multiples: Assessing the company’s annual gross revenue against industry standards for direct-selling companies.
- Profit Margins: Estimating the founder’s equity stake and the dividends drawn from annual net profits.
- Liquidity Events: Analyzing whether the founder has conducted private equity sales, company acquisitions, or business pivots that allow for capital realization.
When discussing Monroe’s financial standing, commentators often conflate the company's annual revenue—which at times exceeded $700 million—with the founder's personal wealth. This is a common error. A founder’s net worth is defined by their share of equity, personal investment portfolio, and real estate assets, rather than the top-line revenue generated by the business they oversee.
Historical Context and Corporate Evolution
By the mid-2010s, the landscape for direct-selling companies shifted due to the rise of e-commerce and changing consumer behaviors. Thirty-One Gifts, like many of its peers, faced increased competition from traditional retail and digital marketplaces. In 2020, the company underwent a significant change when it was acquired by a private equity firm, a move that fundamentally altered the ownership structure and likely provided a liquidity event for the founders.
Understanding this transition is vital for context. While Monroe’s wealth was heavily tied to the company's valuation during its independent operation, the sale of the business represented a transformation of that wealth from an operational business stake into a more diversified financial portfolio.
Factors Influencing Wealth Disparity in Estimates
Readers researching Monroe often encounter disparate figures regarding her wealth. These variations arise from several technical factors:
- Asset Volatility: The valuation of private firms is highly sensitive to market downturns and shifts in consumer discretionary spending.
- Lack of Disclosure: Unlike public company CEOs, Monroe is not subject to SEC disclosure requirements regarding her compensation, stock holdings, or asset sales.
- Estimation Methodology: Different analysts use varying criteria. Some calculate net worth based on the company's total historical sales volume, while others look only at liquid assets and real estate holdings. Neither approach offers a perfect reflection of private wealth.
Comparative Industry Standards
To better gauge the financial reality, it is helpful to view Monroe alongside other prominent figures in the direct-sales industry. The following table highlights the primary components that contribute to net worth in this specific niche.
| Component | Role in Wealth Accumulation | Impact on Founder Status |
|---|---|---|
| Equity Stake | Ownership percentage in the parent company. | High: Determines base value. |
| Dividend Income | Periodic distributions of company profit. | Moderate: Provides annual liquidity. |
| Capital Gains | Profit realized upon selling shares or the company. | High: Represents the major wealth shift. |
| Real Estate/Diversification | Reinvestment of business profits into other assets. | Moderate/High: Ensures long-term stability. |
The Role of Personal Branding and Professional Legacy
Beyond the ledger, Monroe’s professional life has been defined by her status as an entrepreneur, author, and speaker. This aspect of her career adds a layer of "brand equity" to her total profile. Public speaking engagements, professional coaching, and book royalties contribute to a diversified income stream that extends beyond the legacy of Thirty-One Gifts.
It is important to differentiate between professional influence and liquid net worth. While Monroe maintains a significant reputation in the business community, this visibility does not always translate into immediate liquid wealth. Her financial status is better framed as the result of a decades-long career in scaling a massive retail operation, followed by a strategic pivot toward private investment and personal brand management.
Common Misconceptions in Financial Reporting
One of the most persistent misconceptions is that a company founder retains 100% of the revenue reported in press releases. In the retail and direct-sales sectors, gross revenue is significantly offset by:
- Consultant Commissions: A major portion of revenue is redistributed to the independent sales force.
- Operational Overheads: Costs related to manufacturing, shipping, logistics, and corporate employee payroll.
- Tax Liabilities: Significant portions of corporate earnings are subject to federal and state corporate taxes before any personal distribution occurs.
When interpreting any report on Cindy Monroe's net worth, one should discount the total revenue of the organization by these factors. True net worth, in this context, is the residual amount remaining after corporate obligations are satisfied and personal assets are accounted for.
Frequently Asked Questions
1. Is the net worth of Cindy Monroe public knowledge? No. Because Thirty-One Gifts was a private company and remains a private entity under its new ownership, Monroe is not required to publicly disclose her finances. Any figure cited in media reports is an estimate, not a verified financial statement.
2. How did the sale of Thirty-One Gifts affect her wealth? The acquisition of the company by private equity essentially crystallized the value of her stake in the business. This moved her wealth from an illiquid, business-dependent position into a more liquid state, allowing for diversification into other investment vehicles.
3. Does Cindy Monroe still own Thirty-One Gifts? Following the corporate restructuring and subsequent acquisitions starting in 2020, Monroe’s role and ownership stake changed. She transitioned from a primary owner-operator to a position that allowed her to focus on broader entrepreneurial and advisory endeavors.
4. Why do estimates of her net worth differ by millions? Discrepancies exist because different sources weigh various factors differently. Some ignore debts or overheads, while others rely on outdated information that fails to account for the company’s recent corporate changes and the broader economic climate of 2026.
5. What is the most accurate way to assess a founder's net worth? The most accurate assessment is to look at their public portfolio of real estate, verified business sales, and publicly known investments. Anything beyond that is speculative and should be viewed with a significant margin of error.
Practical Advice for Researching Personal Finances
For those interested in the financial profiles of high-profile entrepreneurs, it is essential to prioritize official filings where available. If you are conducting research for academic or professional purposes:
- Verify Source Reliability: Prefer reports from established business journals like the Wall Street Journal or Forbes (if available) over unverified celebrity-gossip websites.
- Understand Asset Classes: Remember that personal wealth is often tied up in real estate, private equity, or trusts that do not show up in real-time "wealth trackers."
- Distinguish Between Revenue and Wealth: Always maintain the distinction between the company’s revenue and the individual’s personal net worth.
As of 2026, Cindy Monroe remains a notable figure in the direct-sales and retail space, her career serving as a primary case study in the scalability of home-based business models. Her financial standing is best viewed not through a single static number, but as the culmination of years of organizational leadership and strategic business decisions that have secured her place in the retail industry.

Image Gallery
Select an image to open it in a new tab.


Akira Tanaka
International Academic Trends Correspondent
