
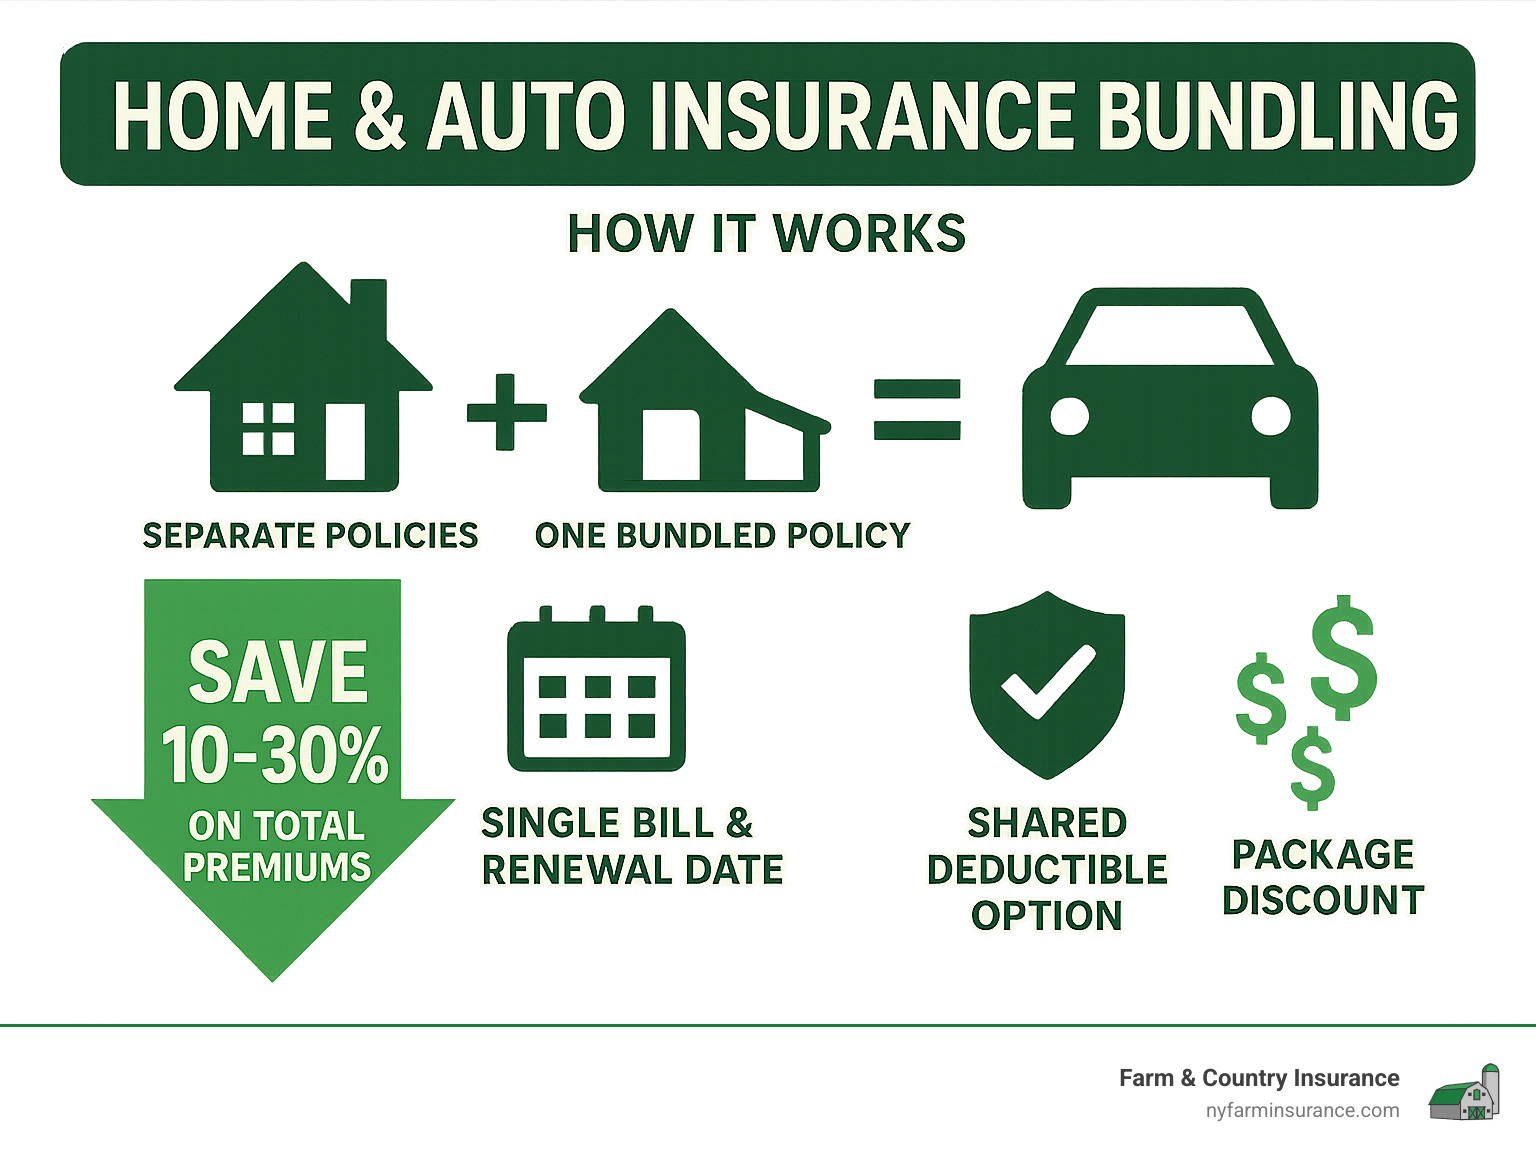
Bundling home and auto insurance is a strategic financial decision that involves purchasing multiple insurance policies from a single carrier to qualify for a multi-policy discount. By combining your primary property and vehicle coverage under one contract or provider, you simplify your administrative tasks while typically reducing your total annual insurance expenditure through streamlined underwriting and lower acquisition costs for the insurer.
The Core Concept of Multi-Policy Bundling
At its most fundamental level, bundling is an incentive program offered by insurance companies to encourage client retention and increase the lifetime value of a policyholder. When you hold both a homeowners insurance policy and an auto insurance policy with the same carrier, you are effectively reducing the risk profile and overhead costs for that insurance provider.
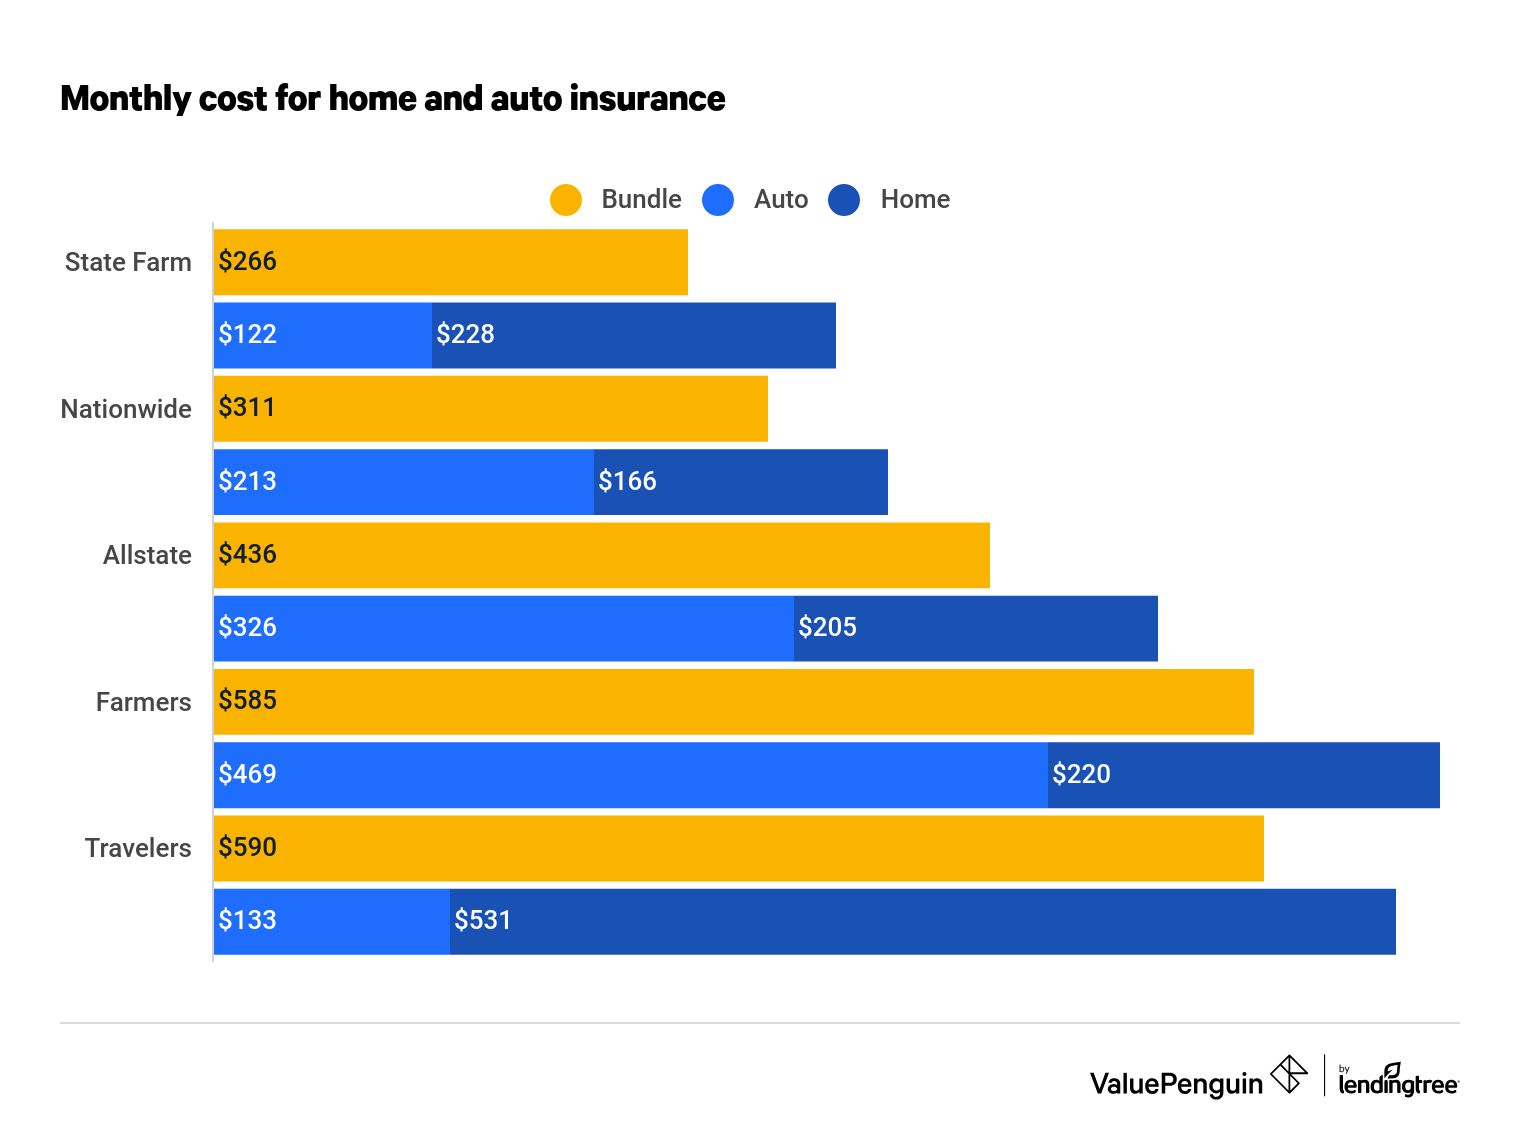
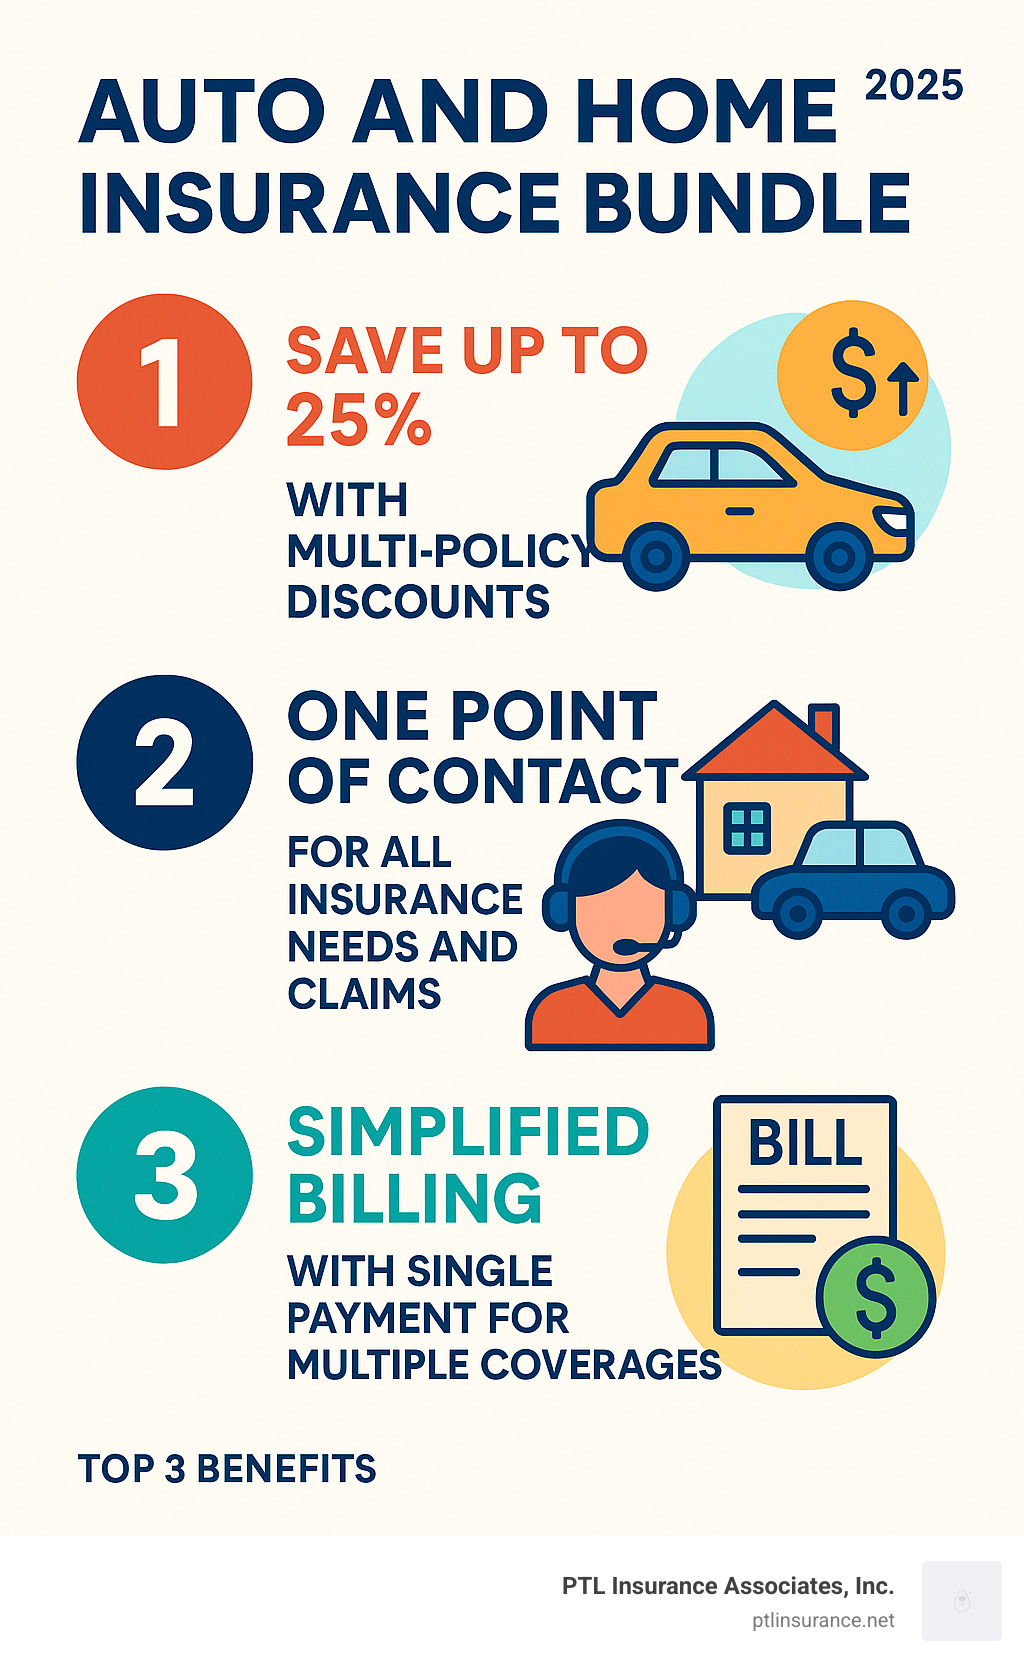
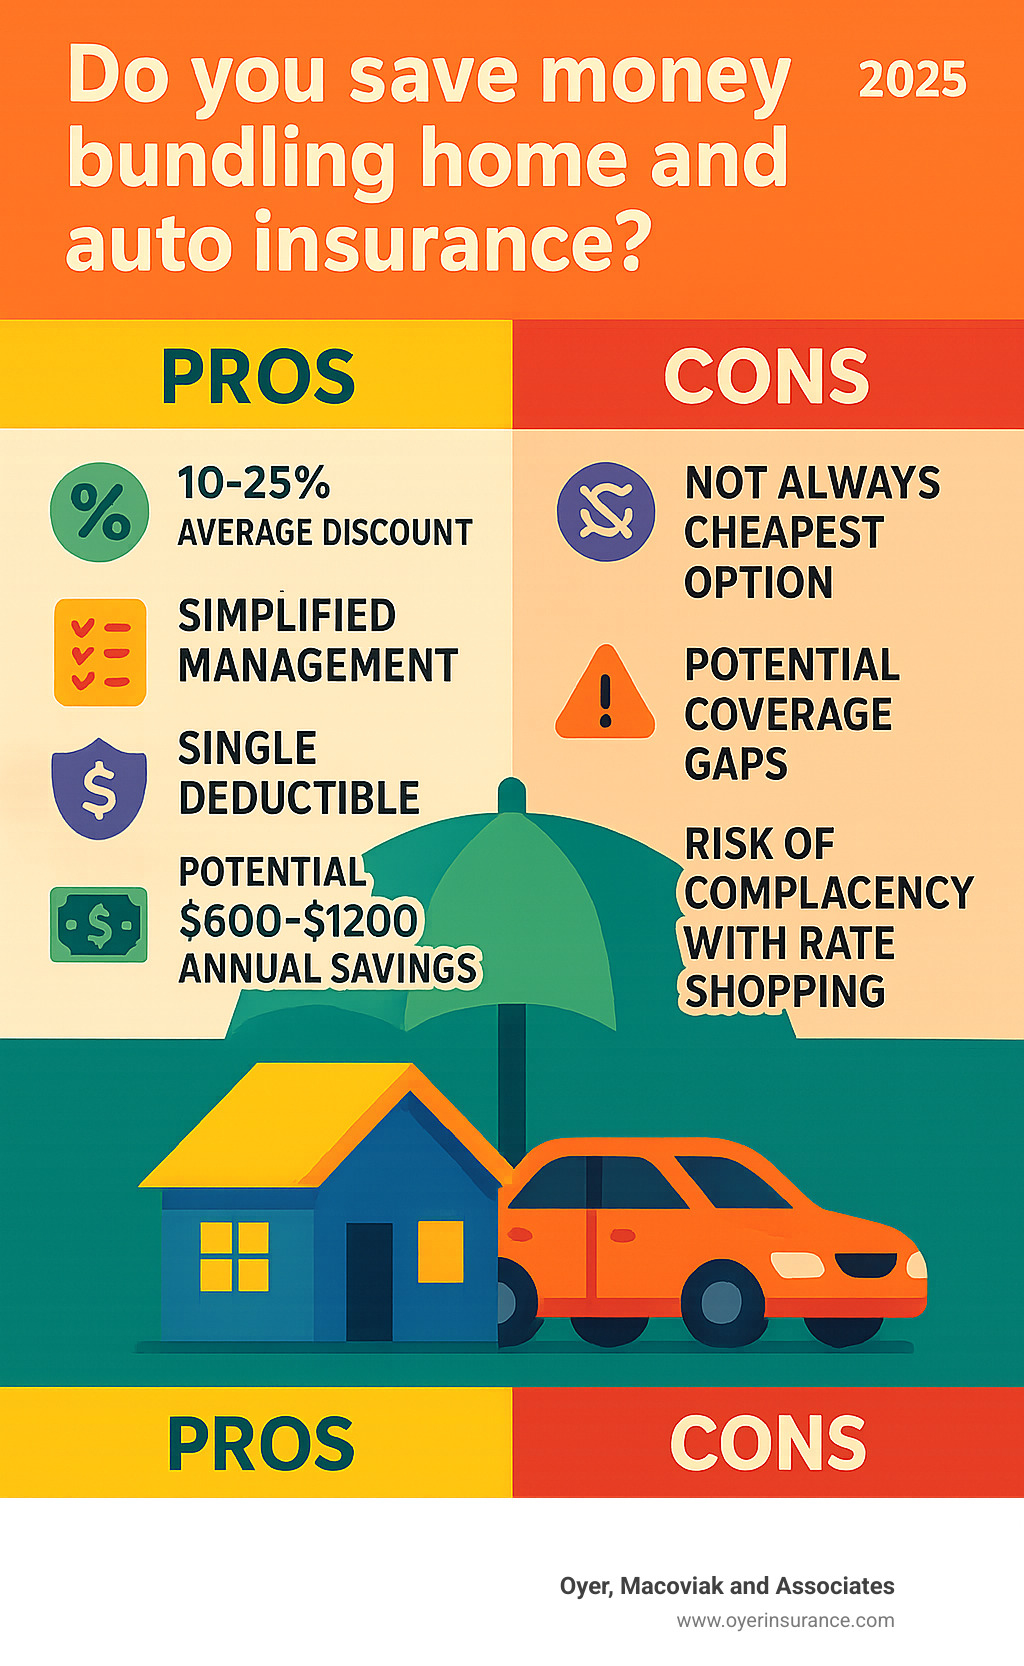
The insurance carrier recognizes that a customer with two or more policies is statistically less likely to switch providers. Because the cost of acquiring a new customer is significantly higher than maintaining an existing one, insurance companies pass some of those savings on to the consumer in the form of a "bundle discount." While the percentages vary significantly by company and geographic location, these discounts can range anywhere from 5% to 25% of the total premium.
Prerequisites for Bundling
Before you can effectively bundle your policies, you must meet certain eligibility requirements set by the insurance market in 2026. Understanding these prerequisites is essential for navigating the transition from separate carriers to a single, unified provider.
Asset Verification and Ownership
To bundle home and auto policies, you must generally own or have a legal interest in both the residence and the vehicle. For homeowners insurance, this includes single-family homes, townhomes, and, in some cases, condominium units. For auto insurance, the carrier will require proof of ownership or a lease agreement. If your vehicle is financed, the lender will likely require you to maintain full coverage (collision and comprehensive), which is a standard feature in most bundle-ready policies.
Underwriting Alignment
Insurance companies operate on individual underwriting guidelines. A major hurdle for some homeowners is the "claims history" or "risk rating" of the property. If your home has a history of high-severity claims, or if your driving record includes multiple at-fault accidents or traffic violations, a carrier may be willing to cover one of your assets but refuse to bundle the other. You must ensure that your overall risk profile remains within the "preferred" or "standard" category of the insurer you choose.
Financial and Administrative Benefits
The most commonly cited benefit of bundling is the reduction in premiums, but the advantages extend into the operational side of managing your personal finances.
Premium Efficiency
By concentrating your risk with one company, you often unlock "account-level" discounts that are not available to single-policy holders. For example, some insurers offer a "vanishing deductible" or "disappearing deductible" program that rewards long-term, multi-policy customers by reducing their deductible for every year they remain claim-free.
Simplified Claims Processing
In the event of a catastrophic event—such as a major storm that damages both your home and your car—managing a single insurance company can be significantly less stressful. You deal with one adjuster, one point of contact, and one set of paperwork. This minimizes the risk of finger-pointing between two different carriers regarding which policy is responsible for damage caused by overlapping perils (e.g., a tree falling on your car in your driveway).
Single Renewal Dates
Managing multiple expiration dates leads to a higher risk of a lapse in coverage. If you forget to renew your auto insurance, you face legal consequences and potential insurance rating penalties. Bundling aligns your renewal cycles, making it easier to track your financial obligations and ensure that your coverage remains continuous.
Evaluating the Risks and Considerations
While bundling is generally advantageous, it is not a "one-size-fits-all" solution. There are specific scenarios where keeping your policies separate may be the more prudent financial move.
Market Specialization
Some insurance carriers are highly specialized. A carrier that excels at providing competitively priced, high-performance auto insurance might have an average or subpar homeowners insurance product, and vice versa. You may find that while a bundle discount makes the combined price look attractive, buying the best auto policy from Company A and the best homeowners policy from Company B individually could result in a better total value, even without the bundle discount.
The "All Eggs in One Basket" Factor
Consolidating your coverage with one carrier means that if the company undergoes a significant rate increase or changes its underwriting guidelines in your state, your entire insurance portfolio is impacted simultaneously. You may find it more difficult to shop around for a better rate if you have to move both your home and auto policies at once, especially if your current home policy has been "grandfathered" into favorable terms that no longer exist in the open market.
Comparison Table: Bundled vs. Individual Coverage
| Feature | Bundled Policies | Individual Policies |
|---|---|---|
| Average Cost | Typically lower (via multi-policy discount) | Higher (lose loyalty/volume incentives) |
| Administration | One point of contact, one bill | Multiple contacts, multiple bills |
| Renewal Cycle | Aligned (simplified) | Often misaligned (risk of lapse) |
| Market Access | Limited to the specific carrier's options | Ability to cherry-pick best-in-class |
| Claims Efficiency | High (single adjuster) | Low (potential conflict between insurers) |
How to Conduct a Strategic Comparison
To determine if bundling is right for your specific situation in 2026, follow a systematic approach to comparison shopping. Never rely on the initial quote provided by an insurance agent without verifying the underlying coverage limits.
- Define Your Coverage Needs: Before seeking quotes, determine your necessary coverage limits for both home (dwelling replacement cost, personal property, liability) and auto (bodily injury liability, property damage, collision, comprehensive).
- Solicit Independent Quotes: Approach three to five independent insurance agencies. Ask for a quote for each policy individually and a separate quote for the bundled option.
- Review the Fine Print: Ensure the bundled quote does not reduce your coverage limits to achieve the lower price. Check the "declarations page" of the bundle quote to ensure all standard endorsements (such as water backup coverage for home or gap insurance for auto) are included.
- Factor in the Renewal Increase: Ask the agent about the average annual premium increase for the company over the last three years. A large bundle discount today may be negated by aggressive rate hikes in the future.
Frequently Asked Questions (FAQ)
Does bundling affect my insurance credit score?
Bundling itself does not negatively impact your insurance-based credit score. In fact, maintaining a consistent, long-term relationship with one carrier can sometimes bolster your internal rating with that specific company, provided your payments remain on time.
Can I bundle renters insurance with auto insurance?
Yes, most major carriers offer a "renters and auto" bundle. This is often an excellent way to lower your auto premium, especially for younger drivers or those in urban environments who do not yet own property but require comprehensive vehicle coverage.
What happens if I move to a state where my current insurer does not operate?
If your insurance carrier is not licensed in your new state, you will be forced to unbundle. This is a common occurrence in the United States insurance market. If this happens, ensure you secure your new policies before canceling the old ones to avoid a lapse in coverage, which can lead to higher rates in the future.
Are there any downsides to having a single deductible?
Bundling does not usually change your deductible structure. You will generally still have a separate deductible for your home policy (often a percentage of the dwelling coverage) and a separate deductible for your auto policy (a fixed dollar amount). Be wary of policies that offer "combined" deductibles, as these are rare and often carry high premiums.
Is the bundle discount applied to the home or auto portion of the bill?
The discount is typically applied to the premium of both policies, but the percentage may differ. For example, an insurer might apply a 15% discount to the auto portion and a 10% discount to the home portion. Always examine the premium breakdown to see where the savings are being applied.
Final Recommendation: Proactive Management
The decision to bundle home and auto insurance should be reviewed every two to three years. Market conditions change rapidly, and the carrier that offered the best bundle discount in 2024 may not be the most competitive option in 2026. Maintain a digital folder containing your current declaration pages. When you receive your annual renewal notice, take thirty minutes to compare your current premiums against the quotes available on the broader market. If your current carrier’s rate has crept above the market average—even with the bundle discount applied—do not hesitate to quote your policies separately or with a different multi-policy carrier. Professional insurance agents, particularly independent brokers, are the best resource for performing this comparative analysis on your behalf.
Image Gallery
Select an image to open it in a new tab.


Lars Thomsen
Global Labor Markets and Economic Strategy Editor
