To determine if your net worth is positive or negative, subtract the total sum of your liabilities (everything you owe) from the total value of your assets (everything you own). A positive result indicates a positive net worth, while a result below zero signifies a negative net worth.
Calculating your net worth is the primary method for assessing your overall financial health in 2026. While monthly cash flow tells you if you can pay your bills today, net worth provides a "big picture" view of your long-term stability and wealth accumulation. Whether you are preparing for retirement, applying for a major loan, or simply trying to get out of debt, understanding this single number is the first step toward financial agency.
Understanding the Fundamentals of the Net Worth Equation
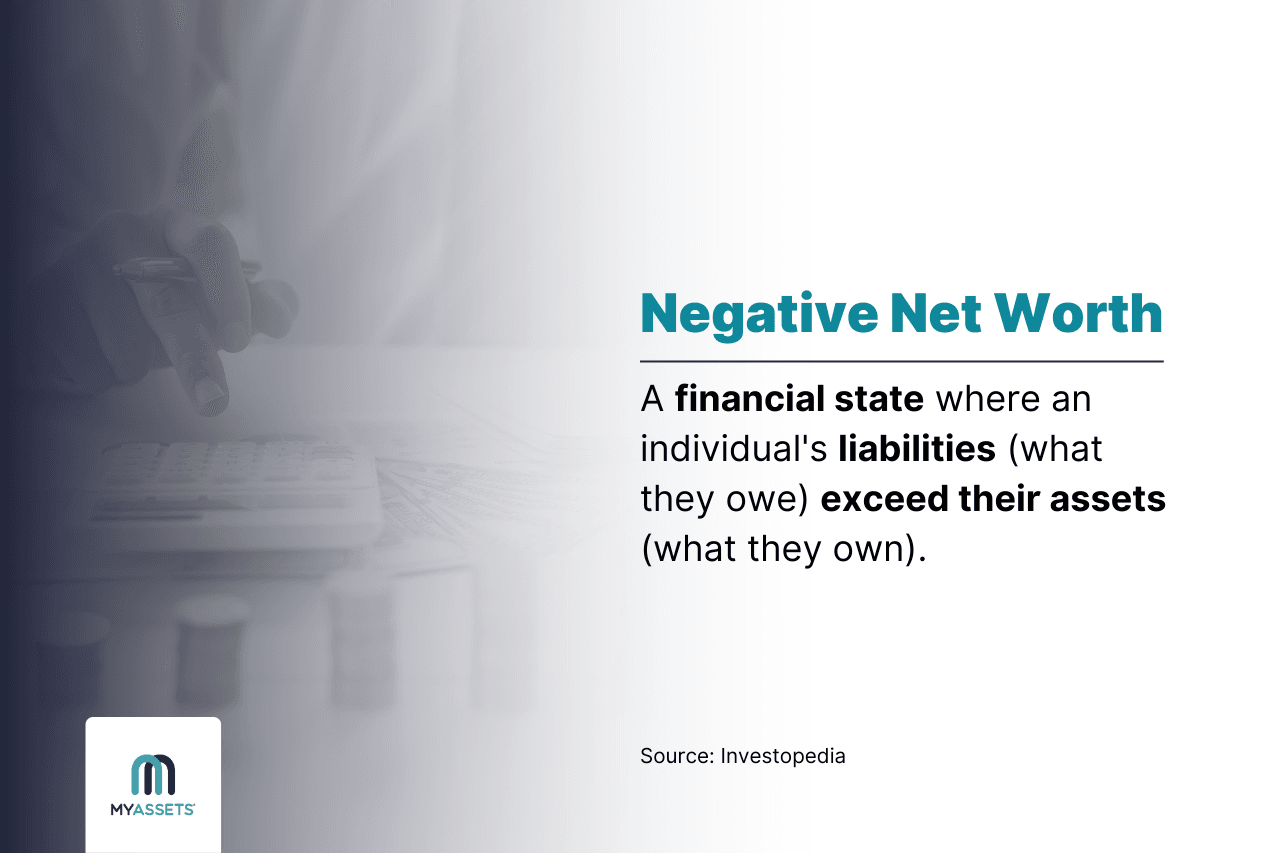
The mathematical foundation of net worth is deceptively simple: Assets - Liabilities = Net Worth. However, the nuance lies in how you categorize and value these components. In a 2026 economic landscape characterized by diverse asset classes—ranging from traditional real estate to digital holdings—tracking these figures requires precision and a clear understanding of current market values.
Defining Assets
An asset is anything of value that you own which can be converted into cash. In personal finance, assets are typically divided into liquid assets (cash and its equivalents) and non-liquid or "fixed" assets (items that take time to sell). To get an accurate reading of your net worth, you must use the current fair market value of these items, not the price you originally paid for them.
Defining Liabilities
A liability is a financial obligation or debt that you owe to another person or institution. These are the "anchors" that pull your net worth down. Just as with assets, you must use the current payoff balance of these debts, which includes any accrued interest as of the current date in 2026, rather than the original loan amount.
The Comprehensive Breakdown of Assets
To see if your net worth is positive or negative, you must first perform a rigorous inventory of your assets. Many people overlook smaller accounts or fail to account for the depreciation of physical goods, leading to an inflated sense of wealth.
Liquid Assets and Cash Equivalents
These are the most accessible forms of wealth. They represent your immediate "buying power" and safety net.
- Checking and Savings Accounts: The balance currently sitting in your bank accounts.
- Emergency Funds: Specialized high-yield savings accounts designated for crises.
- Certificates of Deposit (CDs): While they have maturity dates, they are considered cash equivalents because they have a fixed cash value.
- Money Market Accounts: Interest-bearing accounts that typically offer higher rates than standard savings.
Investment Portfolios
In 2026, investment portfolios often include a mix of traditional and modern vehicles.
- Brokerage Accounts: Taxable accounts containing stocks, bonds, and Exchange-Traded Funds (ETFs).
- Retirement Accounts: 401(k) plans, 403(b) plans, IRAs, and Roth IRAs. Note that for net worth purposes, you should record the current balance, even if there are tax implications for early withdrawal.
- Cryptocurrencies and Digital Assets: Bitcoin, Ethereum, and other verified digital tokens. Given their volatility, these should be valued at the specific market rate on the day of your calculation.
Real Estate and Personal Property
For many, the home is the largest asset. However, it is also the one most prone to valuation errors.
- Primary Residence: Use a conservative estimate based on recent comparable sales (comps) in your neighborhood.
- Investment Properties: Any rental units or land you own.
- Vehicles: Cars, motorcycles, and boats. Use valuation tools like Kelley Blue Book to find the "private party" value, as vehicles are depreciating assets.
- High-Value Personal Items: Jewelry, fine art, and rare collectibles. These should only be included if they have a verified resale value of over $1,000 to avoid cluttering your balance sheet with household junk.
The Comprehensive Breakdown of Liabilities
Liabilities represent your total debt load. To see if your net worth is negative, you must be honest about every dollar you owe.
Secured Debts
These are loans backed by collateral. If you stop paying, the lender can seize the asset.
- Mortgages: The remaining principal balance on your home loan.
- Home Equity Lines of Credit (HELOC): Any outstanding balance you have borrowed against your home's value.
- Auto Loans: The payoff amount for your vehicle.
Unsecured Debts
These debts are not backed by collateral and often carry higher interest rates.
- Credit Card Balances: The total current balance across all cards, not just the "minimum payment" or the statement balance.
- Student Loans: Federal and private loans used for education.
- Personal Loans: Unsecured loans from banks, credit unions, or peer-to-peer lenders.
- Medical Debt: Any outstanding bills for healthcare services.
Other Obligations
- Taxes Owed: Any back taxes or estimated tax payments due to the IRS or state authorities.
- Private Debts: Money borrowed from friends or family members that you intend to repay.
How to Calculate Your Net Worth: A Step-by-Step Guide
Follow these steps to reach your final number. It is helpful to use a spreadsheet or a dedicated financial tracking app to keep these figures organized.
- List Your Assets: Create a column for all assets. Write down the current value of each. Total this column to find your Total Assets.
- List Your Liabilities: Create a second column for all debts. Write down the current payoff balance for each. Total this column to find your Total Liabilities.
- Perform the Subtraction: Subtract Total Liabilities from Total Assets.
- Analyze the Sign:
- If the number is positive (e.g., +$15,000), you have a positive net worth.
- If the number is negative (e.g., -$15,000), you have a negative net worth.
Comparison Table: Assets vs. Liabilities
| Category | Item Examples | Impact on Net Worth | Valuation Basis (2026) |
|---|---|---|---|
| Cash Assets | Checking, Savings, Cash | Increases (+) | Face Value |
| Investments | Stocks, 401(k), Crypto | Increases (+) | Current Market Price |
| Fixed Assets | Home, Car, Jewelry | Increases (+) | Resale/Appraised Value |
| Secured Debt | Mortgage, Car Loan | Decreases (-) | Current Payoff Balance |
| Unsecured Debt | Credit Cards, Student Loans | Decreases (-) | Current Statement Balance |
| Tax Debt | IRS Owed, State Taxes | Decreases (-) | Total Amount Due |
Interpreting a Positive Net Worth
A positive net worth means that if you were to sell everything you own and pay off every debt you have, you would still have cash left over.
What it Signals
In the context of 2026 financial standards, a positive net worth signals that you are living below your means and building equity. It provides a "buffer" against economic downturns. For those in their 40s and 50s, a significantly positive net worth is essential for a viable retirement strategy.
The Nuance of Liquidity
It is possible to have a positive net worth but still be "house poor." For example, if you have $500,000 in home equity but only $100 in your checking account, your net worth is positive, but your liquidity is low. True financial health requires a balance between illiquid equity (like a home) and liquid cash (like a savings account).
Understanding a Negative Net Worth
Finding out you have a negative net worth can be jarring, but it is a common reality for many, particularly younger adults and recent graduates. It essentially means you are "underwater"—you owe more than the total value of your earthly possessions.
When Negative Net Worth is Normal
- Recent Graduates: High student loan balances paired with entry-level salaries and few assets often result in a negative net worth. As long as the "human capital" (earning potential) is high, this is often a temporary phase.
- New Homeowners in a Market Dip: If you bought a home with a small down payment and the local real estate market dipped shortly after, you might temporarily owe more on the mortgage than the house is worth.
- Strategic Business Owners: Some entrepreneurs take on significant debt to scale a business. While their personal balance sheet looks negative, the goal is for the business asset to eventually outgrow the debt.
When Negative Net Worth is a Red Flag
If a negative net worth is driven by high-interest consumer debt (credit cards) and lifestyle inflation, it indicates a structural flaw in your finances. Without intervention, interest will compound, making the "hole" deeper every year.
Tools for Tracking Net Worth in 2026
Modern technology has made it significantly easier to see if your net worth is moving in the right direction without manual tallying.
- Automated Aggregators: Services like Empower, Mint (or its 2026 successors), and specialized banking apps link directly to your accounts via secure APIs. They pull real-time data to give you a daily net worth update.
- Spreadsheet Templates: For those who prioritize privacy, a simple Excel or Google Sheets document is highly effective. Manually updating your numbers once a month encourages "mindful spending."
- Real Estate Valuation APIs: Tools integrated into real estate platforms now provide monthly "Zestimates" or similar valuations that can be pulled automatically into your net worth tracker to keep home equity figures current.
Common Mistakes to Avoid
To ensure your net worth calculation is accurate, avoid these common pitfalls:
- Including Future Income: Net worth is a snapshot of now. Do not include expected bonuses, future inheritance, or salary you haven't earned yet.
- Overestimating Asset Value: Many people list their car at the price they bought it for. Vehicles lose value the moment they leave the lot. Always use the current "Blue Book" value.
- Ignoring Small Debts: That "Buy Now, Pay Later" (BNPL) balance or the $500 owed to a family member counts. These small leaks can collectively shift a net worth from positive to negative.
- Forgetting "Hidden" Assets: Don't forget the cash value of a life insurance policy or the balance in a Health Savings Account (HSA), which can be used for medical expenses.
Strategic Next Steps
Once you know your number, the path forward depends on the result.
If Your Net Worth is Negative:
Focus on the "Debt Avalanche" or "Debt Snowball" methods. The goal is to aggressively reduce liabilities. If your debt is high-interest, consider consolidation to lower the interest rate, which allows more of your payment to go toward the principal balance. Simultaneously, try to build a small $1,000 emergency fund so that new crises don't force you to take on more debt.
If Your Net Worth is Positive:
Focus on asset growth and protection. This involves optimizing your investment accounts, ensuring you are maximizing employer matches in retirement plans, and diversifying your assets to protect against market volatility. You should also look at your debt-to-asset ratio; even with a positive net worth, high-interest debt should be eliminated to accelerate wealth building.
Professional Advice Limitation
The information provided here is for educational purposes and reflects general financial principles as of 2026. It does not constitute legal, tax, or financial advice. Individual financial situations vary significantly based on jurisdiction, tax brackets, and specific loan terms. Consult with a Certified Financial Planner (CFP) or a qualified tax professional before making significant changes to your investment strategy or debt management plan.
Frequently Asked Questions
Is a negative net worth the same as being bankrupt? No. Bankruptcy is a legal process that occurs when you cannot meet your debt obligations. Many people have a negative net worth (such as doctors with $300,000 in student loans) but are not bankrupt because they have the cash flow to make their monthly payments. Negative net worth is a status; bankruptcy is a legal filing.
Should I include my furniture and clothes in my assets? Generally, no. Unless you own high-end designer items or antiques with a proven resale market, most household goods have a negligible resale value. Including them creates a "false positive" in your net worth calculation. Focus on assets that a bank would recognize as having significant value.
How often should I calculate my net worth? Checking your net worth once a quarter (every three months) is ideal. Checking it daily can lead to unnecessary stress due to market fluctuations, while checking it once a year may be too infrequent to catch negative trends early enough to fix them.
Can I have a high income and a negative net worth? Yes. This is often referred to as "HENRY" (High Earner, Not Rich Yet). High income allows for a high standard of living, but if that income is entirely consumed by lifestyle expenses and debt payments, the individual’s net worth will remain low or negative. Wealth is what you keep, not what you spend.
Does my net worth include my partner's assets? This depends on your legal status. If you are married or in a legal partnership, you may calculate a "household net worth" which includes all joint assets and debts. If you are single or keep finances separate, you should only include assets and liabilities for which you are legally responsible.
Image Gallery
Select an image to open it in a new tab.

Celine Dubois
Contemporary Living and Global Arts Columnist
