
Ben Feldman’s "disturbing questions" are strategic inquiries designed to force prospects to confront the financial consequences of death, disability, and taxation. By moving the conversation from a technical product discussion to an emotional and practical reality, these questions highlight the "problem" of unfunded liabilities, ensuring the prospect recognizes the immediate need for a life insurance solution.
Ben Feldman (1912–1993) is widely considered the most successful life insurance salesman in history. During his legendary career with New York Life, he personally placed more insurance than most mid-sized insurance companies combined. His secret did not lie in complex actuarial tables or high-pressure closing techniques; instead, it centered on the "Feldman Method." At the heart of this method are "disturbing questions"—short, punchy inquiries that strip away a prospect's complacency and expose the fragility of their financial legacy.
As of 2026, Feldman’s insights remain more relevant than ever. Despite the evolution of digital underwriting and automated financial planning tools, the fundamental psychological barriers to purchasing life insurance—procrastination, the denial of mortality, and the underestimation of tax burdens—persist. Understanding the disturbing questions Ben Feldman raises is essential for any financial professional or individual looking to secure a legacy against the unpredictable nature of time and the certainty of taxation.
The Philosophy of "Disturbance" in Financial Planning
Feldman believed that most people do not buy life insurance because they do not believe they have a problem. To him, the salesman’s job was to "disturb" the prospect’s peace of mind just enough to make them realize that their current financial state is precarious. He famously stated, "You don’t sell life insurance. You sell a solution to a problem."
The "disturbing" element isn't about being rude or morbid; it is about intellectual and emotional honesty. In the 2026 fiscal landscape, where estate tax exemptions have shifted significantly following the sunsetting of the 2017 Tax Cuts and Jobs Act provisions, many high-net-worth individuals find themselves with increased tax liabilities that they have not yet addressed. Feldman’s questions pierce through the layers of "I'll think about it later" by making "later" feel like "now."
The Concept of the "Problem"
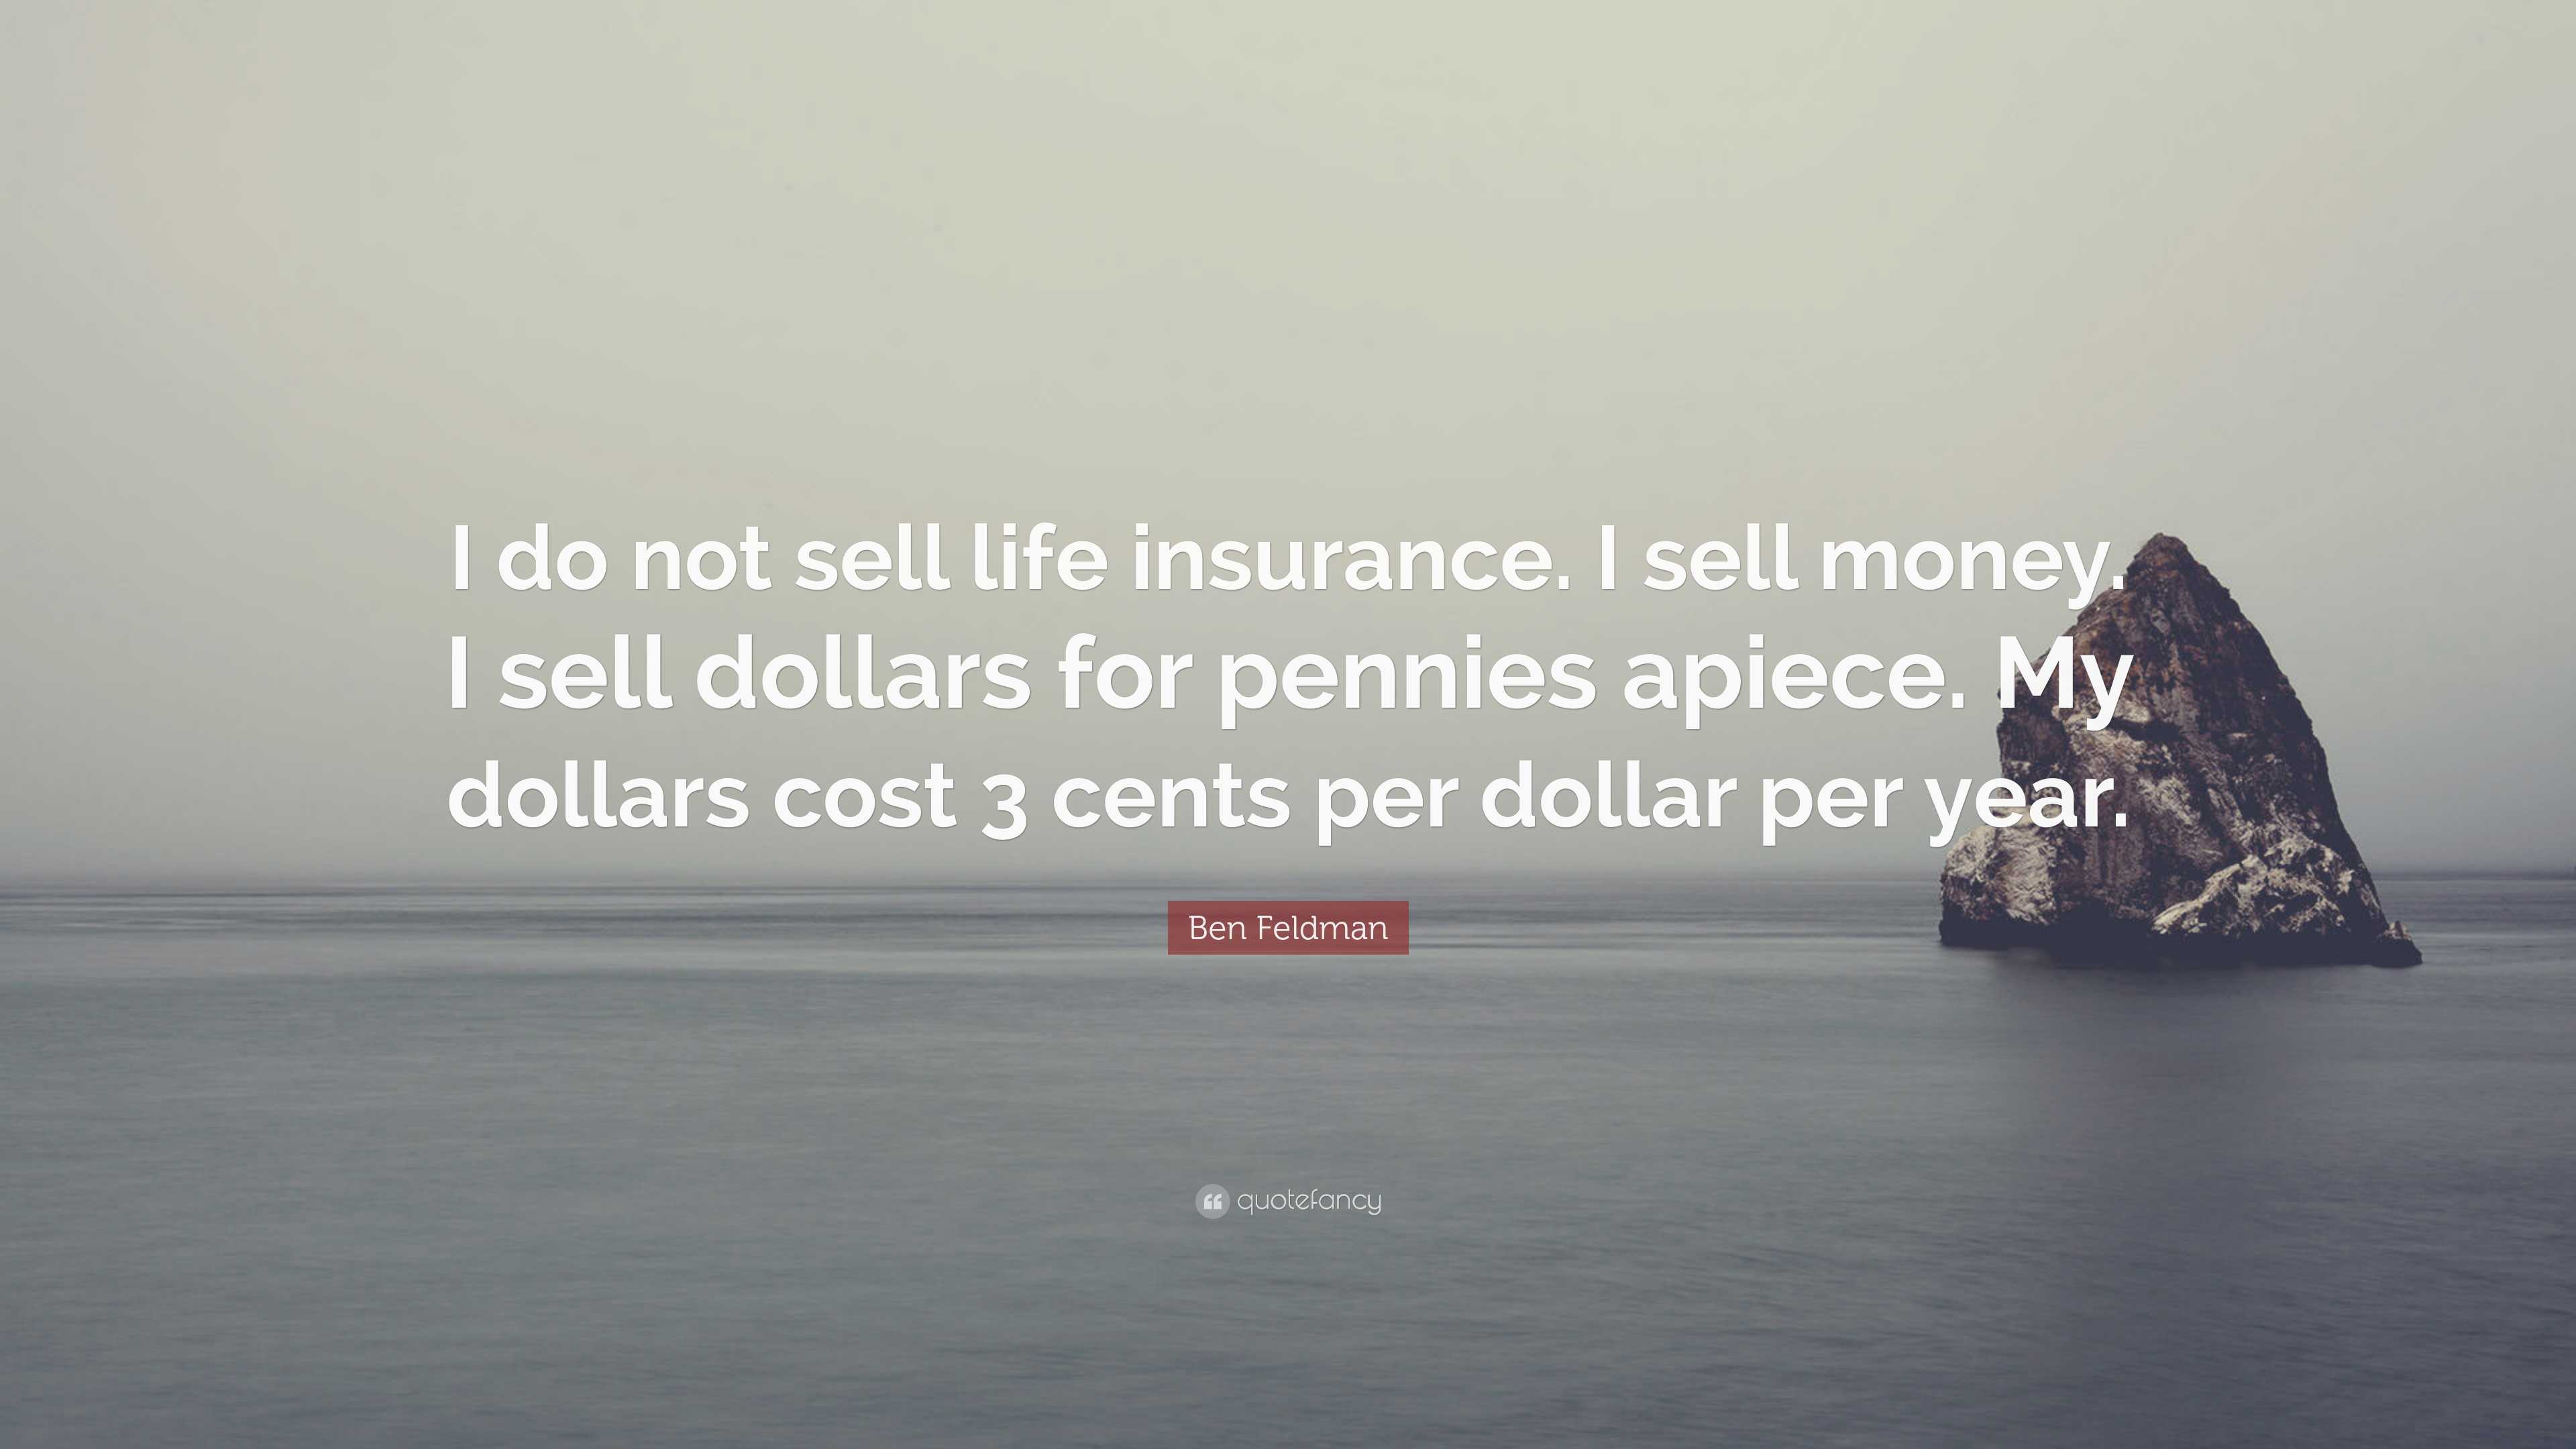
Feldman’s logic was simple: Every person has a problem, but they usually don’t know it. The problem is usually a lack of liquidity at the exact moment it is needed most—death. He framed life insurance not as a cost, but as "pennies that buy dollars," a way to create an instant estate when the clock runs out. By asking a disturbing question, the agent forces the prospect to define the size of their problem in their own words.
Analysis of Feldman’s Most Impactful Questions
Feldman’s questions were often fewer than ten words. Their power lay in their brevity and the silence that followed. In 2026, these inquiries continue to serve as the gold standard for uncovering hidden financial needs.
1. "How much are you worth?"
This seems like a standard financial discovery question, but Feldman used it to lead into a deeper analysis of "Human Life Value." He would follow up with, "If you had a machine that produced $500,000 a year, would you insure the machine?" When the prospect said yes, he would point out that they are the machine. This question disturbs the prospect by highlighting the massive financial void their absence would create for their family or business.
2. "Would you like to buy your own business back from the IRS?"
This question is particularly relevant for business owners in 2026. Many entrepreneurs have their entire net worth tied up in their company. When they die, the IRS (Internal Revenue Service) expects its share of the estate value in cash. Without life insurance, the heirs may be forced to sell the business to pay the taxes. Feldman framed life insurance as the only way to "buy back" the business for pennies on the dollar before the tax bill arrives.
3. "Is your problem one of lack of money or one of time?"
This is perhaps the most disturbing question Feldman ever raised. It forces the prospect to admit that while they might have the talent to build wealth, they do not have a guarantee of the time required to do so. It positions life insurance as the "purchase of time." If the prospect dies tomorrow, the insurance provides the capital that the prospect would have earned had they lived another 20 years.
4. "What will happen to the things you own after you are gone?"
This question targets the "transfer" of wealth. Feldman would often point out that "The things you own will be there after you’re gone, but you won't be there to manage them." It forces a discussion on estate liquidity, management succession, and the protection of heirs who may not have the business acumen to maintain the estate's value.

The Feldman Method: Technical Execution and Strategy
Applying these questions requires more than just memorizing lines. Feldman’s approach involved a specific sequence of "disturb, simplify, and solve."
The Use of Visual Aids and Simple Math
Feldman never used complex spreadsheets. He used a yellow legal pad and wrote in big, bold numbers. He would draw a line down the middle of the page: on one side, the "Cost" (the premium), and on the other, the "Benefit" (the death benefit). By showing that the premium was only 2% or 3% of the benefit, he made the decision to buy insurance look like a logical bargain. He called this "buying money for future delivery."
The Power of Silence
After asking a disturbing question, Feldman would remain completely silent. He understood that the prospect needed time to process the weight of the question. The silence becomes a pressure cooker where the prospect is forced to confront their own mortality and the potential failure of their financial legacy.
Permanent Life Insurance as "Property"
Feldman viewed life insurance as "the most remarkable piece of property a man can own." Unlike real estate or stocks, which can fluctuate in value or be difficult to liquidate, life insurance is "cash that is guaranteed to be there at the exact moment it is needed." In the 2026 market, where volatility in global markets remains a concern, this "guaranteed property" concept is a powerful stabilizing argument.
Practical Comparison: Traditional Selling vs. The Feldman Approach
| Feature | Traditional Sales Approach | Ben Feldman’s "Disturbing" Approach |
|---|---|---|
| Primary Goal | Sell a policy or product. | Solve a specific financial "problem." |
| Main Tool | Product features and brochures. | Probing, disturbing questions and a yellow pad. |
| Focus | Cost and premiums. | The value of the "Human Life" and "Discounted Dollars." |
| Tax Context | General tax-deferred growth. | Solving the immediate liquidity crisis for estate taxes. |
| Psychology | Persuasion and persistence. | Making the prospect feel the "pain" of an unfunded liability. |
| Legacy View | A death benefit for heirs. | Buying your business back from the government. |
Modern Application: 2026 Estate and Business Realities
As we navigate 2026, the financial landscape has changed, but the math behind Feldman’s questions remains sound. The primary drivers for using these questions today include:
- Reverted Estate Tax Thresholds: With the expiration of the high exemption limits from the early 2020s, more families are falling into the "taxable estate" category. The question "Who will pay your taxes?" is no longer just for billionaires; it applies to many upper-middle-class professionals and small business owners.
- Increased Business Valuations: Digital transformation and intellectual property have driven business valuations higher. A business owner might be "paper rich" but "cash poor," making the "Buy your business back from the IRS" question vital for survival.
- Longevity Risk vs. Early Death: While medical technology in 2026 has increased life expectancy, the risk of "dying too soon" remains the ultimate financial wildcard. Feldman’s question about "Lack of money or lack of time" addresses this fundamental uncertainty.
Steps to Implement the Feldman Questioning Style
If you are a professional or a family leader evaluating your needs, follow these steps to use the "disturbing" logic effectively:
- Identify the Unfunded Liability: Calculate the total taxes, debts, and income replacement needs that would be triggered by a death today.
- Ask the Hard Question: Instead of looking at premium costs, ask: "If I die tonight, where does the cash come from to pay these specific bills?"
- Calculate the "Discount": Compare the cost of the insurance premium to the total liability. For example, if $5 million in taxes is due, and a policy costs $50,000 a year, you are essentially paying 1% to solve 100% of the problem.
- Acknowledge the "Time" Factor: Accept that you cannot control the length of your life, only the protection of your assets during that life.
Troubleshooting Common Objections to Disturbing Questions
When these questions are raised, prospects often react with defensive "screens." Understanding how to navigate these is key to the Feldman Method.
- "I'm worth more alive than dead." Feldman’s response: "That's exactly the problem. When you're alive, you're an asset. When you're dead, you're a liability (taxes, funeral costs, debt). We need to turn that liability back into an asset for your family."
- "I have enough insurance." Feldman’s response: "You don't have enough insurance; you have a certain amount of money. The question is, is it enough to do the job you want it to do?"
- "The cost is too high." Feldman’s response: "The cost of the insurance isn't the problem. The cost of not having it—the 40% estate tax or the 100% loss of income—is the real cost. Which bill would you rather pay?"
Frequently Asked Questions
Why did Ben Feldman call his questions "disturbing"?
Feldman used the term because these questions are designed to disrupt the prospect's comfort and complacency. By forcing a person to think about the financial destruction their death would cause, he moved them from a state of indifference to a state of urgency.
Are Ben Feldman’s questions still legal and ethical in 2026?
Yes. They are based on fundamental financial truths regarding estate law, taxation, and income replacement. As long as the agent provides accurate information about policy performance and adheres to current FINRA or state insurance regulations, the "disturbing question" technique is a legitimate tool for needs-based selling.
How did Feldman handle "I want to think it over"?
He would often say, "You can think it over all you want, but you can’t think it over for the insurance company. They have to think you over, and they might say no. Let's see if we can get them to say yes first." This shifted the power dynamic and emphasized the "Time" problem.
Does the Feldman Method work for term insurance or only permanent insurance?
While Feldman primarily sold permanent (Whole Life) insurance because of its "property" and "guaranteed liquidity" characteristics, the logic of the "disturbing question" applies to any coverage. The "problem" of a mortgage or a child’s education can be solved by term insurance just as effectively as estate taxes can be solved by permanent insurance.
What is the most famous Ben Feldman quote?
"The hallmarks of a successful man are the problems he leaves behind." This quote encapsulates his entire philosophy: that success creates liabilities, and those liabilities require life insurance to be managed effectively.
Final Recommendation
To master the life insurance disturbing questions Ben Feldman raises, one must move beyond the role of a "salesperson" and become a "problem solver." Start by quantifying your own or your client's "Human Life Value"—the total earnings expected over a remaining career—and then ask: "If this income stream stopped tonight, who would suffer, and by how much?" This simple, disturbing honesty is the most effective way to ensure that a lifetime of hard work is not liquidated by the IRS or lost to the passage of time. For those seeking to implement this, focusing on the "Discounted Dollar" concept is the most practical next step in 2026’s high-stakes financial environment.
Image Gallery
Select an image to open it in a new tab.
Declan O'Connor
Higher Education and Campus Culture Reporter
