
In 2026, the average cost of auto insurance in Scottsdale, Arizona, typically ranges from $1,850 to $2,400 per year for full coverage, depending on your zip code and driving profile. While higher than the Arizona state average, these rates reflect Scottsdale’s high density of luxury vehicles and unique suburban traffic patterns.
Understanding the nuances of auto insurance in Scottsdale requires a deep look at both state-level mandates and local socioeconomic factors. Scottsdale is not a monolith; the insurance landscape for a resident in the high-end developments of North Scottsdale (85262) differs significantly from the urban density of Old Town (85251). As we navigate the 2026 fiscal year, inflation in automotive parts and the rising cost of medical care have pushed premiums upward, making it essential for residents to understand exactly what they are paying for and how to optimize their coverage.
Arizona Minimum Insurance Requirements and Recommendations
Before analyzing specific Scottsdale costs, it is vital to establish the legal baseline. As of 2026, Arizona law continues to require "25/50/15" liability coverage. This serves as the absolute minimum to legally operate a vehicle on public roads.
- $25,000 bodily injury liability per person.
- $50,000 bodily injury liability per accident.
- $15,000 property damage liability per accident.
While these minimums allow you to register a vehicle, they are notoriously inadequate for Scottsdale residents. In a city where the average vehicle value often exceeds $60,000, a $15,000 property damage limit is a significant financial risk. If you are found at fault in a collision involving a high-end electric vehicle or a luxury SUV—common sights on Scottsdale Road—you could easily exceed your policy limits within seconds.
The Importance of Uninsured/Underinsured Motorist Coverage
Arizona historically has a high rate of uninsured motorists. Even in 2026, industry data suggests that approximately 12% to 15% of drivers in the Greater Phoenix area lack active insurance. In Scottsdale, where medical costs at facilities like HonorHealth are substantial, adding Uninsured Motorist (UM) and Underinsured Motorist (UIM) coverage is considered a technical necessity rather than an optional luxury. This coverage protects you if you are hit by a driver who has no insurance or whose limits are too low to cover your medical expenses.
Average Auto Insurance Costs in Scottsdale (2026 Estimates)
The cost of insurance in Scottsdale is influenced by the city's reputation for luxury and its specific geographical layout. Below is a breakdown of estimated annual premiums based on common driver profiles in 2026.
| Driver Profile | Estimated Annual Premium (Full Coverage) | Estimated Monthly Payment |
|---|---|---|
| Clean Record (Age 35-55) | $1,920 - $2,150 | $160 - $179 |
| Teen Driver (Age 16-19) | $4,800 - $6,200 | $400 - $517 |
| Senior Driver (Age 65+ ) | $2,050 - $2,300 | $171 - $192 |
| Driver with One At-Fault Accident | $2,700 - $3,200 | $225 - $267 |
| High-Net-Worth (Luxury/Exotic Vehicle) | $3,500 - $5,500+ | $292 - $458+ |
Note: These figures assume a standard $500 or $1,000 deductible and common liability limits of 100/300/100.

Factors Driving Scottsdale Insurance Rates
Why does a resident in Scottsdale pay more than someone in Tucson or Yuma? The answer lies in a combination of high-value claims, environmental factors, and local infrastructure.
1. The Luxury Vehicle Factor
Scottsdale has one of the highest concentrations of luxury and performance vehicles in the Southwest. For insurers, this presents a "double-edged sword" of risk. First, the cost to repair a vehicle like a Lucid Air, a Porsche 911, or a Cadillac Escalade is exponentially higher than a standard sedan due to specialized parts and calibrated sensors (ADAS). Second, even if you drive a modest vehicle, the statistical likelihood that you will collide with an expensive vehicle is higher in Scottsdale than in almost any other Arizona city. This increases the "Property Damage" portion of everyone's premium.
2. Traffic Patterns and the Loop 101
The Pima Freeway (Loop 101) serves as the primary artery for Scottsdale. It is characterized by high speeds and heavy congestion during "snowbird" season (January through April). The influx of seasonal residents and tourists increases vehicle density, leading to a seasonal spike in minor collisions and "fender benders." Insurance companies adjust rates based on this predictable surge in claim frequency.
3. Environmental Risks: Heat and Monsoons
The Arizona climate plays a technical role in insurance pricing. Scottsdale's extreme summer heat leads to a high frequency of mechanical failures, specifically tire blowouts and battery deaths, which can lead to accidents. Furthermore, the monsoon season brings localized flooding and "haboobs" (dust storms). Comprehensive coverage is essential in Scottsdale to protect against hail damage and falling debris during these storms, which have become more unpredictable in the mid-2020s.
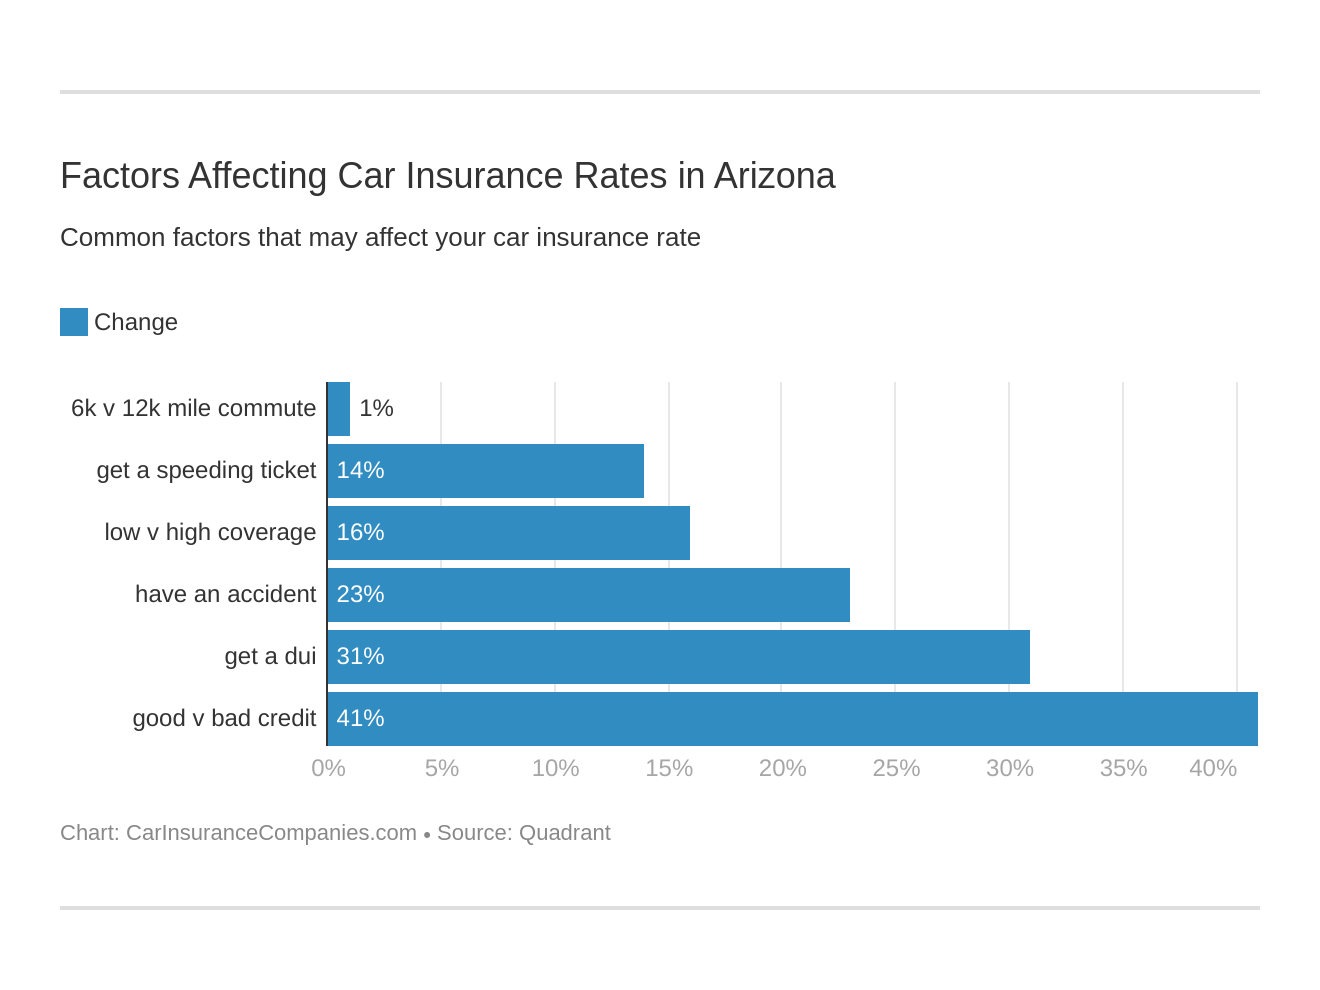
4. Credit-Based Insurance Scores
Arizona is a state that allows insurers to use credit-based insurance scores to help determine premiums. In Scottsdale, where the average credit score tends to be higher than the national average, many residents benefit from this. However, those with a "thin" credit file or recent financial setbacks may find their insurance quotes significantly higher than their neighbors, even with an identical driving record.
Geographic Variations Within Scottsdale Zip Codes
Insurance is priced at the hyper-local level. A move of just three miles can change your premium by 10% or more.
- 85251 and 85250 (Central/Old Town): These areas often see higher rates due to higher theft rates and increased pedestrian traffic. The nightlife scene in Old Town contributes to a higher actuarial risk of late-night accidents.
- 85255 and 85260 (North Scottsdale): Generally, these zip codes enjoy slightly lower premiums for standard vehicles due to lower crime rates and gated communities. However, the average value of vehicles insured here is much higher, which can offset the "safe neighborhood" discount.
- 85262 and 85266 (Far North/Troon): These areas often see the lowest frequency of claims but may face higher "Comprehensive" costs due to wildlife (javelinas, coyotes) and brush fire risks, which can impact vehicle safety when parked in carports or open driveways.
How to Lower Your Insurance Costs in Scottsdale
Despite the upward pressure on rates in 2026, there are several strategic ways for Scottsdale drivers to reduce their overhead without sacrificing essential protection.
Telematics and Usage-Based Insurance (UBI)
Most major carriers in Arizona, such as State Farm (Drive Safe & Save) and Progressive (Snapshot), now offer deep discounts for drivers willing to install a tracking app or device. In a city like Scottsdale, where many residents are retired or work from home, a "Low Mileage" discount combined with safe driving data can result in savings of 20% to 30%. If you rarely drive during the peak congestion hours on the 101, telematics is highly recommended.
Strategic Deductible Adjustments
Increasing your deductible from $500 to $1,000 can reduce your comprehensive and collision premiums by as much as 15%. For many Scottsdale residents with sufficient emergency savings, "self-insuring" for small repairs makes more sense than paying a higher monthly premium to have a low deductible.
Bundling and Loyalty Multipliers
Bundling your auto insurance with a high-value homeowners policy (common in Scottsdale's expensive real estate market) remains the single most effective way to trigger a "multi-policy" discount. In 2026, insurers are increasingly aggressive with these discounts to prevent high-net-worth clients from shopping around.
Common Mistakes to Avoid
When shopping for insurance in Scottsdale, avoiding these technical pitfalls can save you thousands in the long run:
- Ignoring "Agreed Value" for High-End Cars: If you drive a classic or a highly customized luxury car, a standard "Actual Cash Value" (ACV) policy will not compensate you fairly in the event of a total loss. Seek out "Agreed Value" coverage through specialty carriers.
- Skipping Glass Coverage: Arizona law (A.R.S. § 20-264) requires insurers to offer a $0 deductible for safety glass. In a desert environment where rocks are frequently kicked up on the freeway, this is an essential add-on. Replacing a windshield on a modern vehicle with a "Heads-Up Display" (HUD) can cost over $2,000 in 2026.
- Underestimating Liability in a Litigious Environment: Scottsdale is home to many successful professionals and business owners. If you are at fault in an accident, your future earnings and assets are at risk. A "100/300/100" policy should be considered the bare minimum, with many residents opting for a $1M or $2M Umbrella policy for added protection.
Comparing Top Carriers in Scottsdale
| Insurance Company | Best Known For | 2026 Market Position |
|---|---|---|
| State Farm | Local Agent Network | Currently the largest insurer in AZ; strong bundling with home insurance. |
| Geico | Competitive Pricing | Often the lowest rates for drivers with clean records and good credit. |
| Progressive | Telematics/Tech | Excellent for drivers who want to use the "Snapshot" program to lower rates. |
| Chubb / Cincinnati | High-Net-Worth | The go-to for Scottsdale residents with exotic car collections or estates. |
| USAA | Military/Veterans | Consistently the highest customer satisfaction for Scottsdale’s veteran population. |
Frequently Asked Questions
Why is glass coverage so important in Scottsdale?
In Scottsdale, the combination of desert construction, frequent roadwork, and high-speed freeway travel leads to a high frequency of chipped or cracked windshields. Because modern vehicles use the windshield as a mounting point for cameras and sensors (Lane Departure Warning, etc.), a simple crack can disable your car’s safety features. Arizona’s specific "Full Glass" coverage ensures these are replaced with zero out-of-pocket costs and no impact on your deductible.
Does my credit score really affect my auto insurance rate in Arizona?
Yes. Arizona allows insurance companies to use a credit-based insurance score as one of the primary factors in determining your premium. Statistically, insurers have found a correlation between credit management and driving risk. In Scottsdale, maintaining a high credit score is one of the most effective ways to keep insurance costs low.
How does "Snowbird" season affect my rates?
While your individual rate doesn't change month-to-month, the overall "rate environment" in Scottsdale is influenced by the increased accident frequency during the winter months when the population swells. If you are a seasonal resident, you may be able to put your vehicle on a "storage" or "non-operational" policy while you are away, which significantly reduces costs.
What happens if I drive an Electric Vehicle (EV) in Scottsdale?
In 2026, EV insurance premiums in Scottsdale are roughly 15% to 25% higher than equivalent internal combustion engine (ICE) vehicles. This is due to the high cost of battery replacement and the specialized labor required for repairs. However, many insurers offer "Green Vehicle" discounts that can partially offset these higher base rates.
Is Scottsdale more expensive for insurance than Phoenix?
Generally, yes. While Phoenix has higher rates of vehicle theft in certain sectors, Scottsdale’s higher average "cost per claim" (due to more expensive vehicles and higher medical billing rates) often results in a higher average premium for the typical resident.
Final Recommendations for Scottsdale Residents
To secure the most cost-effective auto insurance in Scottsdale for 2026, you should first audit your current liability limits. Ensure you have at least 100/300/100 coverage to protect your assets against the high-value vehicles common in the area. Second, verify that you have the $0 Deductible Glass endorsement; it is almost guaranteed to pay for itself within two years of driving on the Loop 101.
Finally, if you have lived in the same zip code for more than three years, it is time to re-shop your policy. The Scottsdale market is highly competitive, and new actuarial models in 2026 may favor your specific demographic more than they did in previous years. Always compare a national carrier (like Geico or State Farm) against a specialized broker if you own high-value property or luxury vehicles.
Image Gallery
Select an image to open it in a new tab.


Simon Caldwell
Enterprise Technology and Systems Editor
