The Apple Card is an excellent choice for a first credit card due to its transparent fee structure, intuitive financial health tools, and a unique application process that allows you to see your approved credit limit and interest rate before a hard inquiry affects your credit score. By prioritizing user education and simplicity, it serves as a powerful entry point for building a solid credit foundation within the Apple ecosystem.
Introduction to the Apple Card Ecosystem
In 2026, the landscape of consumer finance has shifted toward hyper-transparency and mobile-first integration. For individuals looking to establish credit for the first time, the transition from a debit-only lifestyle to a credit-based one can be fraught with hidden traps, such as annual fees, confusing interest calculations, and punitive late penalties. The Apple Card, issued by Goldman Sachs, remains a standout in this space by stripping away the traditional complexities of banking.
Unlike traditional "starter cards" that often come with high fees or low utility, the Apple Card provides a premium experience regardless of the user's credit history. It is designed to live primarily in the iPhone’s Wallet app, leveraging hardware and software integration to provide a level of security and spending insight that few other issuers can match. For a beginner, this integration is not just a matter of convenience; it is a pedagogical tool that teaches responsible spending in real-time.
The Unique Application Process: Protecting Your Credit Score
One of the most significant barriers for first-time credit seekers is the "hard pull" or hard inquiry. Most credit card issuers require you to submit a full application that immediately impacts your credit score, regardless of whether you are approved or denied. For someone with a "thin" credit file or no credit history at all, multiple denials can lead to a downward spiral in creditworthiness before they even begin.
The Apple Card utilizes a "soft pull" for the initial application. This means you can apply, and Apple (through its banking partner) will determine your eligibility, credit limit, and APR without impacting your credit score. You only face a hard inquiry once you choose to accept the offer and open the account. This feature is particularly valuable for beginners who may be unsure of where they stand in the eyes of lenders.
The "Path to Apple Card" Program
If an applicant is denied, Apple does not simply close the door. They often offer a program called "Path to Apple Card." This is a personalized, multi-month program that identifies the specific reasons for denial—such as high debt-to-income ratios or insufficient payment history—and provides a roadmap to improvement. By following the suggested steps, such as making timely payments on other obligations or reducing existing debt, users are often invited to reapply with a high probability of success. This makes it one of the most inclusive "first" cards on the market.
A Fee-Free Philosophy
For those new to credit, the most dangerous aspect of a credit card is the hidden cost of a mistake. Most starter cards generate significant revenue through "gotcha" fees. The Apple Card is fundamentally different because it charges:
- No Annual Fees: You do not pay just to have the card in your wallet.
- No Late Fees: While interest will still accrue on late balances, you aren't hit with a $40 penalty for being a day late.
- No Foreign Transaction Fees: Ideal for students studying abroad or young travelers.
- No Over-the-Limit Fees: The card simply declines if you exceed your limit, preventing accidental debt spirals.
By removing these fees, the Apple Card creates a "sandbox" environment where the only real cost is the interest on the balance you choose to carry. This simplicity allows a first-time user to focus entirely on the mechanics of borrowing and repayment.
Understanding the Rewards: Daily Cash
Traditional credit cards often make rewards points difficult to understand and even harder to redeem. You might have to wait until the end of a billing cycle or reach a certain threshold before you can use your "points."
The Apple Card uses a system called Daily Cash. When you make a purchase, the percentage of cash back is calculated and deposited into your Apple Cash account (or a high-yield Savings account if you've opted in) as soon as the transaction clears—usually within 24 to 48 hours.
The Reward Tiers
- 3% Daily Cash: On all purchases made directly with Apple (including the App Store, Apple Music, and hardware) and select merchants like Nike, T-Mobile, and ExxonMobil.
- 2% Daily Cash: On every purchase made using Apple Pay via your iPhone or Apple Watch.
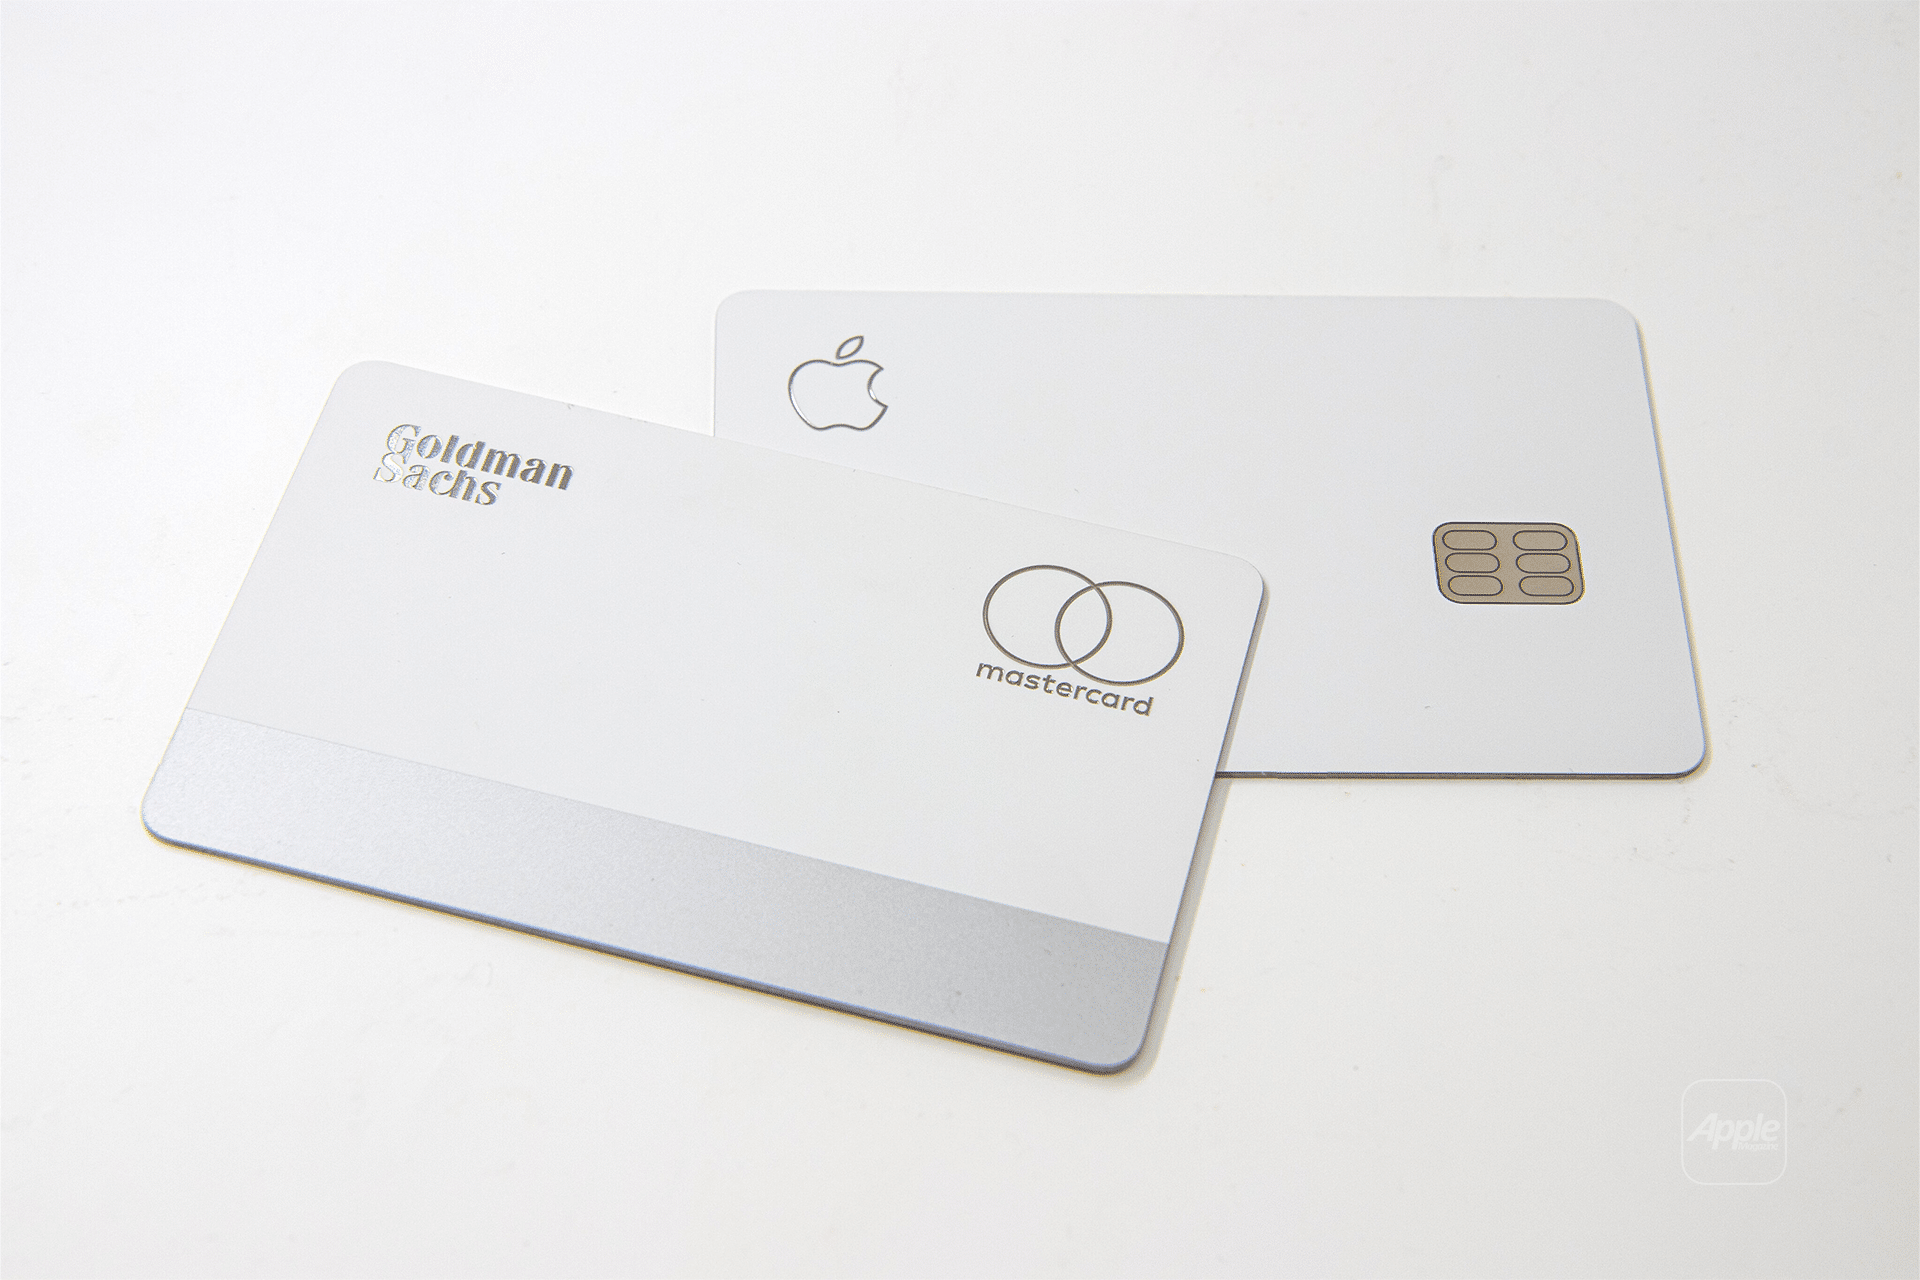
- 1% Daily Cash: On purchases made with the physical titanium card or when using the virtual card number online where Apple Pay is not accepted.
For a first-time cardholder, the 2% tier is the most relevant. Since Apple Pay is accepted at the vast majority of retailers in 2026, most users can effectively earn 2% back on almost everything they buy, which is significantly higher than the 1% or 1.5% offered by most entry-level competitors.
Financial Literacy Through Design
The Wallet app serves as a real-time financial advisor. Rather than receiving a static PDF statement at the end of the month, Apple Card users see a color-coded breakdown of their spending. If you spend heavily on "Food & Drink," those transactions appear orange; "Entertainment" might be pink. This visual feedback helps beginners realize where their money is going without needing to export data to a third-party budgeting app.
The Interest Estimator
Perhaps the most powerful feature for a beginner is the interest estimator. When you go to make a payment, the Wallet app provides a circular slider. As you move the slider to different payment amounts, the app calculates in real-time exactly how much interest you will owe the following month.
This transparency demystifies how credit card interest works. It explicitly shows the user that paying even $20 more than the minimum can significantly reduce the long-term cost of their purchase. By making the "cost of debt" visible, Apple encourages users to pay their balance in full, a habit that is essential for long-term financial health.
Security and Privacy Specifications
As a first credit card, the Apple Card provides a masterclass in modern security. The physical card, made of laser-etched titanium, is notable for what it doesn't have. There is no credit card number, no CVV code, and no expiration date printed on the card. This prevents "over-the-shoulder" theft at restaurants or retail stores.
All of that sensitive information is stored securely in the Wallet app, protected by FaceID or TouchID. If you need to make an online purchase where Apple Pay isn't available, you can generate a virtual card number. If you suspect that number has been compromised, you can reset it instantly with the tap of a button, without needing to wait for a new physical card to arrive in the mail.
Comparing the Apple Card to Other Starter Options
To understand why the Apple Card is superior for many, it is helpful to see how it stacks up against other popular "first" cards like the Discover it® Student Cash Back or the Capital One Platinum.
| Feature | Apple Card | Discover it® Student | Capital One Platinum |
|---|---|---|---|
| Annual Fee | $0 | $0 | $0 |
| Late Fees | $0 | Up to $41 (waived first time) | Up to $40 |
| Rewards | 1%–3% Daily Cash | 1%–5% Cashback | None |
| Foreign Fees | None | None | None |
| Application | Soft pull to see offer | Hard pull | Hard pull |
| UI/UX | Integrated Apple Wallet | Discover Mobile App | Capital One App |
| Physical Card | Titanium (No numbers) | Plastic | Plastic |
While the Discover it® Student card offers high rewards in rotating categories, the Apple Card's consistent 2% on Apple Pay and the lack of any late fees make it a more forgiving and predictable tool for a true beginner.
Limitations to Consider
Despite its strengths, the Apple Card is not perfect for everyone. It is essentially a "locked-in" product. You must own an iPhone to apply for and manage the card effectively. If you switch to an Android device, you lose the ability to manage your account easily, see your spending insights, or use the 2% Apple Pay tier.
Furthermore, because the highest rewards are tied to Apple Pay, the card is less effective for users who live in areas where contactless payment is not yet standard. If you are forced to use the physical titanium card frequently, you are only earning 1% cash back, which is suboptimal compared to "flat-rate" cards that offer 1.5% or 2% on all physical swipes.
Building a Credit History
For a first cardholder, the ultimate goal is building a credit score. The Apple Card reports to the major credit bureaus (TransUnion and Experian), meaning your responsible use will help you qualify for future loans, such as an auto loan or a mortgage. Because Apple makes it so easy to track your balance and set up automated payments, it significantly reduces the risk of the "missed payment" trap that often haunts first-time users.
Frequently Asked Questions
Does the Apple Card help build credit?
Yes. Apple reports your payment history and credit utilization to the major credit bureaus. By making on-time payments and keeping your balance low relative to your limit, you will see a positive impact on your credit score over time.
Can I get an Apple Card with no credit history?
While the Apple Card generally requires a credit score in the "fair" to "good" range (typically 600-660+), many users with thin files are approved. If denied, the "Path to Apple Card" program is specifically designed to help those with no history or poor history get approved within a few months.
What happens if I lose the physical titanium card?
Because there are no numbers on the card, the risk of someone using it for online purchases is zero. You can instantly "freeze" the card in your Wallet app. Ordering a replacement is free and can be done with a few taps; your virtual card and Apple Pay will continue to work even while you wait for the new physical card to arrive.
How does the 2026 interest rate compare to other cards?
Credit card APRs are generally tied to the federal prime rate. In 2026, Apple Card APRs remain competitive with other rewards cards, ranging from approximately 19% to 29% based on creditworthiness. However, Apple's transparent UI makes it much easier to avoid paying that interest entirely by showing you exactly how to pay your balance in full.
Is the Daily Cash real money?
Yes. Daily Cash is real currency deposited into your Apple Cash account. You can use it to pay for things via Apple Pay, send it to friends via iMessage, pay your credit card bill, or transfer it directly to a linked bank account.
Final Recommendation: Should You Start Here?
The Apple Card is arguably the most user-friendly financial product on the market in 2026 for those starting their credit journey. Its "soft pull" application process removes the fear of rejection, and its fee-free structure removes the fear of the unknown. If you are an iPhone user who wants a transparent, secure, and educational way to build credit, the Apple Card should be at the top of your list.
Next Action: Open the Wallet app on your iPhone, tap the "+" icon, and select "Apply for Apple Card." You can review your offer in minutes without any commitment or impact on your credit score.
Image Gallery
Select an image to open it in a new tab.




Akira Tanaka
International Academic Trends Correspondent
