What Kind of Life Insurance Can You Borrow Against? A Complete Guide to Policy Loans
You can borrow against permanent life insurance policies that accumulate cash value, including whole life, universal life, indexed universal life (IUL), and variable life insurance. Term life insurance policies do not build cash value and therefore do not offer borrowing capabilities. Policy loans allow you to access your equity tax-free while the policy remains in force.
Understanding the "Cash Value" Requirement
To understand what kind of life insurance you can borrow against, you must first distinguish between the two primary categories of life insurance: term and permanent. Borrowing is exclusively a feature of permanent policies because they include a savings component known as cash value.
When you pay a premium for a permanent policy, a portion goes toward the cost of insurance (the death benefit) and administrative fees, while the remainder is deposited into a cash value account. Over time, this account grows through interest, dividends, or investment gains. As of 2026, the internal revenue codes governing these products remain consistent in treating the cash value as a private asset of the policyholder, which can be used as collateral for a loan from the insurance company.
Term life insurance, by contrast, is "pure" insurance. It provides a death benefit for a specific period (e.g., 10, 20, or 30 years). Because term insurance is designed to be affordable and temporary, it does not build equity. If you stop paying the premium or the term ends, the coverage simply ceases with no residual value. Consequently, there is no "bucket" of money from which to borrow.
The Specific Types of Borrowable Life Insurance
While the general answer is "permanent life insurance," the specific mechanics of how you borrow—and how much you can borrow—vary significantly depending on the product type.
1. Whole Life Insurance
Whole life is the most traditional form of permanent insurance. It offers a guaranteed death benefit, fixed premiums, and a guaranteed rate of return on the cash value.
In a whole life policy, the cash value grows according to a schedule set by the insurer. If the policy is "participating" (usually offered by mutual insurance companies), you may also receive dividends. You can typically borrow up to 90% or 95% of the total cash value.
One technical nuance in whole life borrowing is the distinction between direct recognition and non-direct recognition companies.
- Non-direct recognition: The insurer continues to pay the same dividend rate on your full cash value, even the portion you have borrowed. This can create "favorable arbitrage" if your dividend rate is higher than your loan interest rate.
- Direct recognition: The insurer reduces the dividend rate on the portion of the cash value you have borrowed. This makes the loan slightly more expensive in the long run.
2. Universal Life Insurance (UL)
Universal life insurance offers more flexibility than whole life. You can adjust your premium payments and death benefit amounts within certain limits. The cash value in a standard UL policy grows based on current market interest rates, subject to a minimum guaranteed rate.
Borrowing from a UL policy is straightforward, but because the premiums are flexible, you must be careful. If you take a large loan and stop paying sufficient premiums, the combination of interest charges and the cost of insurance could deplete the remaining cash value, causing the policy to lapse in the current 2026 economic environment.
3. Indexed Universal Life Insurance (IUL)
IUL policies are popular because they link cash value growth to the performance of a market index, such as the S&P 500, while providing a "floor" (usually 0%) to protect against market losses.
When borrowing from an IUL, many companies offer indexed loans (also called participating loans). In this scenario, the money you "borrow" stays invested in the index. If the index performs well (e.g., 8%) and your loan interest rate is fixed (e.g., 5%), you actually earn a 3% profit on the money you borrowed. However, if the index stays flat, you still owe the 5% interest, which can lead to a faster depletion of equity.
4. Variable Life and Variable Universal Life (VUL)
Variable policies allow you to invest your cash value in "sub-accounts," which function similarly to mutual funds. These offer the highest growth potential but also the highest risk, as the cash value can actually decrease if the underlying investments perform poorly.
Borrowing from a VUL is more complex because the available loan amount fluctuates with the market. Most insurers require a "buffer" to ensure that a market downturn doesn't immediately put the loan underwater. According to guidelines from the Financial Industry Regulatory Authority (FINRA), investors should be aware that market volatility can significantly impact the sustainability of loans against variable products.

How the Borrowing Process Works
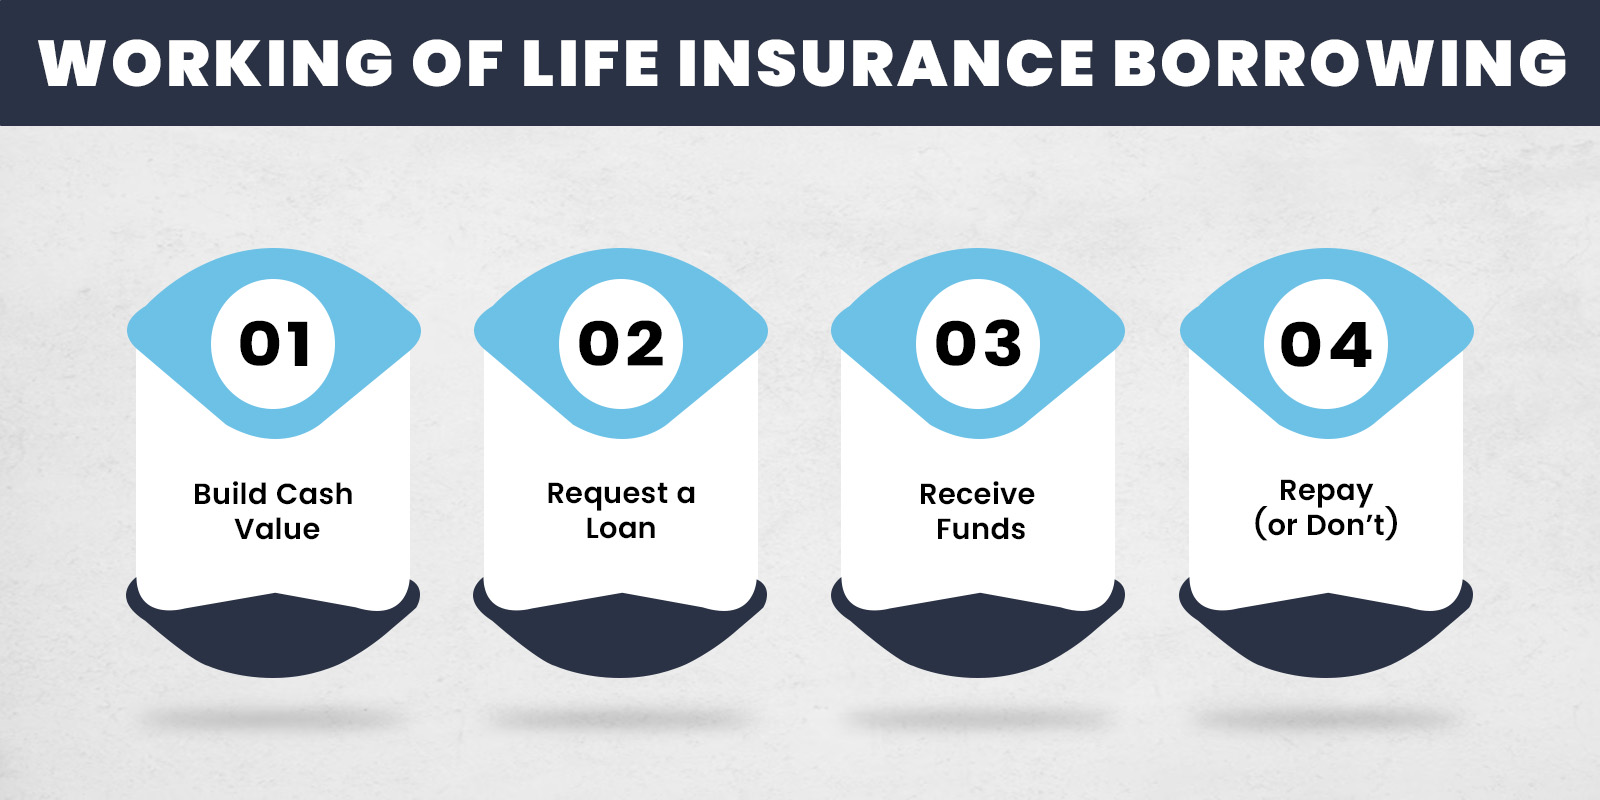
Taking a loan against your life insurance is not like applying for a bank loan. It is technically a collateralized loan where the insurance company uses your cash value as security. You are not "withdrawing" the money (which would be a taxable event if it exceeded your basis); you are borrowing the insurer's money and using your policy's value as a guarantee.
No Credit Checks or Applications
Because the loan is fully collateralized by your own policy, there is no credit check, no income verification, and no lengthy approval process. In 2026, most major carriers allow you to initiate a loan through an online portal or mobile app, with funds typically arriving via ACH transfer within three to five business days.
Interest Rates
The insurance company charges interest on the loan. These rates can be fixed or variable. Even though you are borrowing "your own money" in a sense, the insurer is losing the opportunity to invest that cash elsewhere, so they charge interest to compensate for that loss. In 2026, typical policy loan rates range from 4% to 8%, depending on the policy type and the current federal funds rate environment.
Repayment Flexibility
One of the most unique features of a life insurance loan is that there is no mandatory repayment schedule. You can pay back the principal and interest monthly, annually, or not at all. However, interest will continue to accrue and will be added to the loan balance if not paid.
| Feature | Whole Life | Universal Life | Indexed Universal Life (IUL) | Variable Life (VUL) |
|---|---|---|---|---|
| Growth Mechanism | Guaranteed Rate + Dividends | Current Interest Rates | Market Index (e.g., S&P 500) | Investment Sub-accounts |
| Loan Type | Fixed or Variable | Usually Variable | Fixed, Variable, or Indexed | Variable |
| Borrowing Limit | Up to 95% of Cash Value | Up to 90% of Cash Value | Up to 90% of Cash Value | Variable (due to market risk) |
| Risk Level | Low | Moderate | Moderate-High | High |
| Credit Check | None | None | None | None |
The Dangers of Policy Loans: Lapse and Taxes
While borrowing against life insurance is a powerful financial tool, it carries significant risks that can result in a massive tax bill if handled incorrectly.
The Risk of Policy Lapse
If the total loan balance (principal plus accrued interest) exceeds the total cash value of the policy, the policy will lapse. This means the life insurance coverage ends, and the death benefit is cancelled.
The consequences of a lapse are not just the loss of coverage. If a policy lapses while a loan is outstanding, the IRS treats the unpaid loan as a "distribution." You will be taxed at ordinary income rates on any amount that exceeds the "basis" (the total amount of premiums you paid into the policy). For long-standing policies, this can result in a tax liability of tens of thousands of dollars.
Impact on the Death Benefit
Any outstanding loan balance at the time of the insured's death is deducted from the death benefit paid to the beneficiaries. For example, if you have a $500,000 policy and an outstanding loan of $100,000, your beneficiaries will only receive $400,000. This is a critical consideration if the primary purpose of the policy is to provide for a family's financial security.
Tax Considerations: The MEC Rule
When borrowing from life insurance, you must ensure the policy is not classified as a Modified Endowment Contract (MEC). The IRS created the MEC classification to prevent people from using life insurance as a pure tax-sheltered investment vehicle rather than for actual insurance protection.
A policy becomes a MEC if the premiums paid into it exceed federal limits (the "7-pay test") during the first seven years. If your policy is a MEC:
- Loans are taxed as income to the extent there is gain in the policy (Last-In, First-Out or LIFO accounting).
- A 10% federal tax penalty may apply if you take a loan before age 59½.
Before taking a loan, always verify with your insurer that the policy is not a MEC. Most modern insurance contracts include "MEC-avoidance" riders or alerts to prevent accidental overfunding. You can find more details on these classifications through the IRS Taxable and Nontaxable Income guidelines.
Comparing Policy Loans to Other Credit Sources
In 2026, life insurance loans remain a competitive alternative to traditional financing, especially for those with significant equity in their policies.
Life Insurance Loan vs. Home Equity Line of Credit (HELOC)
A HELOC requires a home appraisal, a credit check, and income verification. It also puts your home at risk if you fail to make payments. A life insurance loan requires none of these. However, HELOC interest might be tax-deductible if used for home improvements, whereas life insurance loan interest is generally not deductible for personal use.
Life Insurance Loan vs. 401(k) Loan
A 401(k) loan is capped at $50,000 or 50% of your vested balance, whichever is less. Furthermore, if you leave your job, the 401(k) loan usually must be paid back immediately or it becomes a taxable distribution. Life insurance loans are not tied to employment and often allow for higher borrowing limits if the cash value is large enough.
Practical Steps to Borrow Against Your Policy
If you have determined that you have the right kind of life insurance and wish to proceed with a loan, follow these steps:
- Request an Illustration: Ask your insurance agent or the carrier for an "in-force illustration" that shows how a loan will impact your cash value and death benefit over the next 10–20 years.
- Verify the Available Loan Value: The "cash surrender value" is the amount you would get if you cancelled the policy. The "available loan value" is usually slightly less, as the insurer keeps a small buffer for interest.
- Choose Your Interest Option: If your policy allows a choice between fixed and variable interest, evaluate the current 2026 interest rate trends. Fixed rates provide certainty, while variable rates may be lower initially.
- Submit the Request: This can usually be done via a simple one-page form or an online portal.
- Develop a Repayment Plan: Even though the insurer doesn't require it, you should have a plan to pay back at least the interest annually to prevent the loan from compounding and risking a policy lapse.
Frequently Asked Questions
Can I borrow from a term life insurance policy?
No. Term life insurance has no cash value component. It is a "pure" insurance product where the premiums only pay for the death benefit for a specific period. If you need to borrow money and only have term insurance, you may need to look into other options like personal loans or credit lines.
Do I have to pay back a life insurance loan?
Technically, no. You are not required to make monthly payments. However, the interest will continue to accrue. If the loan plus interest exceeds the policy's cash value, the policy will lapse, potentially creating a large tax bill. Additionally, any unpaid loan will be subtracted from the death benefit when you die.
Is the money I borrow from life insurance taxable?
In most cases, no. Policy loans are generally treated as non-taxable debt, provided the policy is not a Modified Endowment Contract (MEC) and the policy remains in force. If the policy lapses or is surrendered while a loan is outstanding, the portion of the loan that represents "gain" in the policy becomes taxable as ordinary income.
How soon can I borrow against a new policy?
Most permanent policies require at least one to three years of premium payments before enough cash value has accumulated to allow for a loan. Some "high early cash value" policies designed for business or infinite banking purposes allow borrowing within the first 30 to 90 days, though these typically require much higher initial premiums.
What happens if the insured person dies with an outstanding loan?
The insurance company will pay the death benefit to the beneficiaries, minus the outstanding loan balance and any accrued interest. For example, a $1,000,000 death benefit with a $200,000 loan will result in a $800,000 payout to the heirs.
Summary and Recommendations
Borrowing against your life insurance is a versatile financial strategy, provided you have a permanent policy such as whole life or universal life. It offers unparalleled privacy, speed, and flexibility compared to traditional bank loans.
However, it is not "free money." The interest costs are real, and the risk of policy lapse can lead to unforeseen tax consequences and the loss of valuable insurance coverage. For 2026 policyholders, the best approach is to treat a policy loan with the same discipline as a bank loan: borrow only what is necessary, understand the interest mechanics, and have a clear plan for repayment to protect your long-term financial legacy.
Before taking a loan, consult with a qualified financial advisor to review your policy's current status and ensure that the loan aligns with your overall estate and tax planning goals. You may also wish to review the National Association of Insurance Commissioners (NAIC) resources for consumer protections regarding policy loans and disclosures.
Image Gallery
Select an image to open it in a new tab.
Lars Thomsen
Global Labor Markets and Economic Strategy Editor
