
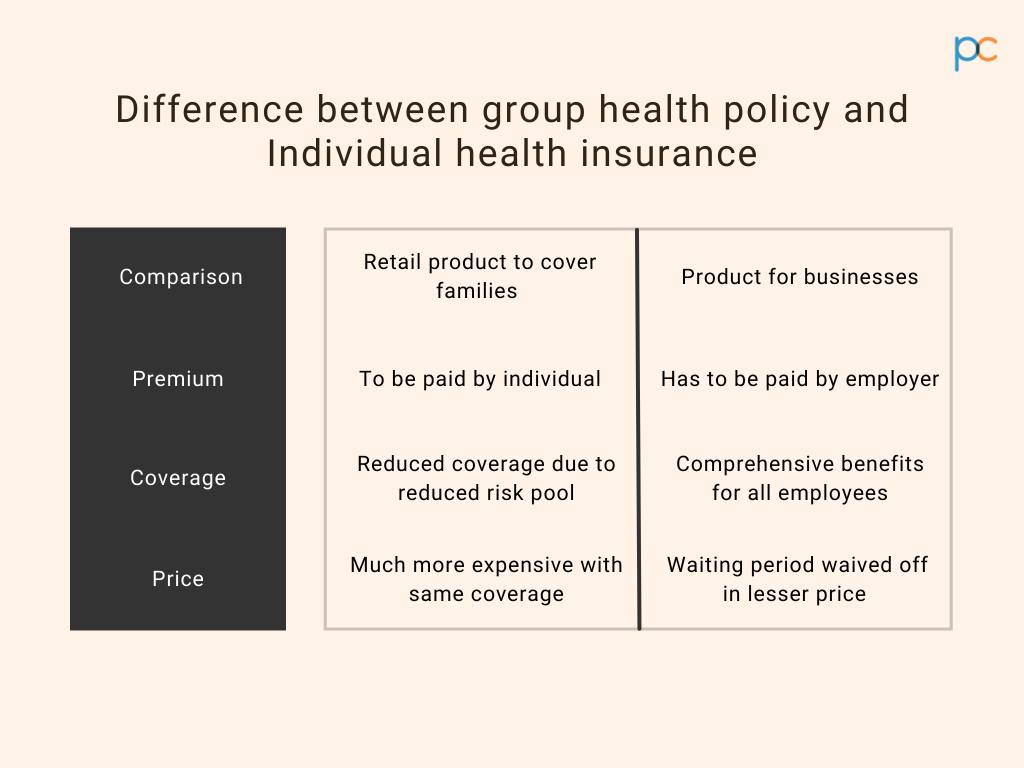
Employer group health insurance for workers serves as a fundamental benefit, providing coverage to employees and their dependents through a plan purchased by a company. These plans are designed to spread risk across a larger group, typically resulting in lower premiums compared to individual market policies while ensuring that workers have consistent access to medical services, preventative care, and financial protection against high healthcare costs.
Understanding the Structure of Group Health Insurance
Group health insurance operates on the principle of risk pooling. By covering a collection of individuals—the employees of a specific organization—the insurer assesses the risk of the entire group rather than the individual health history of every worker. This structure often allows for more stable pricing and richer benefit designs. In 2026, most employer-sponsored plans are classified as either Fully Insured or Self-Funded, and the distinction significantly impacts how the employer manages the plan and how the employees interact with it.
In a Fully Insured model, the employer pays a set premium to an insurance carrier. The carrier assumes the financial risk of paying for the employees' medical claims. This is the most common arrangement for small to mid-sized businesses, as it offers predictable costs for the employer and simplicity for the worker.
In a Self-Funded (or Self-Insured) model, the employer essentially acts as the insurer. They pay for claims as they arise, typically using a third-party administrator (TPA) to manage the network and process paperwork. While this offers greater flexibility in plan design, it carries higher financial risk for the employer, often mitigated by purchasing "stop-loss" insurance to cover catastrophic claims.
Eligibility and Enrollment Prerequisites
Accessing employer group health insurance is generally tied to employment status. Under the standards governing benefit plans in 2026, employers establish "eligibility rules" that typically define who qualifies as a full-time employee.
- Employment Status: Most plans require workers to be classified as full-time. While the specific number of hours can vary by company policy, federal benchmarks often use 30 hours per week as the threshold for an "applicable large employer" to offer coverage under the Affordable Care Act.
- Waiting Periods: Employers may implement a waiting period before a new hire becomes eligible for benefits. By law, this period generally cannot exceed 90 days.
- Open Enrollment: For employees who do not sign up during their initial hiring window, the annual Open Enrollment period is the primary opportunity to join the plan. Outside of this window, enrollment is typically only permitted if the employee experiences a "Qualifying Life Event" (QLE), such as marriage, the birth of a child, or the loss of other health coverage.
Key Components of Coverage
When evaluating an employer plan, workers must look beyond the premium cost. The real value of a plan is often found in the interaction between premiums, deductibles, copayments, and coinsurance.
- Premium: The fixed amount deducted from an employee's paycheck to maintain coverage.
- Deductible: The amount an employee must pay out-of-pocket for covered services before the insurance plan begins to pay its share.
- Copayment (Copay): A fixed dollar amount paid for specific services, such as $30 for a primary care visit.
- Coinsurance: The percentage of costs an employee pays after the deductible is met (e.g., 20% of a procedure’s cost).
- Out-of-Pocket Maximum: The absolute limit on what an employee will pay in a given plan year. Once this limit is reached, the insurance carrier pays 100% of covered in-network costs.
Comparing Common Plan Types
Employees often face a choice between different network structures. Understanding how these networks restrict or allow access to providers is critical for managing costs.
| Plan Type | Network Flexibility | Referral Requirements | Cost Characteristics |
|---|---|---|---|
| HMO | Limited to in-network providers | Required to see specialists | Lower premiums, lower out-of-pocket |
| PPO | In-network and out-of-network | Not required | Higher premiums, more freedom |
| EPO | In-network only | Not required | Moderate premiums and flexibility |
| HDHP | Varies by network | Varies | Lowest premiums; high deductible |
High Deductible Health Plans (HDHPs) are increasingly common in 2026 because they can be paired with a Health Savings Account (HSA). An HSA allows employees to set aside pre-tax dollars to cover qualified medical expenses, providing a tax-advantaged way to save for both current and future healthcare needs.
Navigating Claims and Coverage Denials
Even with robust coverage, employees may occasionally encounter issues with claim processing or denied services. The first step in addressing a denied claim is to review the Explanation of Benefits (EOB) sent by the insurance provider. The EOB explains exactly why a claim was denied—for example, if a service was coded incorrectly, or if the provider was out-of-network.
If the denial is based on medical necessity or coverage exclusions, the worker has the right to an internal appeal. The employer’s Human Resources (HR) department or the benefits administrator can provide the specific steps for filing an appeal, which involves submitting additional medical records or a letter of support from the treating physician. If the internal appeal is denied, most plans provide the right to an external review by an independent third party.
Practical Steps for Choosing the Right Plan
Choosing the right health insurance requires a balance of financial risk tolerance and medical needs. Employees should assess their history of healthcare utilization:
- High Utilization: If you or your dependents require regular prescriptions or frequent specialist visits, a plan with a higher premium but lower deductible (like an HMO or a mid-tier PPO) often results in lower overall annual costs.
- Low Utilization: If you are generally healthy and rarely see a doctor, an HDHP may save you money through lower monthly payroll deductions, provided you have enough in savings to cover the deductible should an emergency arise.
- Provider Networks: Always verify that your preferred primary care physician, specialists, and hospitals are "in-network." Using out-of-network providers can result in significantly higher costs or no coverage at all, depending on the plan design.
Common Pitfalls and Troubleshooting
One of the most common mistakes employees make is failing to update their information or missing deadlines for qualifying life events. If you experience a change in status—such as getting married or moving to a different state—you typically have a 30-day window to report this change to your HR department. Failing to do so may prevent you from adding or removing dependents until the next Open Enrollment period.
Another issue involves "balance billing." This occurs when a provider bills the patient for the difference between what the insurance paid and the provider’s standard rate. Under current regulations like the No Surprises Act, balance billing for emergency services and certain non-emergency services provided at in-network facilities is strictly restricted. If you receive a surprise bill, contact your insurance carrier's member services department immediately to verify if the charge complies with these protections.
Frequently Asked Questions
Can I keep my employer-sponsored insurance if I quit my job? Under the Consolidated Omnibus Budget Reconciliation Act (COBRA), you may be able to continue your group coverage for a limited time after leaving a job. However, you will likely be responsible for the full premium, including the portion the employer previously paid, plus an administrative fee.
Is employer health insurance mandatory for employees? In most cases, enrollment in employer-sponsored health insurance is voluntary. However, if you choose not to enroll, you may be ineligible for certain tax credits that are available when purchasing coverage on the individual marketplace (the ACA Exchange).
How do I know if a procedure is covered? You should review the Summary of Benefits and Coverage (SBC) document provided by your plan. This standardized document outlines covered services, exclusions, and cost-sharing requirements. You can also call the member services number on the back of your insurance ID card to verify coverage for a specific procedure.
What happens to my HSA funds if I leave my employer? Unlike a Flexible Spending Account (FSA), which is often "use it or lose it," an HSA is owned by the individual. If you leave your employer, you keep your HSA account and the funds within it. You can continue to use those funds for qualified medical expenses regardless of your new employment status.
Does my employer see my medical records? No. Under the Health Insurance Portability and Accountability Act (HIPAA), your employer does not have access to your private medical records or the specific details of your health visits. They only receive aggregate data regarding the plan's overall usage to help manage costs and negotiate future premiums.
Moving Forward
Evaluating your employer group health insurance is an annual responsibility that directly impacts your financial well-being and health outcomes. As you head into the next plan year, prioritize reviewing your SBC, mapping out your anticipated healthcare needs, and ensuring your preferred providers remain in-network. If you find your current plan is not meeting your requirements, utilize your HR benefits portal during the next enrollment window to compare available options and secure the coverage that best aligns with your life.
Image Gallery
Select an image to open it in a new tab.



Lars Thomsen
Global Labor Markets and Economic Strategy Editor
