
Securing the right auto insurance in Southcrest goes beyond meeting California’s legal minimums; it is a critical financial strategy to protect against high litigation costs, rising vehicle repair prices in 2026, and specific neighborhood risks like street-parking theft and heavy commuter traffic. Comprehensive coverage ensures that an accident or theft does not lead to personal insolvency or the loss of essential transportation.
While many drivers in Southcrest, San Diego, view insurance as a monthly "tax" required by the DMV, the reality of the 2026 economic landscape suggests otherwise. Southcrest is a vibrant, residential neighborhood situated near major transit arteries like Interstate 5 and State Route 15. This proximity brings convenience but also increases the statistical likelihood of collisions. Furthermore, with the average cost of a new vehicle now exceeding $50,000 and medical inflation continuing to climb, the "minimum" coverage required by the state is often insufficient to cover even a moderate multi-car accident.
Understanding the Southcrest Driving Environment
Southcrest occupies a unique geographic position in Southeastern San Diego. It is a community characterized by dense residential blocks, schools like Cesar Chavez Elementary, and proximity to the Chollas Creek. These factors contribute to a specific risk profile for local drivers.
High Traffic Density and Commuter Risks
Because Southcrest is bordered by major freeways, residents often navigate high-traffic transitions. The "stop-and-go" nature of commuting to Downtown San Diego or National City increases the frequency of rear-end collisions. While these are often lower-speed accidents, the complexity of modern vehicle sensors and ADAS (Advanced Driver Assistance Systems) means that even a minor bumper tapping can result in thousands of dollars in repair costs. In 2026, a single damaged radar sensor can cost more than the property damage limit of a basic "minimum-limit" policy.
Street Parking and Property Risks
Many homes in Southcrest utilize street parking. This exposes vehicles to a higher risk of hit-and-runs, sideswiping, and "non-collision" incidents such as theft or vandalism. Without the "right" coverage—specifically Comprehensive and Uninsured Motorist Property Damage—a resident whose car is damaged overnight by an unknown driver would have to pay for the entire repair out of pocket.
The Gap Between Legal Minimums and Financial Reality
In California, the mandatory minimum liability limits have historically been $15,000 for injury to one person, $30,000 for injury to all persons in one accident, and $5,000 for property damage (often referred to as 15/30/5). In 2026, these figures are dangerously outdated.
The $5,000 Property Damage Trap
If you are at fault in an accident involving a newer vehicle in Southcrest, the repairs will almost certainly exceed $5,000. If you hit a luxury vehicle or a common electric SUV, you could easily be looking at $20,000 to $40,000 in damage. If your policy only covers $5,000, the other driver’s insurance company will pursue you personally for the remaining balance. This can lead to wage garnishment, bank account levies, and the forced sale of assets.
Medical Cost Inflation
Medical expenses in 2026 have outpaced general inflation. A single emergency room visit following a collision on 38th Street can exceed $15,000 before any specialized imaging or physical therapy is considered. Relying on a $15,000 per-person limit leaves you exposed to personal lawsuits from injured parties seeking to recover their full medical costs and lost wages.
Essential Coverage Components for Southcrest Residents
To achieve "the right coverage," Southcrest drivers should look beyond the basic liability requirements. A robust policy is a combination of several different protections designed to shield the policyholder from various angles of risk.
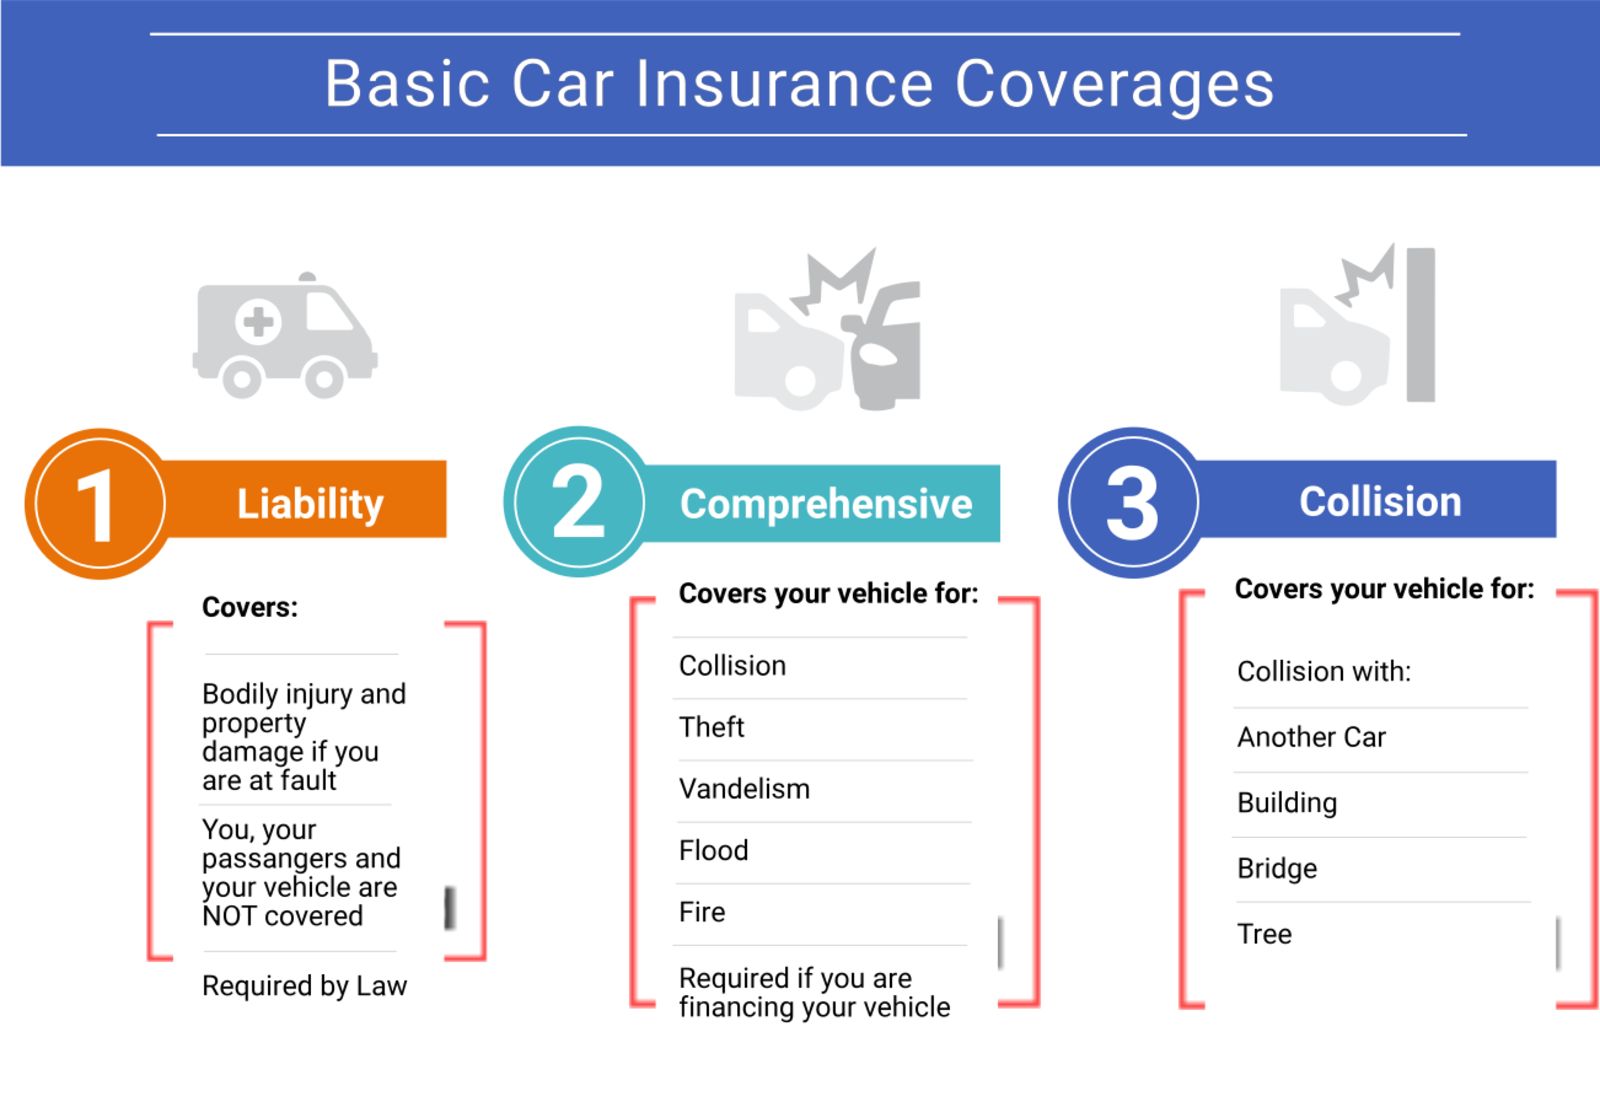
1. Bodily Injury and Property Damage Liability
This is the core of your policy. For Southcrest residents, "right coverage" typically means moving to at least 100/300/50 limits. This provides $100,000 per person for medical injuries, $300,000 per accident, and $50,000 for property damage. This level of coverage is generally sufficient to protect the average middle-class household's assets from most standard accident claims.
2. Comprehensive Coverage
Often called "other than collision," this covers damage to your car caused by events outside your control. In Southcrest, this is vital for:
- Theft: San Diego urban areas continue to see fluctuations in vehicle and catalytic converter thefts.
- Vandalism: Protection against graffiti or smashed windows.
- Environmental Factors: Damage from falling tree limbs during Santa Ana wind events or flooding near Chollas Creek during heavy winter rains.
3. Collision Coverage
Regardless of who is at fault, collision coverage pays to repair or replace your vehicle. Given the rising cost of labor and parts in 2026, having a policy that covers the Actual Cash Value (ACV) of your car is the only way to ensure you can remain mobile after a total loss.
4. Uninsured/Underinsured Motorist (UM/UIM)
This is perhaps the most important coverage for Southcrest drivers. A significant percentage of drivers in urban California operate vehicles without insurance or with only the bare minimum. If an uninsured driver hits you, your UM/UIM coverage steps into the shoes of the at-fault party’s insurance and pays for your medical bills and car repairs. Without this, you are at the mercy of a driver who likely has no assets to sue for.
Comparing Coverage Tiers: 2026 Estimates
| Coverage Type | Basic (Legal Minimum) | Standard (Recommended) | Premium (High Protection) |
|---|---|---|---|
| Bodily Injury | $15k / $30k | $100k / $300k | $250k / $500k |
| Property Damage | $5,000 | $50,000 | $100,000 |
| Uninsured Motorist | Often Declined | Matches Liability | Matches Liability |
| Comprehensive | Not Included | $500 Deductible | $250 Deductible |
| Collision | Not Included | $500 Deductible | $250 Deductible |
| Rental Car Reimb. | No | $30/day | $50/day |
The Role of Deductibles in Managing Costs
Choosing the right coverage doesn't always mean choosing the most expensive premium. Southcrest residents can manage their costs by strategically selecting deductibles. A deductible is the amount you pay out of pocket before insurance kicks in for Comprehensive or Collision claims.
In 2026, many drivers are opting for a $1,000 deductible to lower their monthly payments. However, this is only "right" if you have $1,000 readily available in an emergency fund. For residents living paycheck to paycheck, a $500 deductible is often safer, as it reduces the immediate financial shock of an accident.
Why "Cheap" Insurance Can Be More Expensive
Many secondary-market insurers offer "low-cost" policies in Southcrest. While these are legally valid, they often come with hidden costs:
- Poor Claims Handling: If you are in an accident, a budget insurer may take weeks to send an adjuster, leaving you without a car and potentially losing income from missed work.
- Limited Repair Networks: Some low-cost providers may insist on using non-OEM (Original Equipment Manufacturer) parts or shops outside of the San Diego area, which can affect your vehicle’s resale value and safety.
- Strict Policy Language: Cheap policies may have restrictive "named driver" exclusions, meaning if a family member or friend borrows your car and crashes, the claim could be denied entirely.
How to Verify Your Coverage in 2026
To ensure your coverage is "right" for your current situation, you should perform an annual insurance audit. As of 2026, the California Department of Insurance (CDI) provides online tools to verify the license status and complaint history of insurance companies.
- Check Your Declarations Page: Review the specific limits and ensure "Uninsured Motorist" is not marked as "WAIVED."
- Evaluate Your Vehicle Value: If your car is more than 10 years old, the cost of Collision coverage might exceed the car's value. Conversely, if you have a loan, ensure you have GAP Insurance to cover the difference between what you owe and what the car is worth.
- Update Your Mileage: If your commute has changed (e.g., switching to a remote job or moving to a different part of San Diego), notifying your insurer could lower your premium while maintaining high coverage limits.
Frequently Asked Questions
Does my auto insurance cover my car if it’s flooded in Southcrest?
Only if you have Comprehensive Coverage. Standard liability and collision policies do not cover environmental damage. Given that parts of Southcrest are near low-lying drainage areas, comprehensive coverage is highly recommended to protect against water damage from heavy storms.
Is street parking in Southcrest considered a "high risk" by insurance companies?
Insurers use "garaging location" (your ZIP code) as a primary rating factor. While they don't always ask specifically about street parking versus a garage, the historical data for the Southcrest area regarding theft and hit-and-runs will already be factored into your premium. Having the "right coverage" like Comprehensive and UM/UIM protects you from the very risks that make the ZIP code's rates what they are.
Can I get away with just the California minimum limits if I don't own a home?
It is a common misconception that you only need high liability limits if you have real estate. In California, a judgment against you can last for 10 years and be renewed for another 10. This means a court can garnish your future wages or seize future assets you haven't even acquired yet. High coverage protects your future earning potential, not just your current bank account.
Why did my Southcrest auto insurance rate go up in 2026?
Several factors are likely at play: the increased cost of high-tech vehicle parts, a statewide increase in labor rates for mechanics, and a rise in "nuclear verdicts" where juries award massive settlements for injury claims. Even if your driving record is clean, the collective risk of the San Diego area influences your individual rate.
Does "the right coverage" include roadside assistance?
While not a legal requirement, roadside assistance is a low-cost addition (often less than $10 a year) that is worth it for Southcrest residents. If your car breaks down on the I-5 during rush hour, the cost of a private tow can easily exceed $200. Insurance-provided roadside assistance can save significant money and stress.
Final Recommendation for Southcrest Drivers
For residents of Southcrest, the "right" coverage is a policy that includes 100/300/50 liability limits, Uninsured Motorist protection, and Comprehensive/Collision with a manageable deductible. Before renewing your current policy, compare quotes from at least three different carriers, paying close attention to their claims-handling reputation in San Diego. If you are financing a vehicle, ensure GAP insurance is included to prevent a total loss from becoming a long-term debt. Investing an extra $20 to $40 per month now can prevent a financial catastrophe that could take decades to recover from.
Image Gallery
Select an image to open it in a new tab.


Akira Tanaka
International Academic Trends Correspondent
