Life Insurance That Covers Diabetics Explained: Navigating Eligibility and Options
Securing life insurance when living with diabetes is not only possible but increasingly common. While insurers evaluate the condition based on factors like blood sugar control, type of diagnosis, and presence of complications, many people with diabetes qualify for standard coverage. The key is understanding how underwriters assess medical history to determine your eligibility and premium rates.
Understanding How Diabetes Influences Insurance Underwriting
When you apply for life insurance, insurance companies perform a process called underwriting. The goal is to determine your risk profile—essentially, the statistical likelihood of a claim being filed during the term of the policy. Because diabetes is a chronic condition that can lead to long-term health complications, it is categorized as a "rated" or "table-rated" condition by many underwriters.
Underwriters do not look at a diagnosis of diabetes in isolation. Instead, they look at the "control" of the disease. A person with well-managed Type 2 diabetes who exercises regularly and maintains healthy blood glucose levels may often be offered standard, or even "preferred," rates, depending on the carrier. Conversely, someone with poorly managed Type 1 diabetes, or someone with Type 2 diabetes that has already resulted in complications like neuropathy, retinopathy, or cardiovascular issues, may be offered "substandard" rates or limited to specific types of policies.
The assessment generally involves reviewing your Medical Information Bureau (MIB) report, your pharmacy records, and potentially an attending physician’s statement (APS). The APS provides the insurer with a detailed look at your A1C levels, frequency of doctor visits, and any medications or insulin regimens you currently utilize.
Types of Diabetes and Their Impact on Coverage
The distinction between the type of diabetes you have is critical to the underwriting process.
Type 1 Diabetes
Type 1 diabetes is an autoimmune condition that requires exogenous insulin. Because it usually presents earlier in life and has a longer duration of impact on the body's systems, underwriters often view Type 1 diabetes as higher risk. However, significant advancements in medical technology, such as continuous glucose monitors (CGMs) and insulin pumps, have made it much easier for applicants to demonstrate consistent control. Insurance companies are increasingly receptive to applicants who can show that they are actively managing their condition and have a long history of stable A1C levels.
Type 2 Diabetes
Type 2 diabetes is more common and is often manageable through diet, exercise, and oral medication. If your condition is diagnosed later in life and you have successfully managed it without significant health complications, your chances of obtaining a competitive rate are high. Underwriters focus heavily on your weight, blood pressure, and cholesterol levels in addition to your A1C to assess your overall cardiovascular risk.
Gestational Diabetes
Gestational diabetes occurs during pregnancy and usually resolves after childbirth. In most cases, if you have fully recovered and have normal glucose tests post-pregnancy, this should not negatively impact your ability to get standard insurance rates in the future.
Policy Types: Term vs. Permanent Insurance
Depending on the severity of your diabetes and the insurer’s risk assessment, you may be eligible for different types of life insurance products.
- Term Life Insurance: This provides coverage for a specific period (e.g., 10, 20, or 30 years). If your diabetes is well-managed, this is often the most cost-effective way to secure high coverage amounts.
- Permanent Life Insurance (Whole or Universal): These policies stay in effect for your entire life and include a cash value component. These are often preferred for estate planning, though the premiums are higher than term life insurance.
- Guaranteed Issue Life Insurance: If you have been declined by traditional carriers due to medical complications, guaranteed issue policies are an alternative. These require no medical exam and have no health questions. However, they usually come with lower coverage limits (often capped at $25,000 to $50,000) and a "graded benefit" period, meaning the full death benefit may not be paid out if you die within the first two or three years of the policy.
Comparison of Coverage Options for Diabetics
| Policy Type | Medical Exam | Approval Speed | Coverage Amount | Premium Costs |
|---|---|---|---|---|
| Fully Underwritten | Required | Slow (weeks) | High (Flexible) | Lowest |
| Simplified Issue | No | Fast (days) | Moderate | Moderate |
| Guaranteed Issue | No | Instant | Low (Limited) | Highest |
Documentation and Preparation: Improving Your Odds
To secure the best possible rates, you must be prepared to provide clear evidence of your health status. Being proactive during the application process can significantly influence the underwriter's decision.
- Gather Your Medical Data: Before applying, know your recent A1C levels. If your A1C has been high recently due to a temporary health issue, it may be worth waiting until you have a few months of stable, lower readings before submitting an application.
- Document Lifestyle Habits: Be prepared to provide details on your exercise routine, diet, and any habits that positively impact your condition. Insurers look for evidence that you are working with an endocrinologist or primary care physician to stay on top of your health.
- Use an Independent Broker: Work with an insurance broker who has specific experience with "impaired risk" underwriting. These brokers know which carriers are more lenient regarding diabetes and can help you submit a "pre-screen" or informal inquiry to multiple companies without having to undergo multiple formal medical exams.
- Be Honest on Your Application: Never hide a diagnosis or lie about your medication usage. Pharmacy checks will reveal what medications you are taking, and a discrepancy between your application and your medical history will result in an automatic decline.
Common Pitfalls and Troubleshooting
One of the most common mistakes applicants make is applying for the wrong type of policy too quickly. If you have been turned down by one carrier, do not rush to apply to another immediately. Every rejection goes on your MIB file, which future insurers can see. Instead, consult with a professional to understand why the decline happened and whether that reason is specific to one carrier's guidelines or if it is a broader issue that needs to be addressed through better medical management.
Another common error is failing to maintain regular check-ups. Insurers view an applicant who has not seen a doctor in two years as a "high risk" regardless of their condition. Regular documentation of your health status by a medical professional is the best proof of "stability" that an underwriter can ask for.
Frequently Asked Questions
Will my premiums be higher because I have diabetes? In many cases, yes. Unless your diabetes is very mild and well-controlled, insurers may apply a "table rating" or a flat extra charge to your premiums to account for the additional risk. However, with good control, these increases can be kept minimal.
Can I get life insurance without a medical exam? Yes, "Simplified Issue" and "Guaranteed Issue" policies do not require medical exams. However, they are generally more expensive for the amount of coverage you receive compared to fully underwritten policies.
What is an A1C, and why is it important to insurers? A1C is a blood test that measures your average blood sugar levels over the past two to three months. It is the primary metric insurers use to gauge how well you are managing your diabetes over time.
If I develop diabetes after buying a policy, does it affect my coverage? No. Once your policy is in force, your premium and death benefit are locked in. As long as you continue to pay your premiums, the insurer cannot cancel your policy or increase your rates based on a new diagnosis or changes in your health.
Does an insulin pump disqualify me from standard coverage? No. Most insurers today recognize that insulin pumps and CGMs are tools for better health management. Using these devices does not automatically disqualify you, and in some cases, it can actually help demonstrate your commitment to strict glucose control.
Next Steps for Applicants
If you are currently looking for life insurance as a diabetic, your first step should be to organize your health records. Request a summary from your endocrinologist that outlines your diagnosis date, current medication, recent A1C history, and any absence of secondary complications. Once you have this, contact a licensed, independent life insurance agent who specializes in high-risk or impaired-risk cases. Ask them to perform an anonymous inquiry across multiple carriers to see which company is most likely to offer you the most favorable rating based on your specific medical profile. By preparing your documentation ahead of time, you put yourself in the best position to secure the financial protection you and your family deserve.
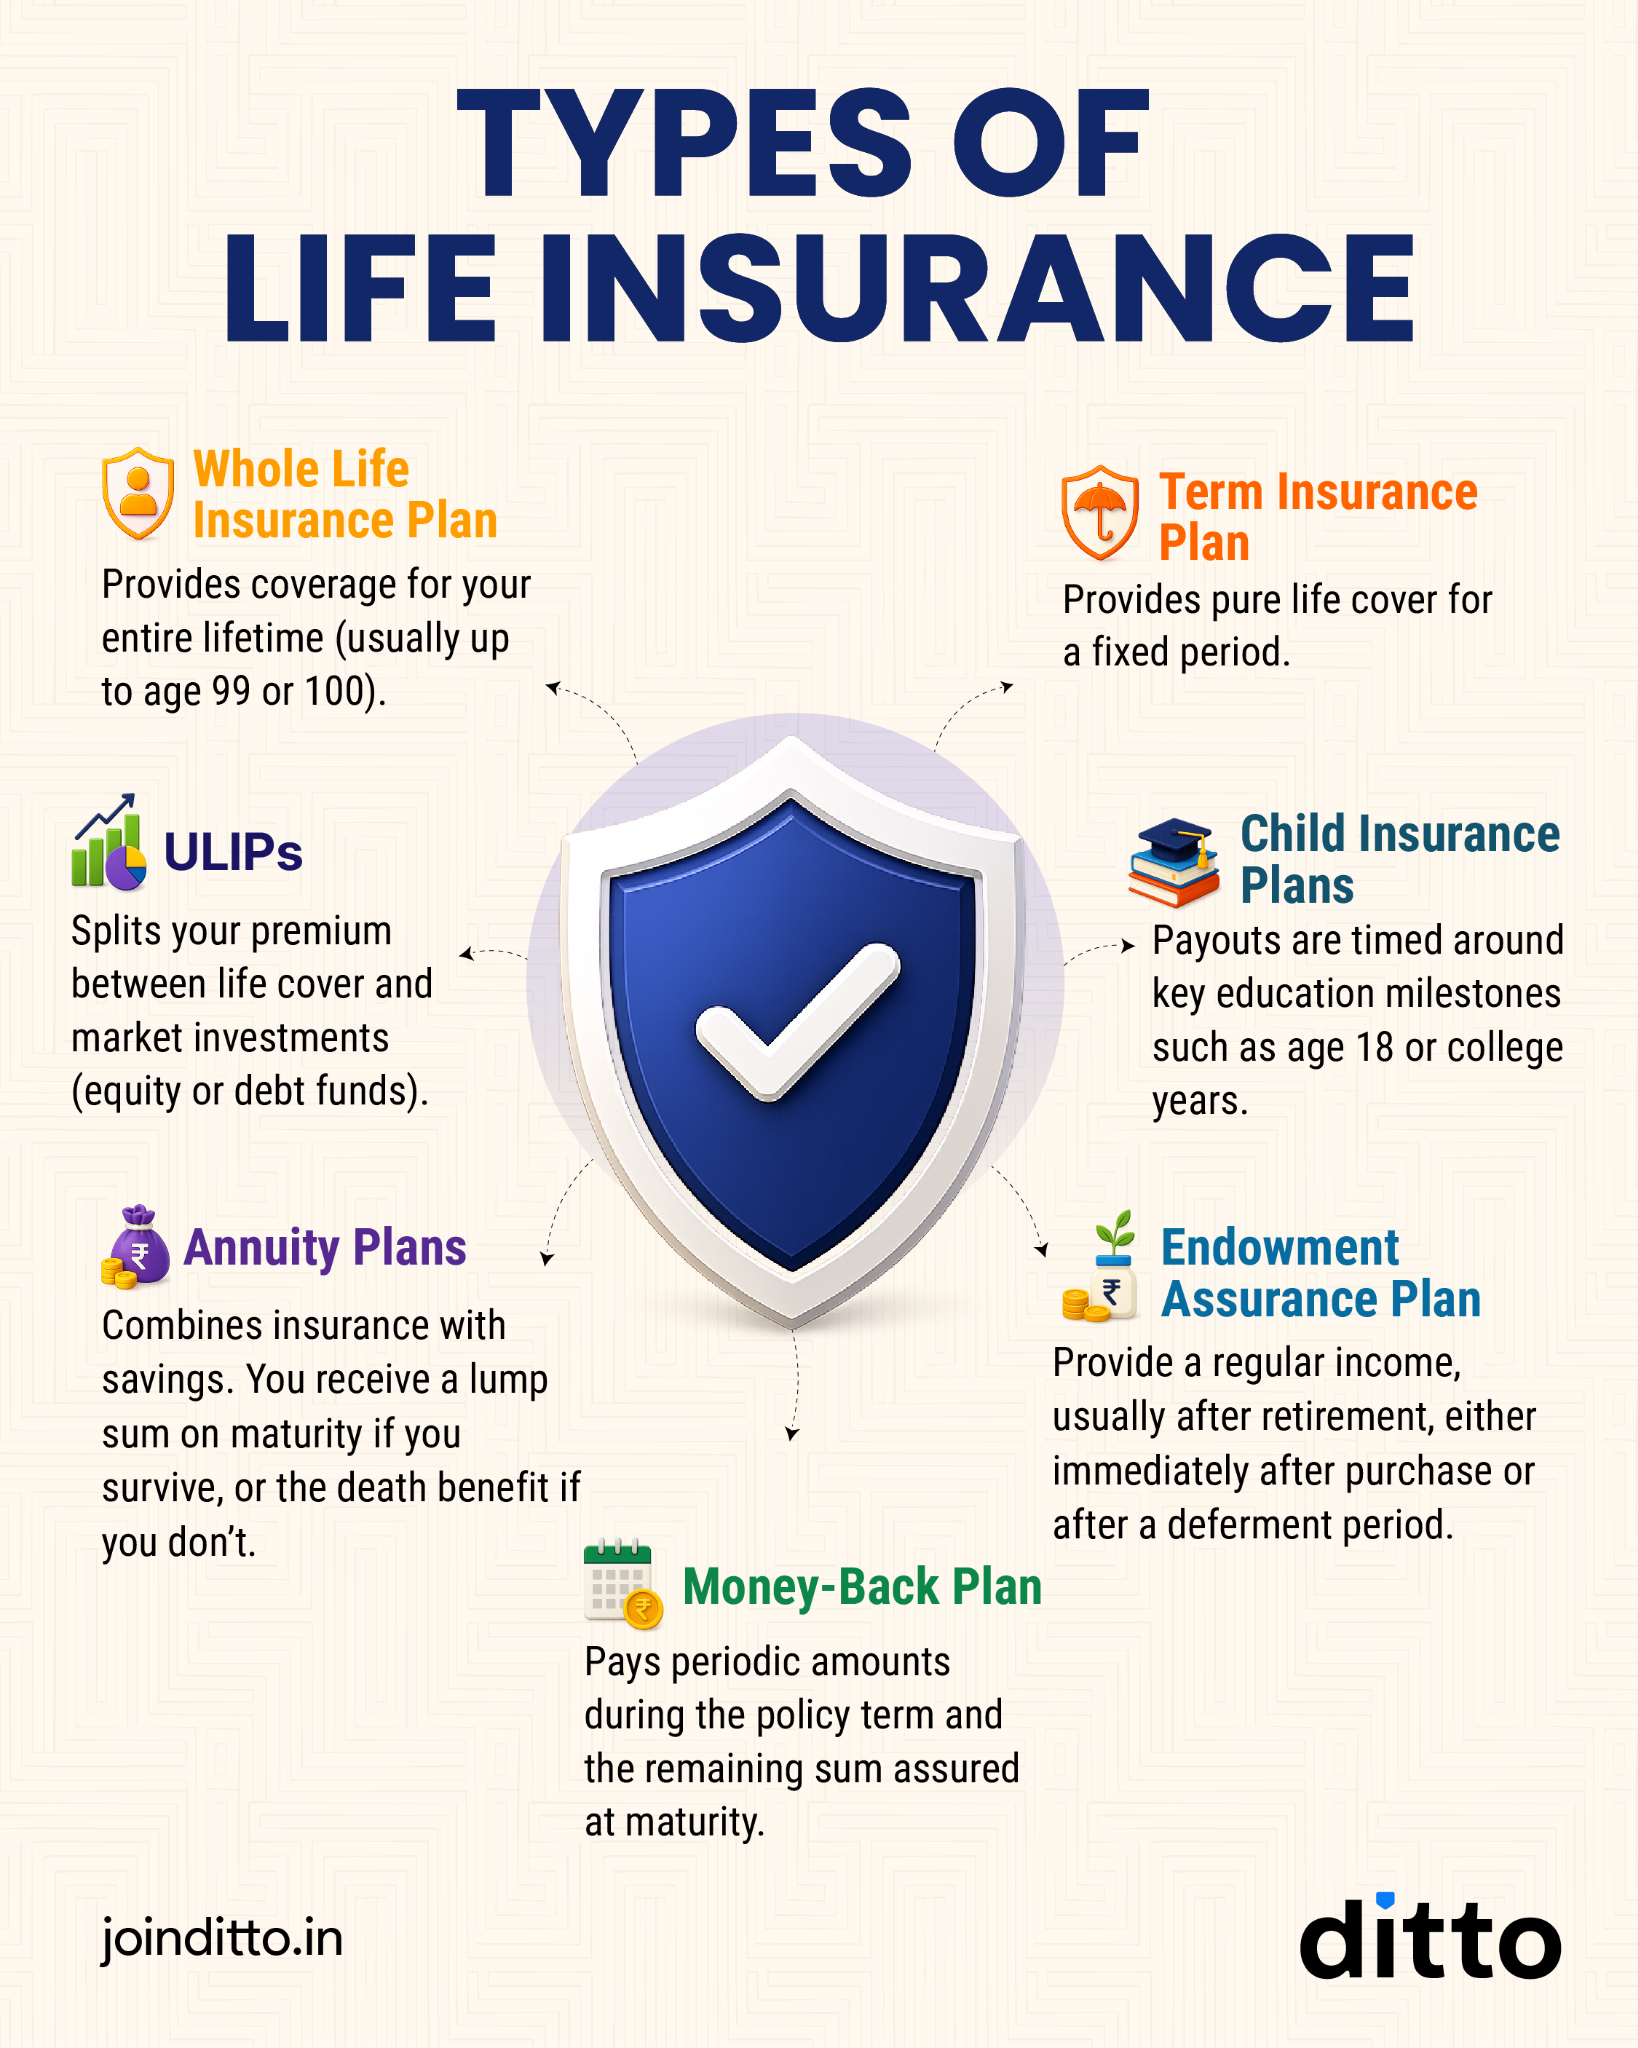
Image Gallery
Select an image to open it in a new tab.

Simon Caldwell
Enterprise Technology and Systems Editor
