Your Auto-Owners Insurance Declaration Page: A Comprehensive Guide to Understanding and Managing Your Coverage in 2026

An Auto-Owners Insurance declaration page is a concise summary of your specific car insurance policy, detailing who is covered, which vehicles are insured, and the exact limits of your protection. Often referred to as the "dec page," it serves as your official proof of coverage and the primary document for verifying policy details with lenders or state registries.
As we navigate the insurance landscape in 2026, the declaration page remains the most critical document in your insurance portfolio. While your full policy booklet contains the "fine print" and legal definitions, the declaration page is the personalized roadmap that tells you exactly what you are paying for. For policyholders with Auto-Owners Insurance—a company renowned for its "No Problem" claims service and commitment to the independent agency model—understanding this document is essential for ensuring your assets are adequately protected.
The Purpose and Importance of the Declaration Page
The declaration page is typically the first page of your policy renewal or new business packet. It is not the insurance contract itself, but rather a summary of the choices you made when purchasing the policy. In 2026, where digital integration is at an all-time high, your Auto-Owners dec page is available both as a physical document and a secure digital file within your Customer Center portal.
This document serves several vital functions. First, it provides immediate verification of coverage for law enforcement or Department of Motor Vehicles (DMV) inquiries. Second, if you are financing or leasing a vehicle, your lienholder or lessor will require a copy of this page to ensure their financial interest is protected through comprehensive and collision coverages. Finally, it acts as a quick-reference guide during the claims process, allowing you to see your deductibles and coverage limits without digging through hundreds of pages of legal terminology.
How to Access Your Auto-Owners Declaration Page
Auto-Owners Insurance continues to emphasize the value of the independent agent, but they have also streamlined digital access to essential documents. There are three primary ways to retrieve your declaration page in 2026:
1. The Auto-Owners Customer Center
The most efficient way to access your documents is through the online Customer Center. Once you log in, you can navigate to the "Documents" or "Policy Information" section. From there, you can view, download, or print your current declaration page as a PDF. This digital version is legally identical to the paper copy mailed to your home.
2. The Auto-Owners Mobile App
For policyholders on the go, the Auto-Owners mobile app provides instant access to digital insurance cards and declaration pages. This is particularly useful if you are at a car dealership or a repair shop and need to verify your coverage limits or deductibles immediately. The app allows you to email the PDF directly to a third party, such as a mortgage broker or a rental car agency.
3. Your Independent Insurance Agent
Unlike many "direct-to-consumer" insurance companies, Auto-Owners operates exclusively through independent agents. Your agent is a local professional who understands the specific insurance requirements of your state. If you have questions about your declaration page or need a certified copy, your agent can provide it quickly. They can also explain the nuances of your coverage and suggest adjustments based on your current financial situation.

Breaking Down the Key Sections of the Dec Page
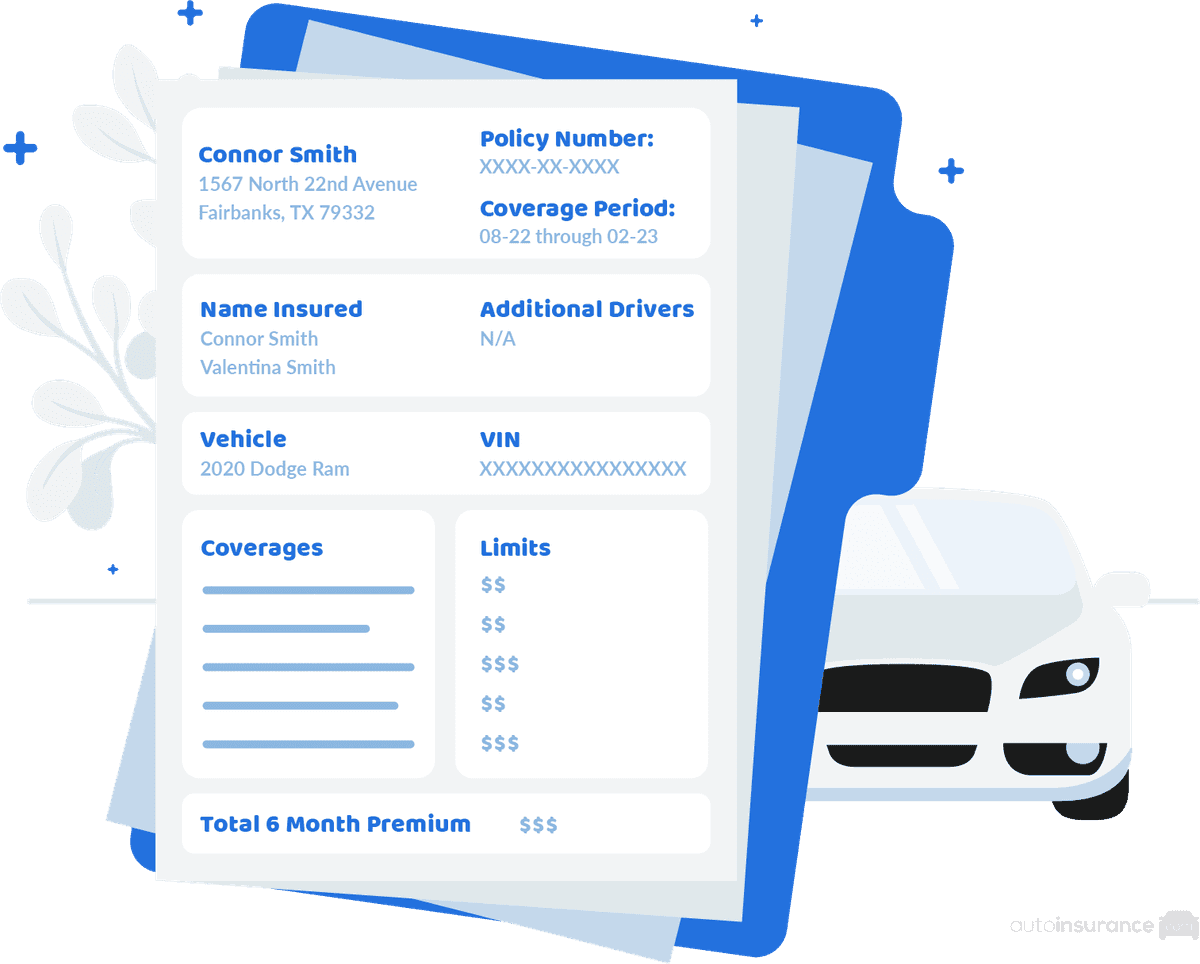
An Auto-Owners declaration page is organized into several distinct blocks of information. Understanding how to read these sections ensures you aren't surprised by coverage gaps after an accident.
Policy Period and Account Information
At the top of the page, you will find your policy number and the "Policy Period." In 2026, most personal auto policies are written for six-month or twelve-month terms. It is crucial to check the "Effective Date" and "Expiration Date." Coverage begins at 12:01 A.M. on the effective date and ends at 12:01 A.M. on the expiration date. If you are switching carriers, ensure there is no gap between these times.
Named Insureds and Rated Drivers
The "Named Insured" is the person (or persons) who owns the policy and has the authority to make changes. Below this, you will see a list of "Rated Drivers." These are the individuals in your household whose driving records and demographics were used to calculate your premium. It is a common mistake to leave licensed teenagers or live-in relatives off this list, which can lead to complications or even denial of coverage during a claim.
Scheduled Vehicles and VINs
Each vehicle covered under the policy will be listed with its year, make, model, and Vehicle Identification Number (VIN). In 2026, with the proliferation of electric vehicles and advanced driver-assistance systems (ADAS), ensuring your VIN is correct is more important than ever. The VIN tells the insurance company exactly what safety features your car has, which can significantly impact your premium and the accuracy of a total-loss settlement.
Coverage Limits and Premiums
This is the "meat" of the declaration page. Each vehicle will have its own set of coverages, and the premium for each coverage is usually itemized.
- Bodily Injury Liability: Shown as a split limit (e.g., $100,000/$300,000). The first number is the maximum paid per person, and the second is the maximum paid per accident.
- Property Damage Liability: The maximum amount Auto-Owners will pay for damage you cause to someone else's property.
- Collision Coverage: This pays for damage to your car resulting from a crash. It will be listed with a deductible (e.g., $500 or $1,000).
- Comprehensive (Other Than Collision): This covers theft, fire, vandalism, or animal strikes.
- Uninsured/Underinsured Motorist: This protects you if you are hit by someone with no insurance or insufficient limits.
Summary of Common Auto-Owners Coverage Options
The following table outlines the standard coverages typically found on an Auto-Owners declaration page and what they mean for the policyholder.
| Coverage Type | What It Protects | Common 2026 Limits/Deductibles |
|---|---|---|
| Bodily Injury Liability | Others' medical bills if you are at fault. | $250,000 / $500,000 |
| Property Damage | Others' property (cars, fences, buildings). | $100,000 |
| Collision | Your vehicle's repair after an accident. | $500 or $1,000 Deductible |
| Comprehensive | Your vehicle's repair from non-collision events. | $250 or $500 Deductible |
| Medical Payments | Your (and your passengers') medical bills. | $5,000 to $10,000 |
| Roadside Assistance | Towing, flat tires, and lockouts. | Included or Flat Fee |
| Loan/Lease Gap | The "gap" between ACV and what you owe. | Actual Debt Amount |
Specialized Addendums and Endorsements
Auto-Owners is known for offering a variety of endorsements that can be added to a standard policy. These will be listed toward the bottom of your declaration page. In 2026, some of the most common additions include:
Personal Automobile Plus Package
This is a popular Auto-Owners bundle that includes several enhancements, such as identity theft protection, cell phone replacement coverage, and increased limits for transportation expenses (rental car reimbursement). If you see "Personal Auto Plus" on your dec page, you have a higher tier of protection than a basic policy.
Diminishing Deductible
If you have remained accident-free, you might see a "Diminishing Deductible" credit. This endorsement reduces your collision deductible for every year you drive safely, potentially bringing it down to $0 over time.
New Value/Full Investment Coverage
For those who have purchased a new vehicle in 2026, this endorsement is critical. It ensures that in the event of a total loss within the first year or two of ownership, Auto-Owners will pay for a new car of the same make and model, rather than just the depreciated actual cash value (ACV).
Identifying Discounts and Surcharges
Transparency in pricing is a hallmark of the declaration page. Below the coverage section, Auto-Owners typically lists the discounts that have been applied to your premium. In 2026, these often include:
- Multi-Policy Discount: If you bundle your home, life, or business insurance with Auto-Owners.
- Paid-In-Full Discount: A significant reduction for paying the entire annual or semi-annual premium upfront.
- Safety Feature Discounts: Credits for vehicles equipped with autonomous braking, lane-keep assist, and advanced anti-theft systems.
- Good Student Discount: For young drivers who maintain a certain GPA.
Conversely, any "surcharges" will also be noted. These are temporary increases in your premium due to at-fault accidents or moving violations. The dec page should specify how long these surcharges will remain on your policy.
The Role of Lienholders and Lessors
If you do not own your vehicle outright, your declaration page will include a "Loss Payee" or "Lienholder" section. This lists the financial institution that holds the title to your car. By listing them on the declaration page, Auto-Owners agrees to include the lender on any claim checks for significant physical damage to the vehicle.
In 2026, most lenders require "Evidence of Insurance" that matches the requirements of the loan agreement. Usually, this means carrying a maximum deductible of $1,000 and maintaining comprehensive and collision coverage. If your declaration page shows that you have dropped these coverages, your lender may "force-place" insurance on your behalf, which is significantly more expensive and provides less protection.
Troubleshooting Common Errors on Your Dec Page
Because the declaration page is the basis for your legal protection, even a small error can cause significant headaches. When you receive your 2026 renewal, check for the following:
- Garaging Address: If you have moved, ensure the address where the car is parked at night is correct. Insurance rates are based on zip codes, and an incorrect address could be seen as "rate evasion" or misrepresentation.
- Usage Classification: Ensure your car is listed correctly as "Pleasure," "Commute," or "Business." Using a vehicle for ride-sharing (like Uber or Lyft) without a specific endorsement can lead to a total denial of coverage.
- Excluded Drivers: If you have specifically excluded a high-risk household member from your policy to save money, they will be listed as an "Excluded Driver." Ensure this list is accurate, as there is zero coverage if an excluded person gets behind the wheel.
- Deductible Amounts: Ensure your deductibles align with your emergency fund. If you have a $1,000 deductible but only $500 in savings, you may struggle to get your car repaired after an accident.
Frequently Asked Questions
Is a declaration page the same as an insurance card?
No. While an insurance card is a small document (digital or paper) meant to be kept in the vehicle for immediate proof of insurance, the declaration page is a much more detailed document. The dec page includes your specific coverage limits, deductibles, and premium costs, which are not found on a standard ID card.
How often should I review my Auto-Owners declaration page?
You should review your declaration page every time your policy renews (usually every six or twelve months) or whenever you have a major life event, such as buying a new car, moving, or adding a new driver to your household. In 2026, it is also wise to review it if you have made significant safety upgrades to your vehicle.
Can I use my declaration page to switch to another insurance company?
Yes. When shopping for new insurance, providing your current Auto-Owners declaration page to a new agent allows them to provide an "apples-to-apples" comparison. It ensures the new quote includes the same limits and coverages you currently have, allowing you to see if you are truly saving money.
Why is my lender's name on my declaration page?
If you have a car loan or lease, the lender has a financial stake in the vehicle. They are listed as a "Lienholder" or "Loss Payee" to ensure they are compensated if the vehicle is totaled. This also ensures that Auto-Owners notifies the lender if your policy is canceled for non-payment.
Does the declaration page show my full policy language?
No. The declaration page is only a summary. The full policy consists of the declaration page, the policy booklet (which contains general terms and exclusions), and any specific endorsements or state-specific amendments. You must read all these documents together to understand your full legal rights and responsibilities.
Final Recommendation: Maintain a Digital and Physical File
In 2026, the ease of digital access is a great convenience, but it is not a complete substitute for organization. We recommend downloading a PDF copy of your Auto-Owners Insurance declaration page at every renewal and saving it to a secure cloud storage folder. Simultaneously, keep a printed copy in your home's fire-safe box or a dedicated insurance file. This ensures that even in the event of a technical outage or an emergency where you cannot access your phone, you have the vital information needed to contact your agent and begin the recovery process.
Image Gallery
Select an image to open it in a new tab.



Vivian Cho
Executive IT and Emerging Technologies Reporter
