
Achieving financial freedom is the process of building enough passive income or liquid assets to cover your cost of living without being dependent on active employment. This goal is reached by systematically reducing debt, maximizing personal savings rates, diversifying investment portfolios, and ensuring your total annual expenses are supported by consistent, non-labor-based cash flows.
Understanding Financial Freedom in 2026
Financial freedom is often misunderstood as sudden wealth or an immediate exit from the workforce. In reality, it is a quantifiable state of solvency where your net worth or the yield from your assets generates enough capital to sustain your chosen lifestyle indefinitely. As of 2026, economic conditions—characterized by fluctuating interest rates and varying inflation benchmarks—demand a disciplined, data-driven approach to personal finance rather than speculative strategies.
The journey requires a departure from traditional "paycheck-to-paycheck" living. It necessitates moving through distinct stages: from basic survival and debt elimination to capital accumulation and, eventually, portfolio optimization.
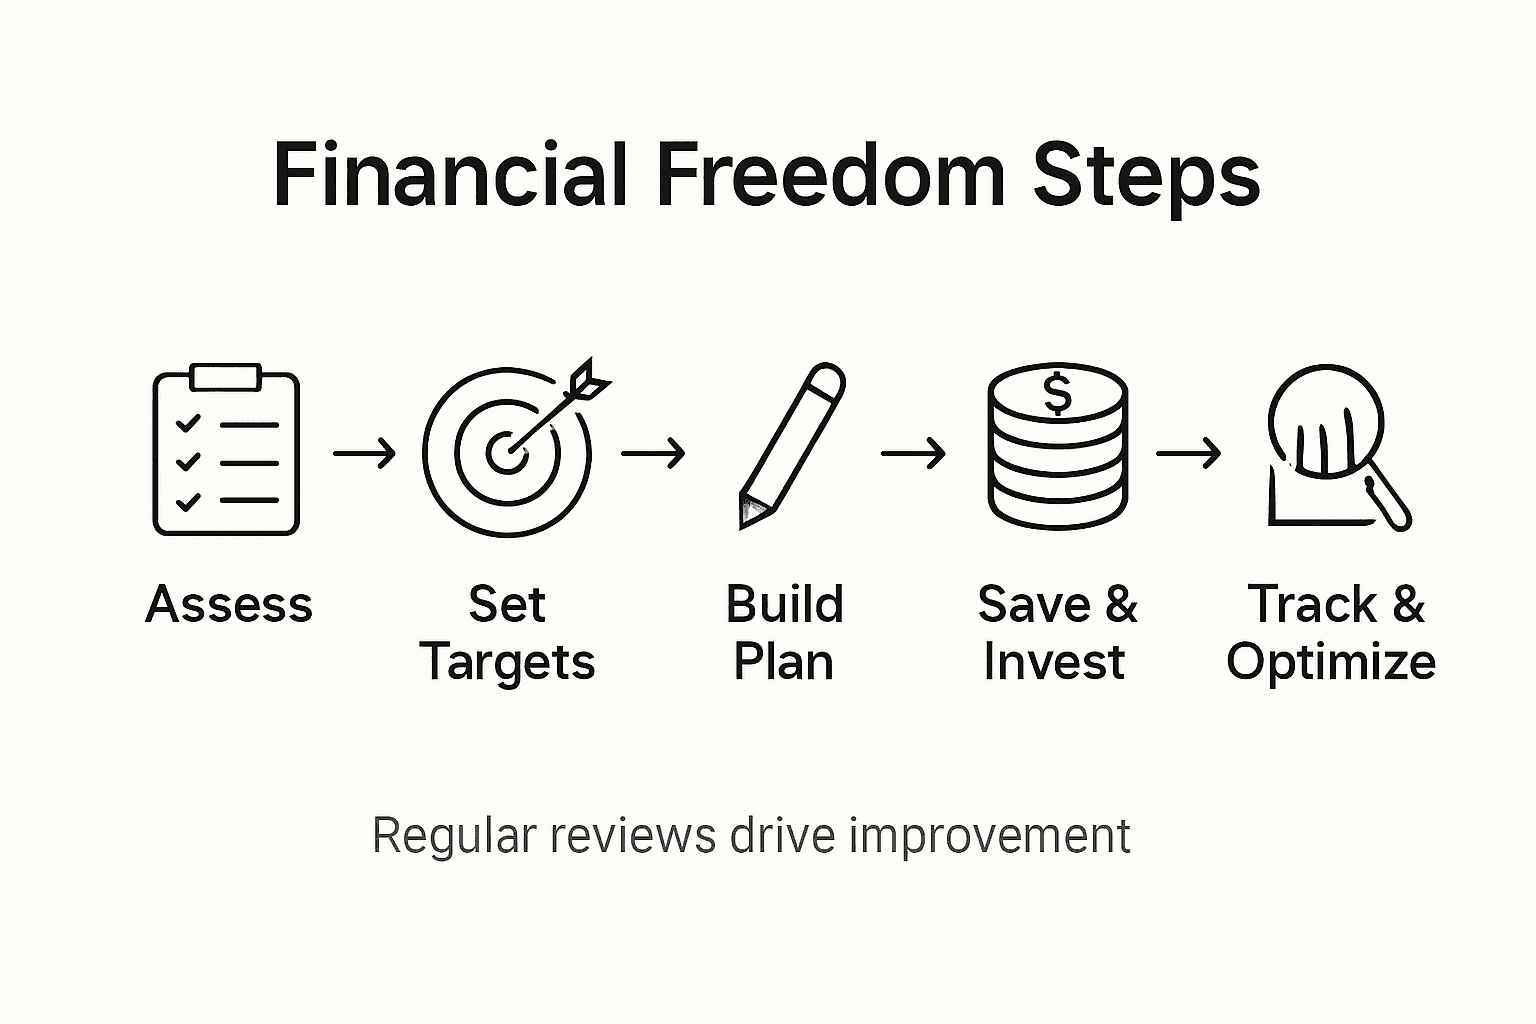
Step 1: Conducting a Comprehensive Financial Audit
Before setting goals, you must establish a baseline. You cannot manage what you do not measure. A financial audit involves creating a detailed ledger of your current economic state.
- Net Worth Statement: List all assets (cash, brokerage accounts, retirement funds, real estate equity) and subtract all liabilities (mortgage balances, student loans, credit card debt, auto loans).
- Cash Flow Analysis: Track every dollar of income and expenditure for three months. Categorize spending into "Fixed Needs" (rent/mortgage, utilities, insurance) and "Variable Wants" (entertainment, dining out, luxury subscriptions).
- Debt-to-Income Ratio (DTI): Calculate your monthly debt payments divided by your gross monthly income. A lower DTI is essential for qualifying for favorable financing terms as you scale your investments.
Step 2: Establishing a Secure Foundation
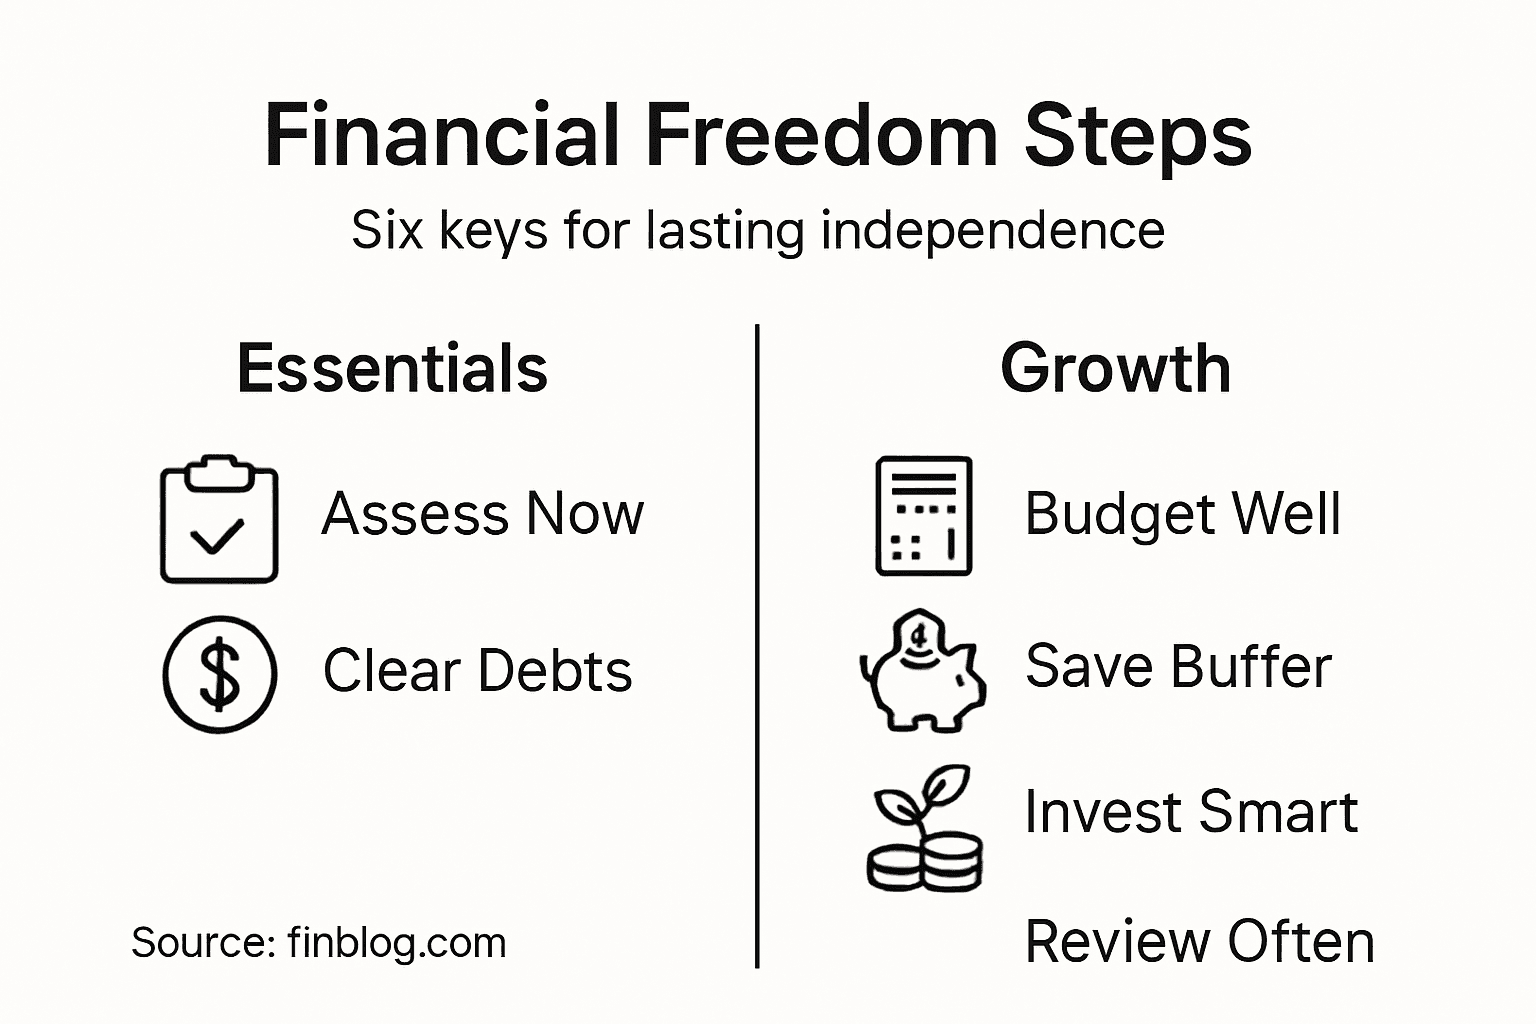
Before investing in volatile markets, you must secure your financial perimeter. This prevents life’s inevitable emergencies from forcing you into high-interest debt.
- The Emergency Fund: Maintain 3–6 months of living expenses in a High-Yield Savings Account (HYSA). In 2026, these accounts continue to provide liquidity while offering a hedge against inflation. This fund is not an investment; it is insurance against job loss or unexpected health costs.
- High-Interest Debt Elimination: Debt with interest rates exceeding 7–8% is a guaranteed negative return on your money. Utilize the "Avalanche Method" (paying off the highest interest rates first) to mathematically minimize the total interest paid over time.
Step 3: Optimizing Your Savings Rate
Financial freedom is accelerated by the gap between your income and your expenses. While increasing income is important, controlling the "burn rate" of your lifestyle is the most controllable variable in your journey.
To optimize, adopt the 50/30/20 rule as a starting point: 50% of net income to needs, 30% to wants, and 20% to savings and investments. As you progress toward financial independence, many practitioners aim to invert this, pushing the savings rate toward 40% or 50% of total income.
Step 4: Strategic Investing for Long-Term Growth
Once your foundation is set, capital must be deployed where it can compound. Compound interest is the primary mechanism of wealth accumulation. In the 2026 market environment, the focus remains on low-cost, tax-efficient vehicles.
| Investment Vehicle | Typical Risk Profile | Purpose |
|---|---|---|
| Index Funds (ETFs) | Moderate | Broad market exposure and long-term growth. |
| Tax-Advantaged Accounts (401k/IRA) | Low to Moderate | Tax-deferred growth or tax-free withdrawals. |
| Real Estate (REITs/Direct) | Moderate to High | Cash flow and appreciation. |
| Government Bonds | Low | Capital preservation and income. |
When selecting investments, prioritize diversification across sectors, geographies, and asset classes to mitigate idiosyncratic risk. Rebalancing your portfolio annually ensures that your risk tolerance remains aligned with your age and proximity to your freedom milestone.
Comparative Analysis of Wealth-Building Strategies
Investors often choose between different philosophies. Understanding these helps in tailoring a plan to your specific circumstances.
- The Aggressive Accumulator: Prioritizes early retirement (FIRE - Financial Independence, Retire Early). Focuses on extreme frugality and aggressive index fund investing to reach the "4% rule" threshold—the point where you can withdraw 4% of your portfolio annually without depleting it.
- The Income Investor: Focuses on dividend-paying stocks and rental properties. The goal here is to replace a monthly salary with monthly cash flow, prioritizing stability over explosive capital appreciation.
- The Hybrid Approach: A mix of growth assets (stocks) to outpace inflation and income assets (bonds/real estate) to provide a "floor" of safety. This is generally the most sustainable approach for most individuals.
Common Pitfalls and Troubleshooting
Even with a plan, external and internal factors can derail progress. Recognizing these early is key to maintaining trajectory.
- Lifestyle Inflation: As your income grows, the temptation to increase spending—known as "lifestyle creep"—is the single greatest threat to financial freedom. If you raise your spending in lockstep with your raises, your path to freedom will never shorten.
- Tax Inefficiency: Failing to utilize tax-advantaged accounts (such as a 401(k), Roth IRA, or HSA) means losing a significant percentage of your returns to the IRS annually. Always fill tax-advantaged buckets before moving to taxable brokerage accounts.
- Market Timing: Trying to predict market peaks and valleys is statistically ineffective for individual investors. Instead, employ Dollar Cost Averaging (DCA), which involves investing a fixed amount at regular intervals, regardless of market volatility.
Important Considerations: Financial Advice
While these steps provide a structural framework, personal finance is inherently personal. Tax laws are subject to change, and specific jurisdictions impose different rules on capital gains and retirement withdrawals. If your financial situation involves complex estate planning, business ownership, or significant tax liabilities, consult with a Certified Financial Planner (CFP) or a licensed tax professional. Professional guidance is particularly important as you transition from the "accumulation" phase to the "decumulation" or "maintenance" phase of your journey.
Frequently Asked Questions
What is the "4% Rule" and is it still relevant in 2026? The 4% rule suggests you can safely withdraw 4% of your initial portfolio balance (adjusted for inflation) annually for 30 years without running out of money. While market conditions change, it remains a valuable benchmark for estimating how large a "nest egg" you need to build before considering yourself financially free.
How much do I need to save to be considered financially free? A common metric is 25 times your annual expenses. If you spend $60,000 per year, your target goal is $1.5 million in investable assets. This figure will vary based on your expected lifestyle, inflation expectations, and your withdrawal rate.
Should I pay off my mortgage or invest extra money? This is a comparison between your mortgage interest rate and the expected return of your investments. If your mortgage rate is low (e.g., 3%) and market returns are historically higher (e.g., 7–8%), it is often mathematically superior to invest. However, the psychological benefit of being "debt-free" may outweigh the math for many individuals.
What is the biggest mistake people make when trying to achieve financial freedom? The most common mistake is impatience. Financial freedom is rarely achieved through "get rich quick" schemes. It is the result of consistent, often boring, long-term saving and investing habits practiced over years or decades.
How do I adjust my strategy if I have a high-income but high-debt lifestyle? Focus on "debt consolidation" or refinancing to lower interest rates while aggressively directing surplus income to the highest-interest balances. Treat debt repayment as your most important "investment" until the high-interest liabilities are cleared.
Next Action: Start Today
The most effective way to begin your journey is to calculate your "Financial Freedom Number"—the total amount of assets you need to sustain your lifestyle. Open a dedicated spreadsheet or use a secure financial tracking app to list your current assets and debts. By establishing your starting point today, you turn an abstract concept into a concrete, measurable project. Schedule a monthly "money date" with yourself to review your spending, check your savings rate, and ensure your investment portfolio remains balanced according to your risk appetite.
Image Gallery
Select an image to open it in a new tab.



Zara El-Hashem
Sociocultural Dynamics and Academics Writer
